









Tariffs can raise the Canadian cost of some vehicles, parts and construction materials, which can feed into insurance claim costs. They don't automatically raise premiums, and the tariff schedule can change quickly. To prepare this guide, our editorial team reviewed the Department of Finance Canada’s August 25, 2026 tariff announcement, the Bank of Canada’s July 2026 Monetary Policy Report, FSRA’s explanation of Ontario auto insurance rate approvals, and the Insurance Bureau of Canada’s submission on current auto claims costs.
How Could U.S. Tariffs Affect Insurance Costs in Canada?
Tariffs can influence insurance costs when the cost and/or availability of goods needed to repair or replace an item changes. Examples of ways tariffs could impact insurance premiums include tariffs on auto parts, replacement vehicles, steel, aluminum, etc.
There is no indication that insurers are increasing premiums across Canada by the same percentage and/or on the same effective dates. Changes will vary by covered products, exemptions, exchange rates, supplier reactions, existing inventories, claim frequency, individual insurers’ experience, and provincial legislation.
Current Canadian Tariff Position
On August 25, Finance Canada noted that U.S. tariffs of 50% came into force on August 22 on Canadian goods worth $27.6 billion, and that Canada’s targeted countermeasures of 15%, 25% and 50% will come into force on September 8.
Canada’s countermeasures, its countertariffs on the automotive sector, measures on steel and aluminum and the remission framework are all part of its tariff policy. However, Canada’s tariff policies and the products they apply to can still change.
Check current tariff notices before estimating repair costs or insurance impact, as tariff classifications, effective dates, exclusions, remissions, and other factors will affect the outcome.
Why Tariffs Are a Concern for the Canadian Insurance Industry
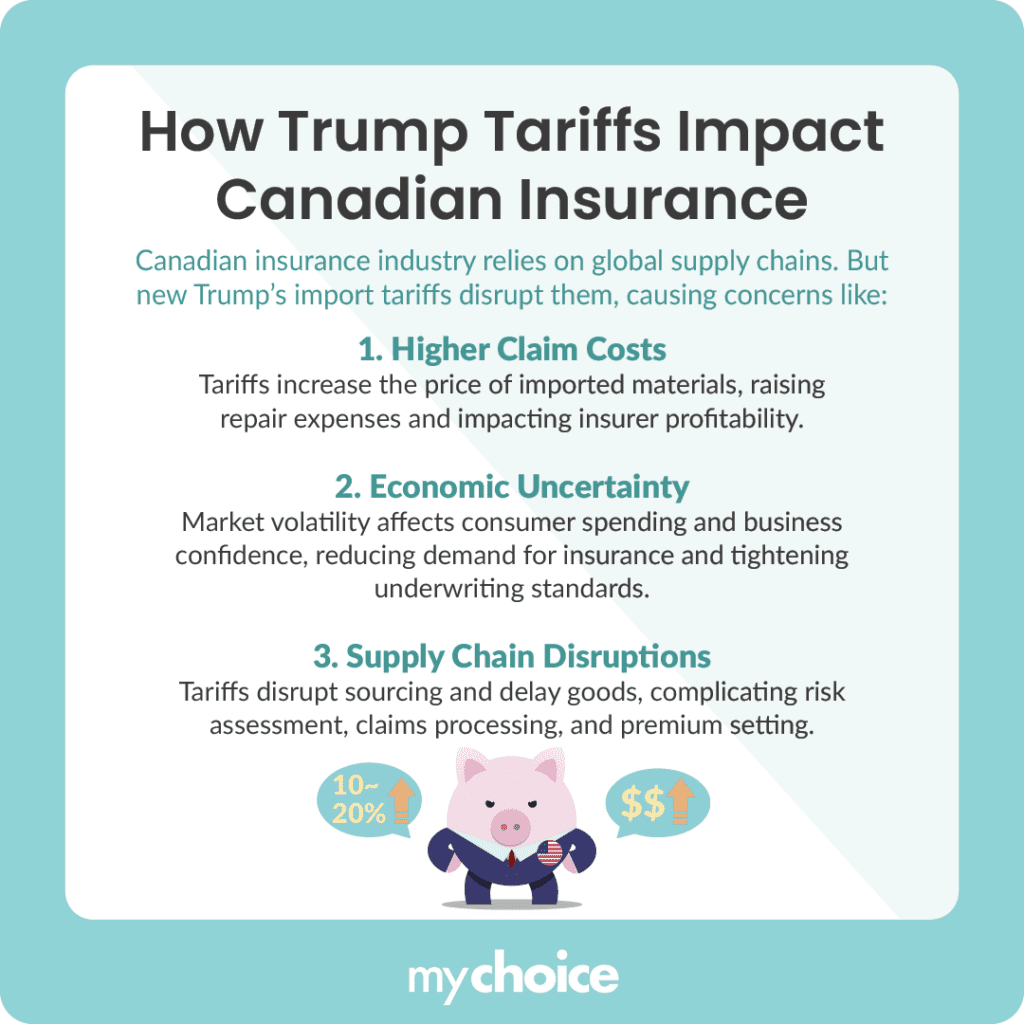
Depending on insurance terms, the insurer may have to repair, replace, or make payments described in the insurance. Higher costs for any of these may increase claim severity, particularly when a repair requires tariffed material with no adequate alternatives to offset the increase.
Increased Claim Costs
In its submission to FSRA, the IBC noted that some insurers are already seeing increases in repair and replacement costs as a result of tariffs. While it did not provide an aggregate quantification, the submission highlights the industry’s concern about repair costs. Still, it does not necessarily mean premiums will increase for every policyholder, as circumstances will differ among insurers.
Economic Uncertainty
At the macroeconomic level, the Bank of Canada commented in July 2026 that although most North American trade continues without tariffs, some industries are feeling impacts, and trade relations represent one of the key risks to inflation. However, this report preceded the introduction of the August 25 measures and is not necessarily representative of the impacts that may be felt.
Supply Chain Disruptions
For an auto, if parts or other materials are unavailable, sourcing changes could lengthen repair time, which can increase rental or loss-of-use costs where applicable.
In some cases, alternative materials, contractor availability, and local building codes may be a bigger issue for a property claim than tariffs.
Higher prices for steel and aluminum do not necessarily portend higher premiums everywhere. Still, it’s plausible that higher material costs lead to higher vehicle and building costs, which in turn lead to higher repair/replacement costs.
How Tariffs Could Impact Premiums and Claims
- A tariff or countertariff is put in place for a good from a particular country of origin.
- Suppliers then factor in foreign exchange, tariffs and countertariffs, current inventory, alternate products, etc., before adjusting prices, product availability, and/or fulfilment timelines.
- Claims that require those products cost more to settle and/or take longer.
- An insurer may increase premiums if actual or anticipated losses warrant a rate increase. Each province has its own process to approve increases.
- Premium increases apply to insurance policies when permitted, usually at renewal.
Read More: Read How Global Financial Volatility Can Affect Insurance
What to check on an auto renewal
FSRA reminds us that approved insurer-level rate changes don't affect all drivers the same way. Shop around and compare rates. Make sure you’re comparing the same liability limits, deductibles, drivers on the policy, comprehensive, collision, and any endorsements.
While they can’t necessarily put a cost on tariffs, your insurer or broker should be able to discuss the many changing factors that can affect your auto insurance rate.
Check whether it still makes sense to include replacement-cost or depreciation-waiver options for your vehicle. Review the maximum amount available under your policy if you have loss-of-use coverage and parts delays are an issue.
Read More: Use the Ontario Car Insurance Renewal Guide
What to check on a property or business policy
Update the values of buildings, equipment and stock according to current estimates of replacement cost.
Read the wording of your policies regarding replacement cost or actual cash value, coinsurance, inflation protection, debris removal, professional fees, service interruption, equipment breakdown, by-laws, and imported machinery, considering, where relevant, the place of origin, lead-time, possibility of substitute parts, and how long production could continue without the item.
Don’t reduce limits or increase deductibles to save on premiums unless you can pay the resulting increase in uninsured losses.
Read More: Learn How Rebuilding Risk Relates to Home Insurance Cost