









What to Do If You Cannot Afford Car Insurance
In Canada, it’s illegal to drive a car without insurance. So what happens if you can’t afford your monthly insurance payments? One option is to cancel your insurance and let your car sit in the garage. We don’t recommend doing that without considering some alternatives first.
There’s nothing worse than looking at your bank account and thinking, “I can’t afford car insurance this month.” Missing payments can result in cancellation. It may also affect the cost and availability of insurance later on.
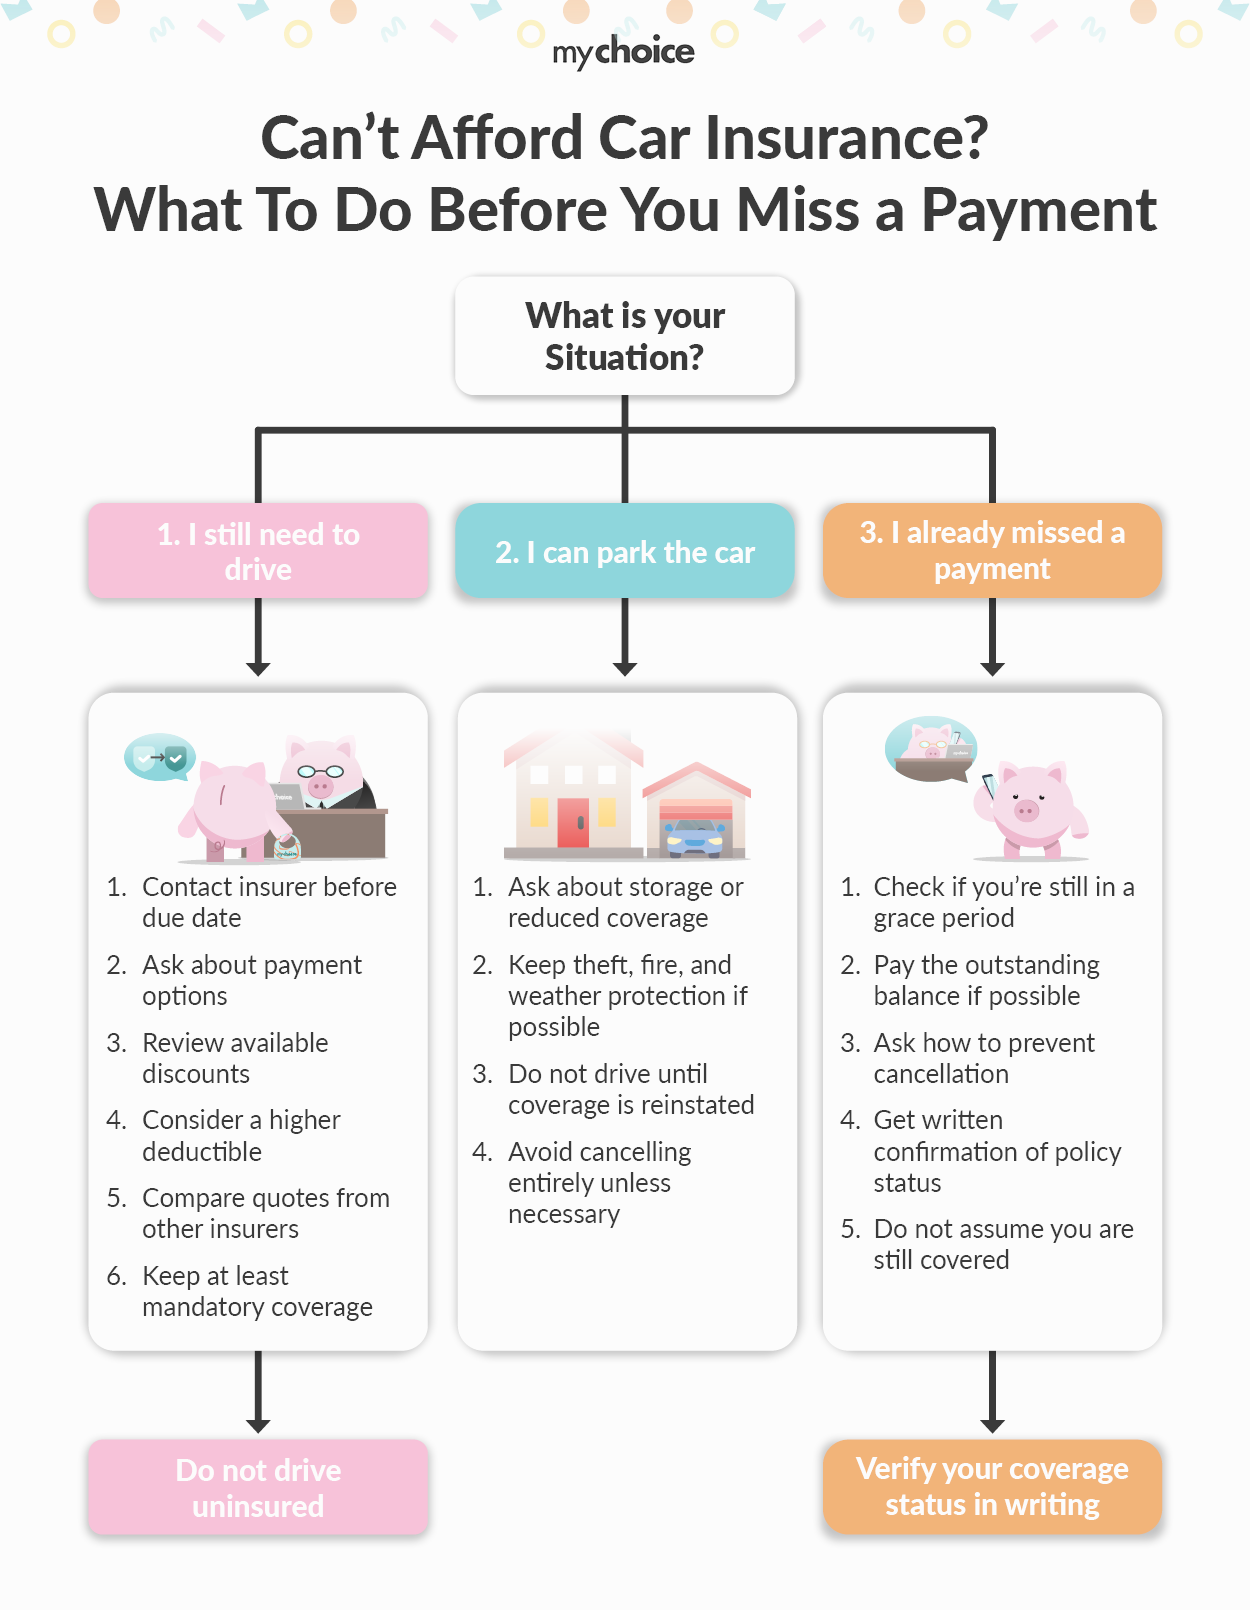
If a Payment Is Due Soon
When a payment is due, focus on that payment first. You can look at longer-term ways to save money afterward.
Your insurer or broker may be able to make some adjustments to help with the amount you’re being billed. Contact the insurance company as soon as possible, preferably before the premium is due. Ask about changing your billing date, available payment options and any other ways it can help.
If you have received a non-payment notice, follow the amount, payment method and deadline shown in the notice.
Why Missing a Payment Can Cost More
A single late or missed payment doesn’t necessarily mean that your policy will be cancelled. However, failing to make payments can eventually result in cancellation. A lapse in coverage may limit your choice of insurers and lead to higher premiums down the road.
Here’s an example from our Ontario quote database:
A driver with no claims or other issues on their driving record could pay an average quoted premium of $2,345 per year. If the policy is cancelled for non-payment, that driver could pay $2,836 per year. That’s an increase of $491, or 21%.
The $491 increase is not a set penalty. The actual increase can vary based on your driving record, vehicle, location, time since the cancellation and coverage purchased.
Some Options When You Can’t Afford Auto Insurance
If the problem is going to last for longer than a month, contact your insurance company. It may be able to reduce your costs by changing your coverage, raising your deductible or finding discounts that apply to you.
Reducing coverage or raising your deductible also means taking on more financial risk. Ask what each change would save before agreeing to it.
You should also look at the discounts your insurer offers. Many insurance companies provide discounts for things such as low mileage, eligible safety features, winter tires, multiple vehicles or bundled home and auto insurance. Eligibility and savings vary by insurer.
Compare Prices and Coverage
If you’re unhappy with the cost of your insurance, ask your broker to look at other options. You can also get quotes from other companies.
Make sure you’re comparing apples to apples. Compare policies with the same liability coverage, accident benefits, deductibles and endorsements before deciding which one costs less.
A cheaper policy may provide less coverage or come with a higher deductible.
If the Vehicle Will Be Stored and Not Driven
Ask your insurer whether the premium can be lowered if your car will not be driven for an extended period.
OPCF 16 can be added to an eligible policy when a vehicle is continuously out of use. It suspends the road coverages listed in the endorsement.
You won’t receive a refund if the coverage is suspended for fewer than 45 consecutive days. If you might use the car, even for a short trip, speak with your broker before suspending coverage. You cannot drive while the road coverages are suspended. OPCF 17 must be used to reinstate them before you drive again.
Before You Cancel or Switch Policies
If you find a lower-priced policy elsewhere, make sure the new coverage is confirmed before cancelling your existing policy or allowing it to expire. Get the effective date of the new policy in writing before driving.
A preliminary quote or payment receipt does not, by itself, confirm that coverage is in force.
Insurers must follow the applicable notice process before cancelling a policy for non-payment. The standard Ontario Automobile Policy, OAP 1, outlines the notice requirements and timelines for most private passenger vehicles. Different rules may apply after repeated non-payment during the same policy term.
You cannot drive if your policy has been cancelled or expired, or while its road coverages are suspended.