









Myth: Ontario has a “no-fault” system, so it doesn’t matter who caused the collision.
Fact: Although Ontario has a no-fault insurance system, which means you deal with your own insurance provider for covered claims, fault is still determined after a collision and may affect your insurance rates or standing.
For this guide, we reviewed FSRA’s standard-policy overview, the Ontario Automobile Policy and Ontario’s Fault Determination Rules.
What Does No-Fault Insurance Mean in Ontario?
DCPD, Collision and Uninsured Automobile claims each have different rules and deductibles. You usually handle claims for eligible accident benefits through your own insurer, no matter who was at fault. That is what makes it “no-fault insurance.”
This doesn’t mean that nobody gets assigned fault for the accident. Insurers can decide who was at fault for rating and vehicle-damage coverage purposes.
For vehicle damage, Direct Compensation-Property Damage coverage applies in Ontario if specific criteria are met. Only the portion of vehicle damage that is not your fault would be covered. Other forms of coverage may also apply, such as optional collision coverage or uninsured-automobile coverage.
For physical injuries, statutory accident benefits may apply through the applicable insurer regardless of who was at fault, subject to eligibility, limits and policy terms.
Percentage of fault can affect the level of DCPD coverage and the treatment of your claim. Ask your adjuster to explain the Ontario Fault Determination Rules applied to the assessment, including the applicable diagram, the evidence they relied upon and the policy section and deductible applied to each part of your claim.
Fault affects deductibles, your ability to sue and your future rates differently.
Read More: How Is Fault Assigned After a Car Accident?
What Does Ontario No-Fault Insurance Cover?
Injury benefits and vehicle-damage coverage operate differently. No-fault insurance describes how claims are handled; it is not a separate type of coverage. Certain limits and conditions determine whose insurance responds to your claim.
Medical Expenses
FSRA’s standard-policy overview outlines the current Statutory Accident Benefits regime. Subject to eligibility, limits and policy terms, your insurer may pay benefits for eligible medical, rehabilitation and attendant-care expenses regardless of who was at fault for the accident.
Direct Compensation-Property Damage
DCPD coverage may pay for the portion of vehicle damage, contents and loss of use to which you are entitled as the not-at-fault party if certain requirements in Ontario are met, unless you have chosen to opt out of DCPD coverage by selecting OPCF 49.
Uninsured Automobile Coverage
Uninsured Automobile coverage may apply if you meet certain definitions and follow the claim requirements. Property-damage claims work differently when the other uninsured driver is known than when a hit-and-run driver is unidentified.
What Happens After a Crash?
What to Do After a Collision
Follow these steps after an accident:
- Exchange information with the other drivers.
- Call for medical assistance if necessary.
- Report the accident to your insurer within the period stated in your policy.
- Follow police instructions and collision-reporting-centre requirements.
- Photograph the accident scene.
- Collect names and contact information from witnesses.
- Make the accident scene safe when possible.
Never wait for fault to be determined before reporting injuries or documenting vehicle damage. Ask the claims adjuster what happens next. If coverage is denied, ask for a letter explaining the reason.
Why Was No-Fault Insurance Introduced in Ontario?
Ontario introduced no-fault insurance in 1990 to reduce the growing liability costs associated with motor vehicle accidents. Before no-fault insurance was introduced, a driver involved in an accident had to make several insurance claims and often waited months to receive payment.
Common Misunderstandings About No-Fault Insurance
Common misunderstandings arise because “no-fault” describes the claims process, not an absence of fault findings.
- Contrary to common belief, fault will still be assigned to a party.
- Myth: There is no investigation under no-fault insurance. Correction: The insurer still collects evidence and investigates to determine which rules, coverages and deductibles apply.
- Whether an accident affects your rates depends on fault, the specifics of your coverage and your insurer’s approved rules. Even if you’re found not at fault, the accident may still appear in your claims history.
Under Ontario’s No-Fault Insurance, Who Pays the Deductible?
Ask the adjuster which coverage—such as DCPD, Collision or Uninsured Automobile—each part of the claim falls under and how they arrived at the deductible.
Deductibles vary depending on which part of your policy pays the claim and the percentage of fault. Ask the adjuster to go over their calculations.
Will a No-Fault Claim Affect Insurance Rates?
Depending on the claim, the percentage of fault attributed to you, your driving record, the coverages you have, whether the insurer has an applicable accident-forgiveness endorsement and other factors, an at-fault claim can affect your renewal premium. This can vary based on the rules approved for your insurer.
Policies From July 1, 2026
Medical, rehabilitation and attendant-care benefits will still be required. Income replacement and similar benefits will be optional under the FSRA summary of the standard policy for new insurance policies effective July 1, 2026 or later.
Always check your policy and the current OAP 1 to determine which benefits apply.
Read More: 2026 Ontario Accident Benefits Reform Explained
Is No-Fault Insurance Available in Other Provinces?
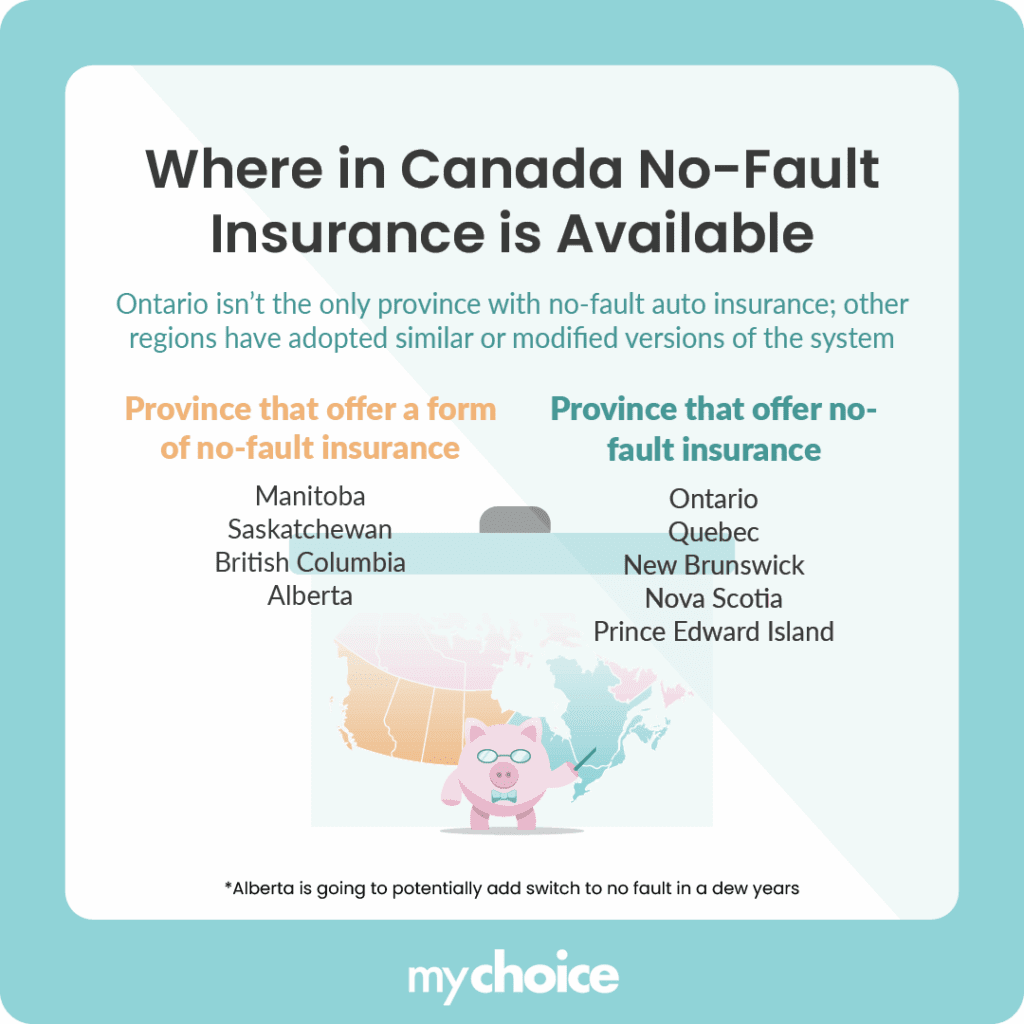
Always check with the regulator and review the insurance policy in the province where the vehicle is insured. Each jurisdiction has a different system for first-party benefits, property damage and the right to bring a legal action.
Read More: Public Car Insurance vs. Private Car Insurance in Canada