









Who Is Considered a High-Risk Driver?
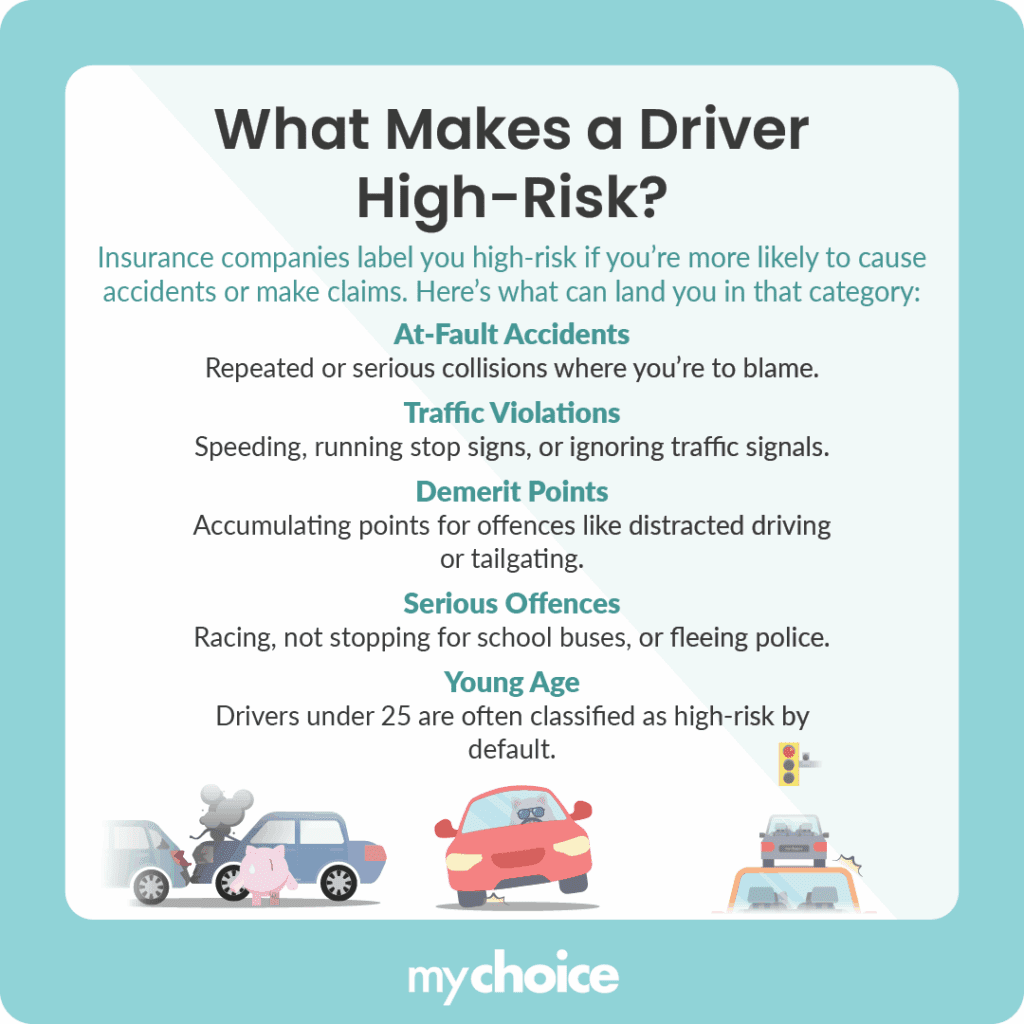
You may become a high-risk driver if insurers consider you more likely to file a claim. This classification is based on your driving history or experience level. High-risk drivers typically pay higher premiums.
You may be considered a high-risk driver if you have:
- At-fault accidents on your record;
- Tickets, suspensions or major convictions;
- An insurance cancellation due to non-payment;
- Filed multiple at-fault claims in a short period.
As your driving record improves and you maintain continuous insurance without incidents, you can gradually move out of the high-risk category and see your rates come down over time.
How Much Is High-Risk Insurance in Ontario?
Accidents, tickets, licence suspensions and insurance cancellations can increase your rates.
The table below shows average annual car insurance premiums in Ontario for several common driving records.
| Driving record or violation | Average annual car insurance premium |
|---|---|
| Clean driving record | $1,894 |
| Insurance cancellation due to non-payment | $2,633 |
| Licence suspension for an alcohol-related offence | $1,989 |
| One at-fault accident | $3,712 |
| Speeding ticket | $2,292 |
Source: MyChoice Quote Database, January 2026.
What Is the Best Car Insurance Company for High-Risk Drivers?
There is no single best company for high-risk drivers in Ontario. However, according to our latest study on the best auto insurance companies in Ontario, Coachman offers auto insurance for drivers who fall outside standard underwriting guidelines, such as those with previous accidents or driving violations.
How to Save Money as a High-Risk Driver
It’s important to remember that every insurer prices risk differently. That’s why comparing rates from multiple providers is key.
You can use our auto insurance comparison platform to see what rates you can get from different providers.
Showing insurers that you are becoming a safer, more predictable driver works over time. If you maintain a clean driving record, your rates may eventually go down.
Avoiding cancellations for non-payment and choosing a car with lower insurance premiums can also make a difference.