









If you’re looking to compare car insurance quotes in Ontario, it’s important to understand the difference between insurance brokers and insurance agents. Both provide valuable services to consumers.
Our comparison below is based on sources that define how agents and brokers are regulated and what each owes you. On the broker side, we drew on the Registered Insurance Brokers Act, 1981 and RIBO’s Code of Conduct. On the agent side, we reviewed FSRA’s licensing framework for how agents are authorized and supervised in Ontario.
We also reviewed the CCIR/CISRO Fair Treatment of Customers guidance.
What Is The Difference Between An Insurance Broker And An Agent?
An insurance broker is licensed to sell insurance. Brokers may obtain quotes from the insurers their brokerage can access.
Insurance agents represent the insurance company that sponsors them. They may be employees or independent contractors.
In Ontario, brokers must abide by the Registered Insurance Brokers Act, 1981 and the RIBO Code of Conduct. FSRA must authorize agents to sell insurance in Ontario. In other provinces, agents must be authorized by the applicable regulator, such as the Alberta Insurance Council, the Insurance Council of British Columbia or the Autorité des marchés financiers in Quebec.
Both must meet the expectations for fair treatment of customers outlined by CCIR and CISRO.
Types Of Insurance Agents
In Ontario, a general insurance agent is sponsored by an insurer and generally sells that insurer’s products. An agent may be an employee or an independent contractor.
Brokers can offer insurance from several insurers available through their brokerage. Brokers act in the interests of their clients, while agents represent the insurance companies they work for.
Pros And Cons Of Working With Insurance Agents
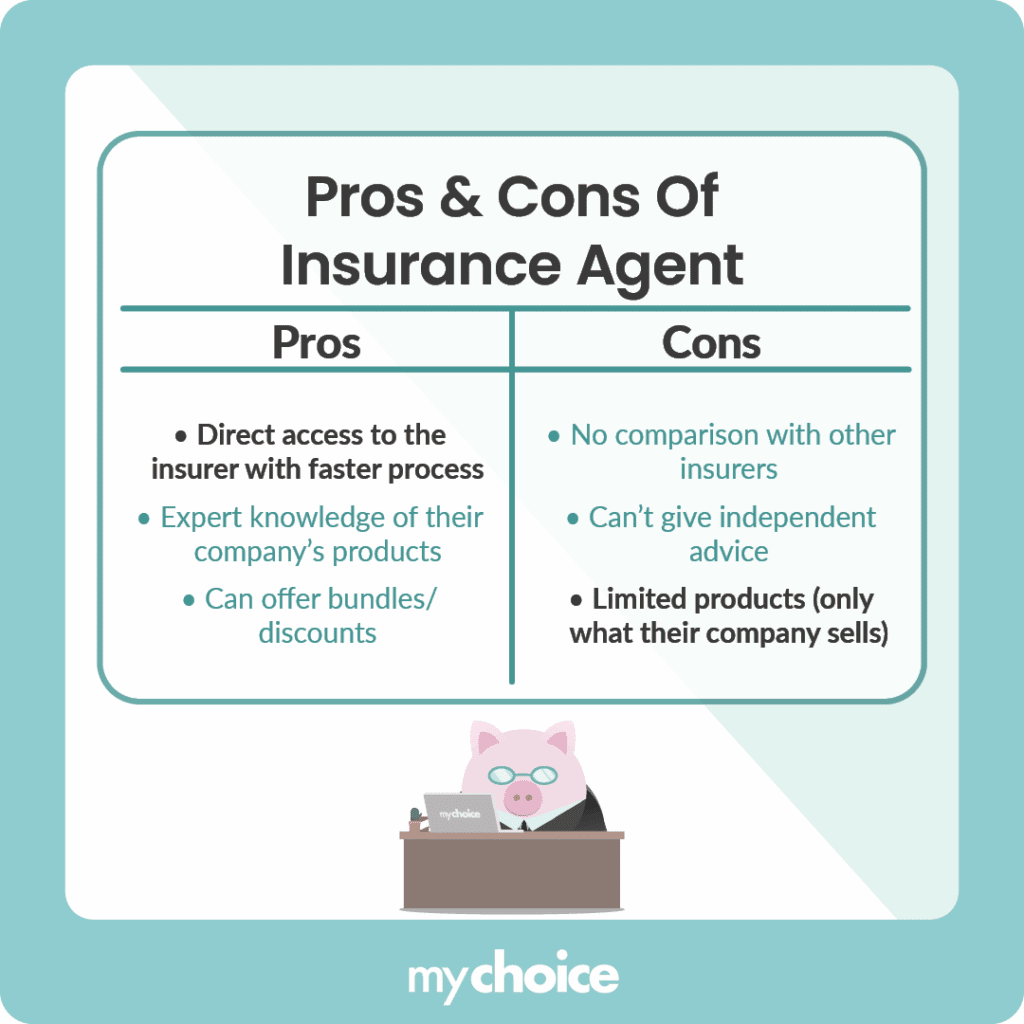
Advantages Of Working With Insurance Agents
- They are knowledgeable about the products offered by the company they work with and may be able to offer information about insurance you didn’t know existed.
- Insurance agents are often familiar with the details of their insurer’s policies. Their knowledge may help if you are already familiar with or loyal to a particular insurance company.
- An insurance agent may be able to offer discounts for having more than one type of insurance with the company, such as home and car insurance.
- Their authority to bind coverage depends on the insurer and product.
- Insurance agents can only sell products offered by the insurance company they represent. This limits the products they can offer.
- An insurance agent can advise you about products offered by that company but does not shop the policies offered by competing insurers.
Disadvantages Of Working With Insurance Agents
- Since they represent only one insurer, you won’t be able to compare different options through agents
- The advice you receive from insurance agents might not be free from bias
- The products offered by insurance agents are limited by what the company they work for sells
Types Of Insurance Brokers
Insurance brokers identify the insurance needs of clients and assist in finding policies that meet those needs. There are two main types of brokers:
- Retail brokers deal with you directly. They can be a resource when looking for common types of insurance, including home and auto policies. They obtain policies from insurers and wholesale brokers.
- Wholesale brokers offer policies to agents and brokers. Their products can be unique or specialized. Wholesale brokers are less likely to deal directly with individual clients.
- Brokers are obligated to act in the interests of their clients. They are accountable for providing advice that meets their regulatory duties.
- Brokers can request quotes from several insurance companies available through their brokerage. They can share this information with you to help you make a decision.
- Insurers often compensate brokers, although fees may also apply. Ask the broker how they are compensated.
- Brokers must work with insurers to arrange coverage. An agent working directly for an insurance company may have a different process for issuing policies or making changes.
- Agents may have more product-specific knowledge about their insurer’s policies. Brokers can still explain the policies they offer, but they work with products from several insurers.
- Some brokers receive contingent commissions from insurance companies when certain criteria are met. Brokers must disclose applicable forms of compensation and conflicts of interest before you agree to purchase the policy.
Who’s Right For You?
If you’ve been happy with an insurer for some time, an insurance agent might be a good option. The agent may also be able to offer discounts available through that company.
However, it still pays to shop around. Rates can vary greatly between insurance companies, particularly for young, inexperienced or high-risk drivers.
How Agents And Brokers Are Licensed In Canada
In Ontario, the Financial Services Regulatory Authority of Ontario licenses insurance agents. The Registered Insurance Brokers of Ontario, a self-regulatory body created by the Registered Insurance Brokers Act, 1981, licenses brokers.
Outside Ontario, provincial insurance councils may license agents and brokers. These include the Alberta Insurance Council and the Insurance Council of British Columbia. In Quebec, the Autorité des marchés financiers oversees insurance.
- Ontario brokers: Search RIBO’s public licence directory to confirm that the individual and brokerage hold active licences.
- Ontario agents: Use FSRA’s online licence search to check the licensing status of an insurance agent.
What To Ask When Shopping For Insurance
Before speaking with an insurance agent or broker, review the following questions. Use them to start the conversation and help you decide whether the person is the right fit.
Questions To Ask Insurance Agents
- Will you be my point of contact if I have questions or need to make changes to my policy?
- How easy is it to increase or decrease my coverage?
- Does the insurance company employ you, or are you an independent contractor?
- Are there discounts for purchasing more than one type of insurance from your company?
- How long have you worked in insurance?
- How do you determine which insurers to obtain quotes from?
- Which insurers do you work with?
- How many quotes will you obtain for me?
- How are you compensated, and do contingent commissions apply?