









Keeping your car insured will save you from a certain amount of financial loss if your vehicle is damaged, totalled or stolen. However, your car’s value can depreciate, which can make an insurance payout lower than you expected.
OPCF 19 and OPCF 19A change how the amount payable for covered loss or damage is determined. What are the differences between OPCF 19 and 19A? Which one is better for your vehicle? Read on to learn what you need to know.
OPCF 19 and OPCF 19A at a Glance
OPCF 19 and OPCF 19A are endorsements you can add to your Ontario auto insurance policy.
- OPCF 19 limits the amount the insurer will pay.
- OPCF 19A sets an agreed value for the vehicle.
- Both endorsements remain subject to the coverage, deductibles and other terms of the policy.
OPCF 19 Explained
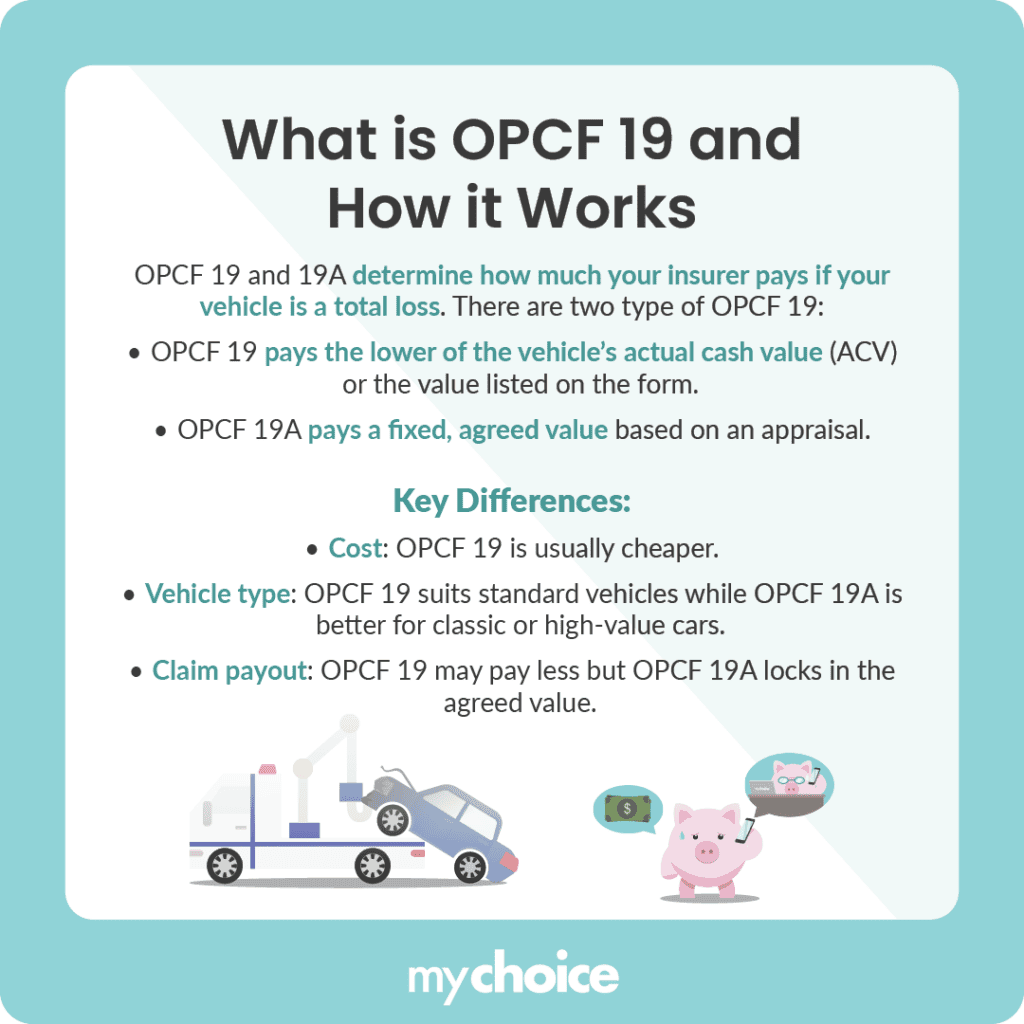
Ontario Policy Change Form 19 is an endorsement known as “Limiting the Amount Paid for Loss or Damage Coverages.”
When you make a claim for covered loss or damage, the insurance company will pay no more than the lower of two amounts: the vehicle’s actual cash value at the time of the loss or the amount listed on the OPCF 19 form.
The deductible shown on your Certificate of Automobile Insurance still applies.
OPCF 19A Explained
OPCF 19A is known as the “Agreed Value of Automobiles” endorsement. It sets an agreed value for the vehicle, and the insurance company gives up its right to settle based on actual cash value in the circumstances described by the form.
The insurer will provide coverage up to the value listed on the endorsement. That value also limits how much the insurer will pay to repair the vehicle, and the policy’s deductibles still apply.
An insurer may require an appraisal or other documents before agreeing to the value.
What’s the Difference Between OPCF 19 and OPCF 19A?
While OPCF 19 and OPCF 19A are similar in name, there is an important difference between them.
OPCF 19 limits payment to the lower of the vehicle’s actual cash value or the amount listed on the form.
OPCF 19A uses the agreed value listed on the form instead of the vehicle’s actual cash value. The insurer will pay up to that amount for covered loss or damage.
Don’t assume that one endorsement will always cost less than the other. Ask for written quotes and compare the premium, deductible, settlement terms and appraisal requirements.
OPCF 19 or OPCF 19A for Collector Vehicles?
Each insurance company has its own rules for collector vehicles. The insurer may consider the vehicle’s age, condition, use, storage and appraisal. A car does not automatically qualify for collector insurance when it reaches a particular age.
OPCF 19 can result in a payment below the amount listed on the endorsement because the insurer pays the lower of that amount or the vehicle’s actual cash value.
OPCF 19A may be more suitable for a classic or collector vehicle because it uses an agreed value. However, it is still important to check the amount shown on the endorsement and keep it up to date.
Ask your insurer whether a new appraisal is required when the policy renews or after the vehicle’s value changes.
Should I Choose OPCF 19, OPCF 19A or OPCF 43?
Much like OPCF 19 and OPCF 19A, OPCF 43 changes how the insurer settles certain claims. However, OPCF 43 does not provide agreed-value coverage.
OPCF 43 removes the insurer’s right to deduct depreciation from an eligible vehicle. Under the current form, you must be the original purchaser, and the vehicle must have been new when it was delivered to you. The endorsement only applies for the period shown on the form.
OPCF 19 limits the amount payable, OPCF 19A uses an agreed value, and OPCF 43 removes a depreciation deduction from an eligible vehicle. Compare the wording before choosing an endorsement.
Bottom Line
- Check the amount listed on the endorsement before the policy is issued or renewed.
- Ask whether the insurer requires an appraisal and how often it must be updated.
- Compare the premium, deductible and settlement terms.
- Don’t assume OPCF 19A will always pay the vehicle’s full market value or that OPCF 19 will always cost less.
- Keep copies of the endorsement, appraisal and Certificate of Automobile Insurance.
Read More: Gap Insurance: What Is It and Do I Need It?