









Having a car stolen or totalled in an accident is a stressful event that comes with a lot of financial implications. If the loss is covered, your auto insurance policy may provide a settlement. However, your car may have depreciated between the time you purchased it and the date of the claim, reducing the amount you receive.
OPCF 43, also called Removing Depreciation Deduction, is an endorsement that prevents the insurer from deducting depreciation when settling an eligible claim. How does OPCF 43 work? How much does it cost? Read on to find out what you need to know about this insurance add-on.
OPCF 43 at a Glance
- OPCF 43 is an endorsement you can add to an Ontario auto insurance policy.
- It removes the insurer’s right to deduct depreciation when settling an eligible claim for loss or damage.
- You must be the original purchaser, and the vehicle must have been new when it was delivered.
- The coverage lasts for the period shown on your policy.
How OPCF 43 Works
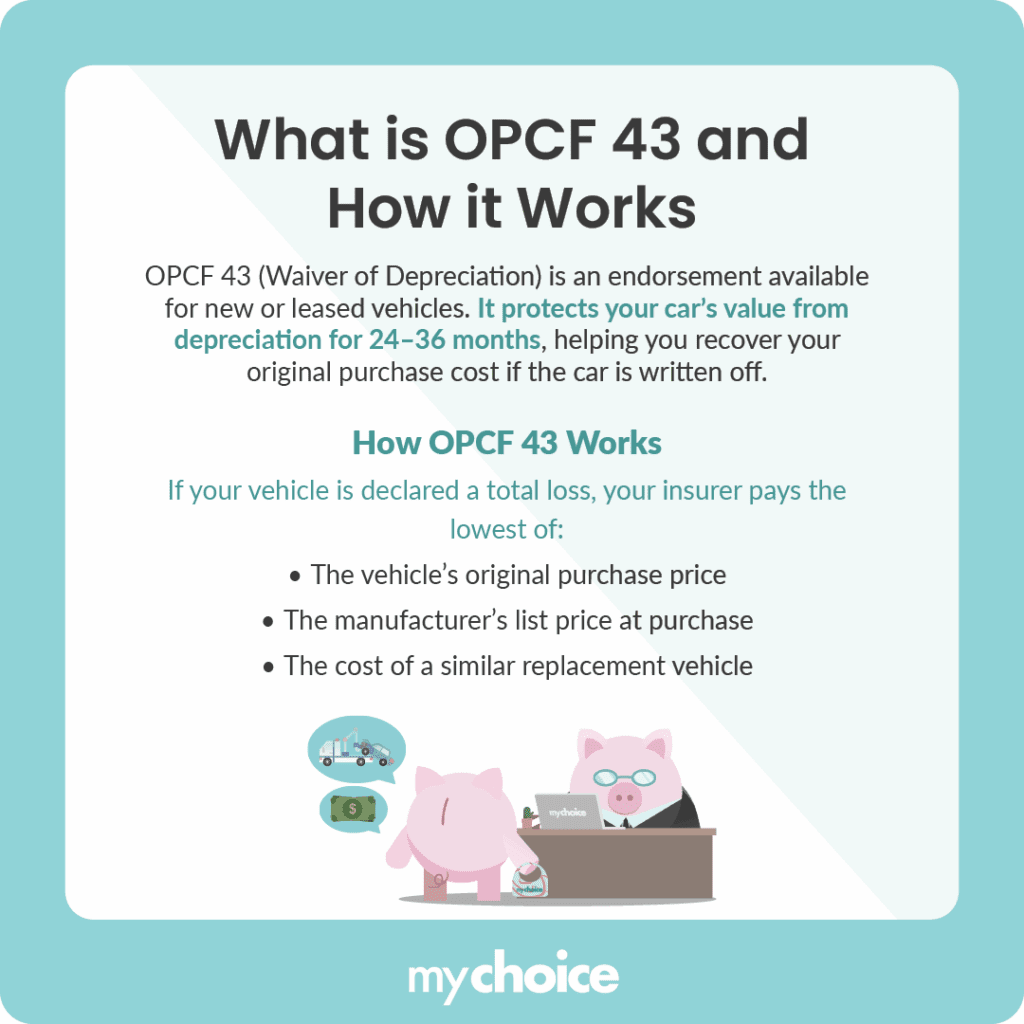
You may be able to add OPCF 43 when buying a brand-new vehicle. OPCF 43A may apply when leasing a new vehicle.
Depending on your policy and insurance company, you may be able to protect the vehicle against depreciation for several years. Check the number of months shown on your policy because the available coverage period varies.
Since most vehicles depreciate, losing a car within the first few years can mean that the regular settlement is lower than its original purchase price. OPCF 43 removes the insurer’s right to deduct that depreciation, subject to the limits and conditions in the endorsement.
How Does Car Depreciation Work?
When you buy a new car, you’re buying it at its current value. Once you start driving it, the vehicle will usually begin losing value.
The amount of depreciation depends on the make and model, mileage, condition and local market. That makes it difficult to use a fixed annual percentage to predict the value of a future claim.
OPCF 43 uses the settlement formula stated in the endorsement rather than guaranteeing a particular percentage or payment.
Why Do I Need OPCF 43?
OPCF 43 can protect you from some of the financial loss caused by depreciation after a covered claim.
This may be useful if your vehicle is stolen or declared a total loss shortly after you buy it. Without the endorsement, the settlement may reflect the vehicle’s depreciated value.
OPCF 43 does not guarantee that you’ll receive everything you originally spent. The payment is still subject to the deductible, coverage and settlement limits in your policy.
How Much Does OPCF 43 Cost and Is It Worth It?
There is no standard price for OPCF 43. The cost depends on the insurer, vehicle and available coverage period.
Whether the endorsement is worth adding depends on:
- the additional premium
- the vehicle’s purchase price and expected depreciation
- the deductible
- how long the endorsement remains in effect
- your financing or lease agreement
- whether you could afford the difference after a depreciated settlement
Ask your insurer for the additional cost and coverage period in writing before adding the endorsement.
Read More: OPCF 20: Loss of Use Coverage
Mechanics of OPCF 43
When your car is damaged or declared a total loss, your claim will be reviewed by the insurance company. If OPCF 43 applies, the insurer removes its right to deduct depreciation.
The most the insurer will pay is the lowest of:
- the actual purchase price of the vehicle and its equipment
- the manufacturer’s suggested list price of the vehicle and its equipment on the original purchase date
- the cost of replacing the vehicle with a new one of the same make and model with similar equipment
These amounts include applicable taxes. The deductible shown on your Certificate of Automobile Insurance still applies.
The payment may be lower than the vehicle’s current market value if the vehicle has appreciated rather than depreciated. This is uncommon, but it may happen with a rare or limited-production model.
Read More: What Is Gap Insurance and Do I Need It?
Limitations of OPCF 43
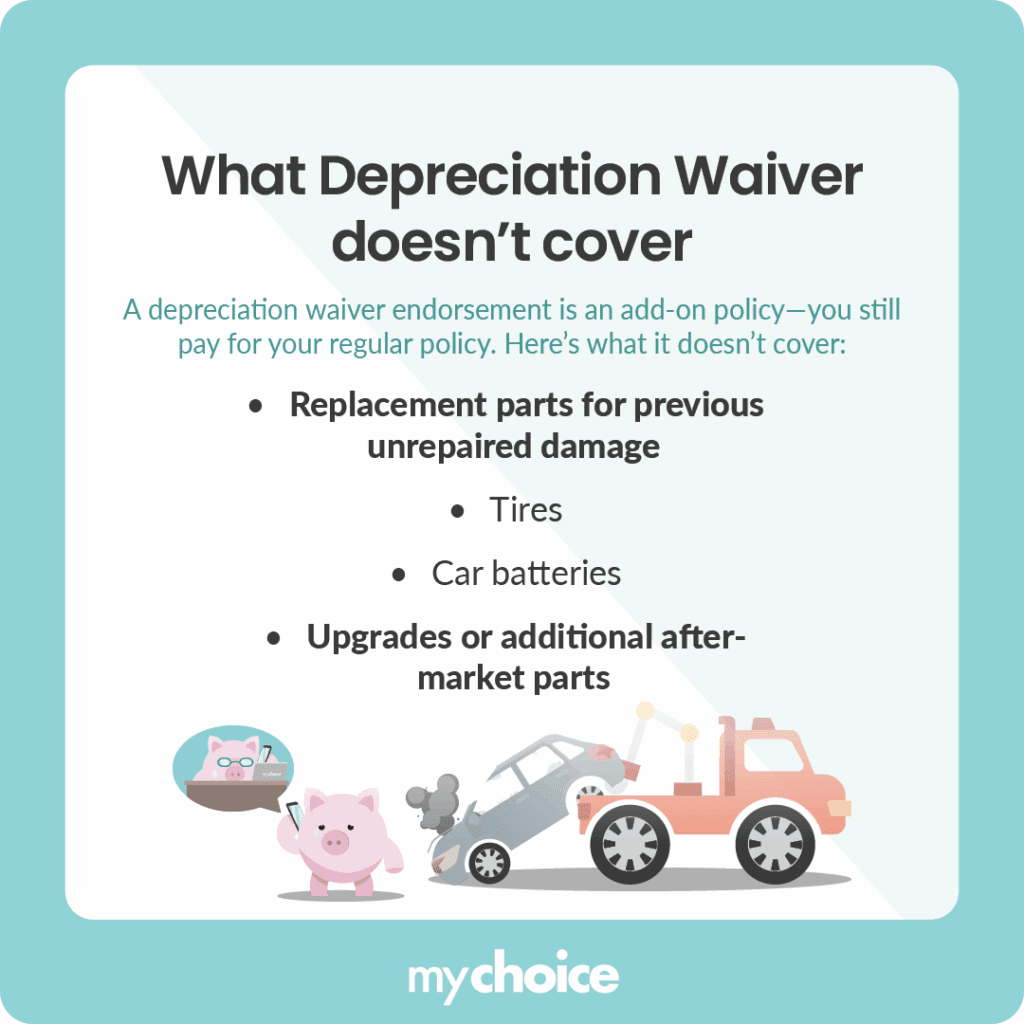
While OPCF 43 removes depreciation from an eligible settlement, there are several limitations to consider.
The endorsement applies only to the original purchaser of a vehicle that was new when delivered. It generally won’t apply if you buy a used vehicle.
OPCF 43 also applies only during the period shown on your policy. Check the expiry date rather than assuming the endorsement will remain in effect for as long as you own the vehicle.
The endorsement excludes:
- tires
- batteries
- betterment resulting from repairing or replacing parts affected by earlier damage that wasn’t repaired
A previous repair does not automatically end OPCF 43 coverage. How a previous loss affects your eligibility depends on the policy and insurer.