









Effective July 1, 2026, Ontario made some auto insurance benefits optional that previously were mandatory. One of these is the income replacement benefit, which lets you continue to receive a portion of your income if a car crash leaves you unable to work.
Now that you have a choice, should you keep the income replacement benefit, cancel it, or even increase the amount you would receive? There’s no universal answer. Some people may assess their financial situation and decide income replacement is critical. Others may be able to give this up if they have sufficient savings or alternate coverage.
In this article, we’ll lay out the factors to consider when deciding whether the income replacement benefit remains an important part of your Ontario auto insurance policy.
Read More: 2026 Ontario Accident Benefits Reform Explained
Why the Income Replacement Benefit is Now Optional in Ontario
Due to changes in Ontario’s auto insurance regulations, drivers can now opt out of the income replacement benefit and several other types of coverage. This gives Ontario drivers more choice and flexibility around tailoring insurance premiums.
To make adjustments to your policy, you’ll need to communicate with your insurance provider or broker, who can offer professional guidance. Any policy that began before July 1, 2026, and renews after that date will retain the same coverage and limits unless you agree to make changes in writing.
What to Consider When Deciding Whether to Keep the Income Replacement Benefit
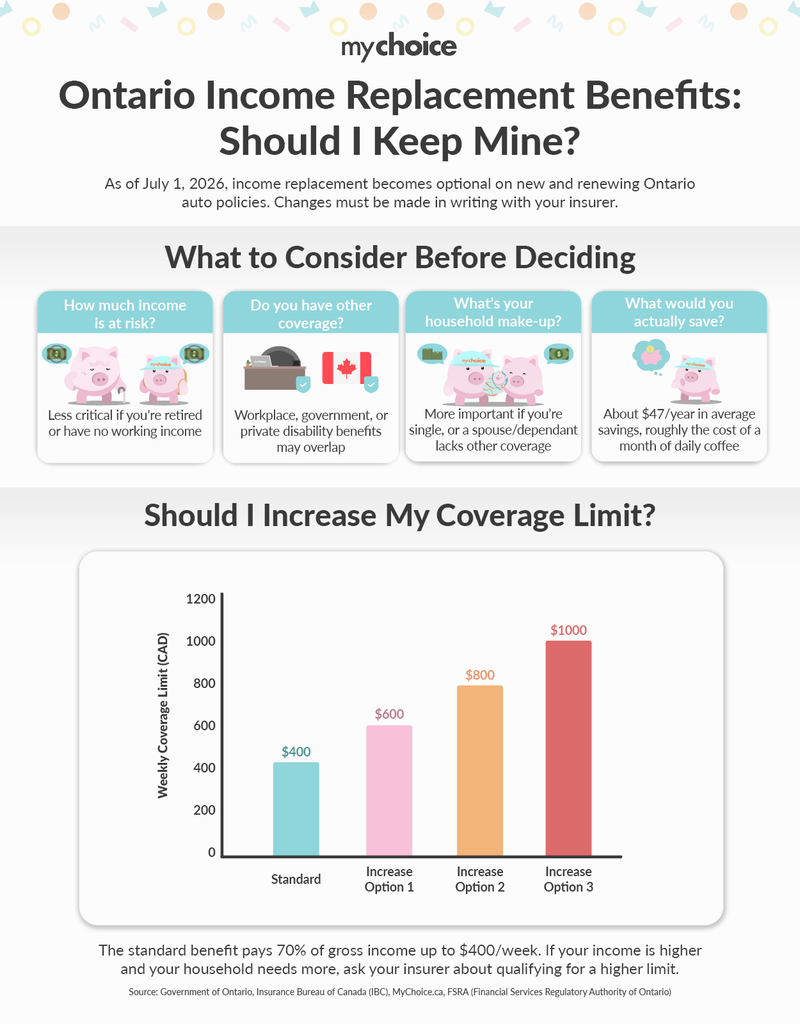
- How much income would you lose if a crash left you unable to work? For example, if your income is essential to cover your household’s expenses, protecting it may be very important. If you have no income to cover such as if you’re retired, this benefit won’t help you.
- What other income protection do you already have? Your workplace, government, or private disability benefits may include coverage that would make the income replacement benefit through your auto insurance redundant.
- What is the make-up of your household? The income replacement benefit may be more important for those who are single or for families where one spouse or a dependant has little to no income protection from other sources.
- How much will removing the income replacement benefit actually save? According to MyChoice.ca’s study of internal insurance quote data since this change came into effect, removing the income replacement benefit would save the average driver only $47 per year or $3.92 monthly. If receiving a portion of your income if you can’t work after an accident is worth a cup of coffee per month to you, consider holding onto that coverage.
Read More: What’s Covered by Accident Beenfits in Ontario
Should I Increase the Limit on My Income Replacement Benefit?
The Financial Services Regulatory Authority of Ontario outlines that the standard income replacement benefit amount is 70% of the beneficiary’s gross income up to $400 per week. If your income is higher than that and your household requires more funds to cover essential expenses, it may be worth getting quotes for higher weekly limits.
Increases are available to $600, $800, or $1,000 per week, provided you qualify and earn enough income. Speak to your insurance provider or broker to learn more.
Who Should Consider Keeping the Income Replacement Benefit?
In short, consider keeping the income replacement benefit on your Ontario auto insurance if losing your income due to injury in a car crash would cause financial hardship for you or your household.
This becomes even more important if you don’t have alternate income protection such as other benefits or a sizeable emergency fund. Every individual’s circumstance is different, so we highly recommend getting expert advice from a licensed insurance professional for before making any changes to your policy.