
Foundation repairs can be expensive. Whether homeowners’ insurance will cover the costs depends not on the location of the crack but on the cause of the problem. Coverage will also depend on the specifics of the homeowner’s insurance policy and optional coverage, such as water and earthquake coverage. For example, insurance may cover resulting damage in a home but not damage to a foundation.
Our team looked through information from the Insurance Bureau of Canada’s guide to home coverage, IBC’s flood and water guidance, the Government of Canada’s foundation-maintenance guidance, and the Financial Consumer Agency of Canada’s claim guide. Read on to learn what kind of damage insurance might cover and what evidence you’ll need to collect before making repairs that could conceal the cause of the damage.
Does Home Insurance Cover Foundation Repair?
You need to establish the cause of the foundation damage and any other property damage separately. The event that caused the problem, the damage to the foundation itself, and the resulting damage to the rest of the property may each be treated differently under your policy.
Insurance may cover foundation damage caused by a covered event, such as fire. Wear and tear, lack of maintenance, settling, faulty construction or engineering, and earth movement are common exclusions.
Water in your basement may be covered if caused by a specific plumbing failure. Coverage for overland water or sewer backup may be available as an endorsement. It all depends on where the water comes from.
How the Cause Changes the Coverage Analysis
| Possible cause | How coverage may be treated | What to verify |
|---|---|---|
| Sudden interior plumbing failure | Resulting water damage may be insured, subject to wording, exclusions and deductible. | Whether the broken pipe or damaged part is covered and whether provisions regarding frozen pipes or vacancy apply |
| Fire, explosion, vehicle impact or vandalism | Foundation damage may form part of the insured physical loss. | The insured event, limits, deductible and repair scope |
| Wind or hail | Damage may be insured if the event directly damaged the structure. | Whether rain entered through an opening created by the event |
| Overland flood or sewer backup | Coverage usually depends on a specific endorsement and its limits. | The water source, deductibles, exclusions, sublimits and endorsements |
| Groundwater or hydrostatic pressure | Gradual seepage is often excluded or limited. | What the water exclusions and endorsements say |
| Earthquake, landslide, settling or soil movement | Settling and earth movement are commonly excluded unless coverage is provided by an endorsement. | Whether an earthquake endorsement applies if an engineer finds earthquake-related damage |
| Faulty design, construction or maintenance | Coverage for damage resulting from the defect varies by policy form. Correcting a defect is usually excluded. | Defect exclusion, resulting-damage wording, warranties and contractor responsibility |
The table should be used as a guideline only and is not indicative of coverage.
Read More: See How Home Insurance Treats Water Leaks
Ask the Adjuster Additional Questions
Ask the adjuster what cause of loss they’re accepting, what repairs are within the scope of the adjuster’s estimate, what exclusions or limitations apply, and if there are resulting-loss provisions in your policy that apply. Ask for a written explanation for any portion of the claim that the insurer is not paying.
What to Do After You Find Foundation Damage
- Make sure people stay away from walls or structures that may be unsafe and from electrical and contaminated-water hazards. If there’s an emergency, call the appropriate utility or emergency number.
- Mitigate the problem if you can do so safely. Turn off the water and move items away from the damaged area.
- Take pictures or videos before demolishing or cleaning up. Include cracks or waterlines, damaged areas and the outside of your house, especially grades, drains and downspouts. Save damaged parts if it’s safe to do so.
- Call your insurer as soon as possible. Do not wait until you get all the quotes. Your insurer will tell you what emergency work they authorize and whether a plumber, engineer or adjuster must see the damage first.
- Be aware of your obligations and deadlines under your insurance policy to notify your insurer and make a claim.
- Keep track of moisture readings, quotes and invoices. Keep a list of the date you found the problem and any repairs. If you’re unsure who is responsible or what caused the problem, get an engineer or plumber to come in. Separate facts from recommendations and repairs.
Read More: Use the Canadian Home Maintenance Checklist
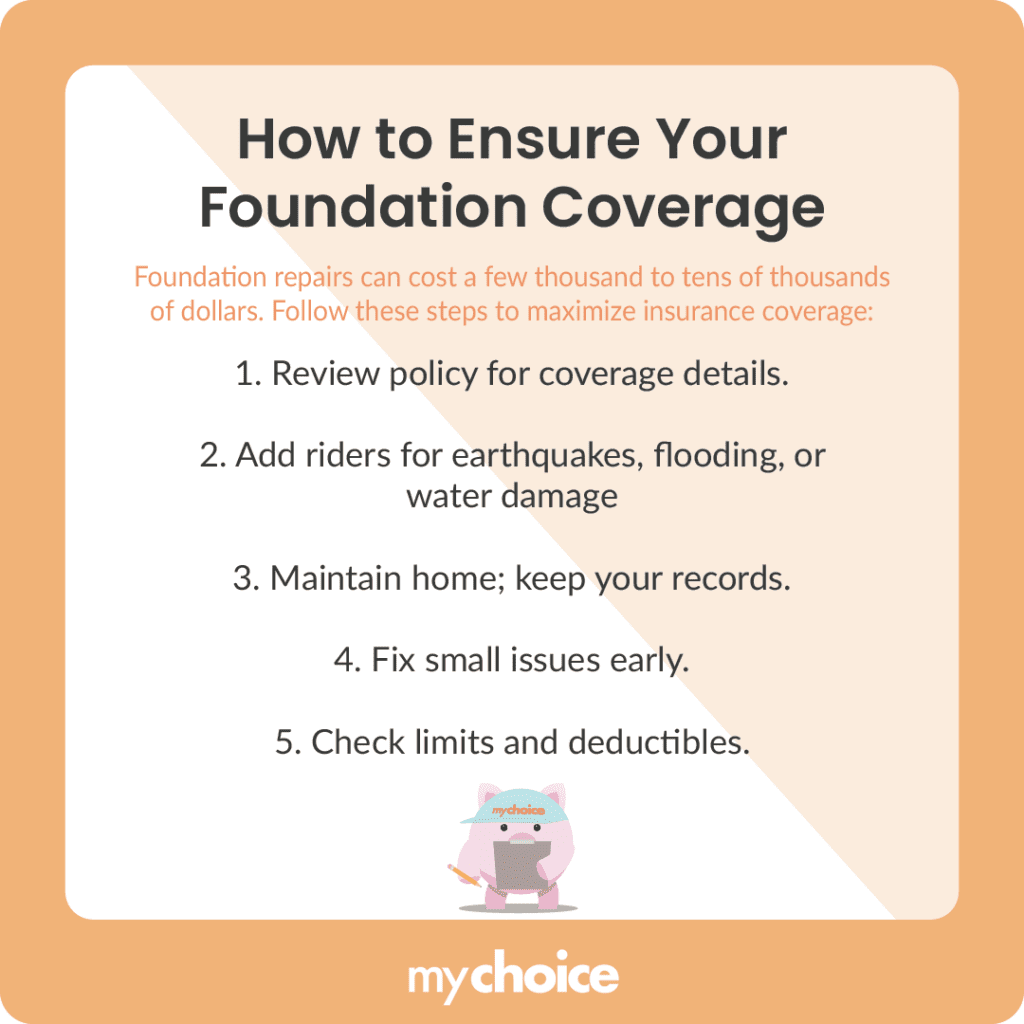
How to Check Your Foundation-Related Coverage
Understand Your Current Policy
Find out if overland water, sewer backup and earthquake coverages are available or optional for your address. Ask if they can be added to your policy.
Basement restoration can be extremely costly. Make sure you know your policy’s limits and deductibles and compare them to the cost of restoring a basement, not just the cost of repairing cracks.
Find out what is excluded. Settling, earth movement, seepage, groundwater, faulty work, rot, mould, tear-out costs, building-code requirements, professional fees and resulting damage are treated differently.
Keep Up With Home Maintenance and Documentation
- Direct downspouts away from the foundation and keep gutters and drains clear.
- Maintain grading so surface water moves away from the home, where local conditions permit.
- Inspect visible foundation walls and seal small openings before water and freeze-thaw cycles worsen them.
- Test sump pumps and backwater valves according to the manufacturer or installer, and record service work.
Repair Drainage and Maintenance Problems Early
Depending on what’s going on, call a structural engineer qualified to assess movement in a building, or a plumber or drainage specialist qualified to identify the source of the water. Signs to call a professional include repeated water ingress, new cracking, sticking doors, bowing walls and sloping floors. Match the professional’s expertise to the suspected cause of the problem.
Evaluate Policy Limits and Deductibles
An endorsement can have its own limit, deductible, waiting condition or exclusion. Ask for a specimen or the actual endorsement and compare it with your restoration cost. A low premium does not establish that the most likely water source at your property is covered.
Read More: Read the Guide to Dwelling Coverage