4.7
★★★★★ 4.8/5
on Google and Facebook!

Find Low Tenant Insurance Rates in Ontario: Get a Free Quote

3 minutes can save you hundreds. Enter your postal code below and join thousands of Canadians saving on tenant insurance.

Secure. No Spam. No Fees.

Why Use MyChoice

MyChoice.ca is an independent platform that helps Canadians find their best insurance options and make informed financial decisions. Our service is free to use. We may earn a commission from some providers when you buy a policy, but it never affects the price you pay or how products are reviewed. To help ensure accuracy, our content is researched and reviewed by licensed insurance professionals before publication.

square one logo

How to Compare Tenant Insurance Quotes with MyChoice

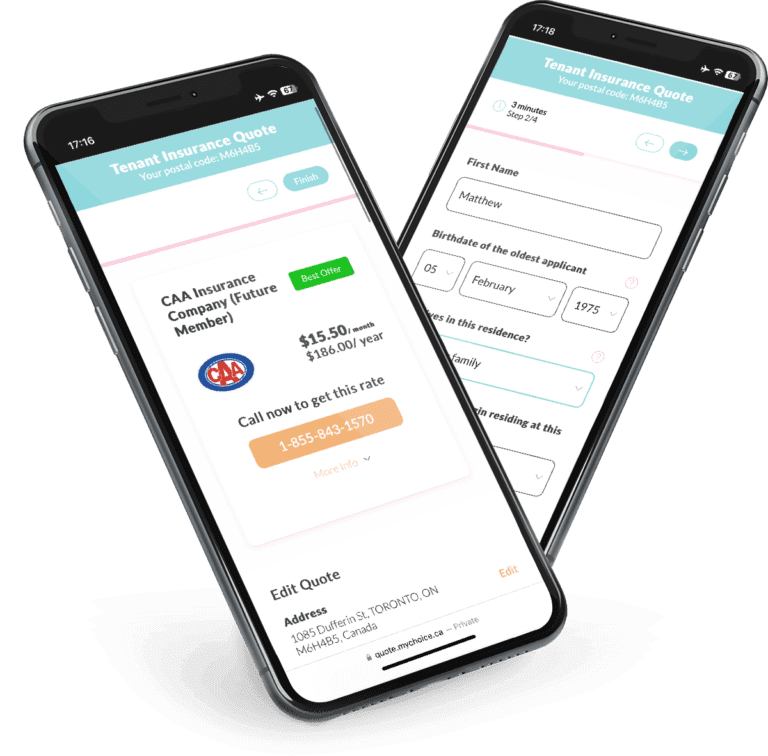
Comparing tenant insurance quotes with MyChoice is as simple as it gets:

Share Your Tenant Insurance Needs

Tell us what you want out of your tenant insurance.

Shop for the Best Deals​

Compare tenant insurance quotes from the best Canadian insurers.

Secure Your Rates​

Pick the best deal and lock your rates on our site.​

Recent Quotes From Our Users

Monthly PremiumsDateQuote TypeAgeGenderCity
$12.36Nov 07, 2026Tenant31FemaleBurlington
$28.87Nov 07, 2026Tenant43FemaleBrantford
$13.59Nov 06, 2026Tenant40MaleNiagara Falls
$14.56Nov 06, 2026Tenant37FemaleNorth York

How MyChoice Works

Posted on Google Google
Amy Sacco profile picture
Amy Sacco
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
Great service. And best home insurance rates provided.
Posted on Google Google
Laura Okah profile picture
Laura Okah
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
Great platform, I had an advisor reach out to me almost immediately after signing up and they made sure to work around my schedule
Posted on Google Google
Vaarunan Srikumaraguru (vaarunan.s) profile picture
Vaarunan Srikumaraguru (vaarunan.s)
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
The experience in receiving a quote was very easy and was quite competitive. The process was straightforward. Would highly recommend this tool
Posted on Google Google
Diana Goyette profile picture
Diana Goyette
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
Quotes were really good and it was easy to sign up with selected company
Posted on Google Google
jakss sss profile picture
jakss sss
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
I recently tried MyChoice to look at homeowner insurance options and the process was very fast. The website only required a few basic details about the property to get started. After entering the address, a lot of the home information was already filled in automatically, so I just had to confirm that everything was correct before continuing. Within a short time, the site displayed a few insurance quotes from different providers. Having several prices shown together made it easy to see the differences and decide which option seemed the most reasonable. I also liked that MyChoice included a bit of background information about the brokers connected to each quote. This gave me a better idea of who the provider was and added some helpful context before choosing anything. Overall, MyChoice is a convenient way to check insurance rates if you're exploring your options. It’s simple to use, quick, and helpful for comparing offers without having to search multiple websites.
Posted on Google Google
kayden uintavious profile picture
kayden uintavious
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
saved me a lot
Secure. No Spam. No Fees.
First published on October 16, 2023

9 minute read

✎ Updated By Vitalii Starov on September 24, 2026

MyChoice follows a strict content review process designed to ensure reliable and unbiased information.

Many different types of renters may be looking for tenant insurance in Ontario, including occupants living in an apartment building, a basement suite, or in a house with other people.

The cost of replacing contents, water damage coverage for the rental unit and the length of time that relocation costs are paid for after a claim are common tenant insurance considerations.

It’s important to understand that a landlord’s insurance does not insure the tenant’s liability or belongings. A landlord’s insurance does cover the structure of the building. Always check who is insured, how claims are paid out for belongings, and exclusions on water damage in a unit.

On this page we’ve broken down insurance quotes from MyChoice’s quote database based on location, square footage and age of property in Ontario. Learn more about tenant insurance, how the cost is determined, common endorsements, and compare quotes using identical deductibles and limits.

Ontario Tenant Insurance at a Glance

The median tenant insurance premium in Ontario is $326 a year, or about $27 per month.

Compare your quotes, customized according to your needs for contents and liability limits, deductibles and water options, to this number.

Median annual tenant insurance premium$326
Median monthly tenant insurance premium$27
Lowest-Premium City for Tenant Insurance in OntarioSudbury ($269)
Highest-Premium City for Tenant Insurance in OntarioEtobicoke ($375)
Postal-area range in the datasetL7R (Burlington) $268 to M8Y (Etobicoke) $416
Source: MyChoice Quote Database, 2026.

Ontario Tenant Insurance Premiums by City

For example, the city median rate in Sudbury is $269 whereas in Etobicoke the median is $375, which is a difference of $106 a year among Ontario’s city medians. For more local info, follow the links to each city’s web page.

Keep in mind, however, that medians are a starting point. To get a sense of the price of insurance on a specific rental, you’ll need to compare policies with similar contents and liability coverage, deductibles, water endorsements and so on.

What Goes Into a Tenant Insurance Premium in Ontario?

Find out what your water endorsements cover. Coverage for sewer backup, overland water and groundwater may have different limits, deductibles and eligibility.

In Ontario, contents are 77.0% of the premium. Optional endorsements are 11.0%. Find out what that 11.0% gets you.

Coverage ComponentWhat It Generally CoversMedian Annual Tenant Insurance Premium Allocation
Contents / Personal PropertyReimbursement of your belongings which are damaged or lost as result of a covered event up to the amount of coverage (limit of liability), subject to deductible and method of payment.$251
Personal Liability and Voluntary MedicalCoverage for property damage or bodily injury for which you (the insured) could be held legally liable.$25
Additional Living ExpensesCoverage for additional living expense if a covered event makes your home unlivable, subject to policy terms and conditions.$14
Optional Water and Other EndorsementsMay be available for sewer backup/overland water, groundwater, identity theft and others, depending on insurance carrier.$36
Coverage Total$326
Source: MyChoice Quote Database, 2026.

Ontario Tenant Insurance Premiums by Unit Size

Rental Unit SizeMedian Annual Tenant Insurance Premium
Under 500 sq. ft.$271
500–799 sq. ft.$300
800–1,199 sq. ft.$326
1,200–1,599 sq. ft.$359
1,600+ sq. ft.$401
Source: MyChoice Quote Database, 2026.

Ontario Tenant Insurance Premiums by Building Age

If your rental is an older property, ask your landlord if there are any updates to the heating, electrical, plumbing, and fire-safety systems. Provide any verifiable information to your insurer.

Older properties can affect your price: The average renter pays $372 per year to insure a rental built before 1940 versus $317 per year for a rental built in 2020 or later.

Building Construction PeriodMedian Annual Tenant Insurance Premium
Before 1940$372
1940–1959$358
1960–1979$343
1980–1999$333
2000–2009$326
2010–2019$322
2020 or newer$317
Source: MyChoice Quote Database, 2026.

Popular Tenant Insurance Add-ons in Ontario

Of the quotes in Ontario, 48.9% of renters chose sewer backup coverage and 46.7% chose overland water coverage. These are important to have if applicable to the address and floor of the unit. When in doubt ask your insurance agent.

Identity theft coverage was selected by 40.3% of Ontario renters. Before adding this to your policy it would be a good idea to find out if this is included with other sources.

Selected CoverageShare of Ontario Quotes
Sewer backup48.9%
Overland water46.7%
Identity theft40.3%
Food-freezer contents21.3%
Source: MyChoice Quote Database, 2026.

Is Tenant Insurance Mandatory in Ontario?

As a rule, tenants aren’t required to have tenant insurance in Ontario. However, a landlord may require it and ask for proof of coverage. Check the lease for any insurance requirements and liability limits. Contents insurance is not automatically included with the standard lease.

Why Do I Need Tenant Insurance in Ontario?

While a landlord’s insurance policy will cover the building itself, renters should consider getting their own insurance to ensure that they are properly protected.

Protection for your belongings

For example, if your stuff is damaged because of a covered event such as theft, vandalism, or fire, contents coverage helps pay to fix or replace your belongings. Of course, coverage is limited by policy terms, coverage limits and deductibles.

Lease and liability requirements

Personal liability coverage may pay when a tenant is held liable for unintentional injury to a person or damage to their property. Depending on policy terms, it may help pay legal expenses if the renter is taken to court. Some leases or rental contracts require tenants to have liability insurance.

Additional living expenses

Finally, if a covered event renders your home uninhabitable and you’re forced to relocate, tenant insurance helps pay additional-living-expense claims, meaning costs above normal household expenditures up to policy limits and duration.

How Does Tenant Insurance in Ontario Work?

The form, amount of coverage offered, deductibles and exclusions vary by insurance company. Ontario tenant policies usually provide three main types of coverage.

Your personal belongings may be insured for their replacement cost or actual cash value, as indicated in your policy. This coverage usually operates on a named-perils basis, although some policies offer a broader all-risks form that provides coverage for accidental loss or damage unless excluded.

Personal liability pays damages and legal defence costs, up to a limit you have chosen, if an insured is found legally liable for covered bodily injury or property damage to others.

Additional living expense coverage pays eligible expenses caused by a covered loss that temporarily makes your rental unit unlivable. Coverage is limited by the amounts listed in the policy. Some losses from interruptions of services or utilities and certain evacuation situations are not covered.

Also ask about endorsements or additional coverages available for your Ontario tenant policy. Examples include water damage, sewer backup, overland water, earthquake, valuables coverage, identity theft coverage, improvements or alterations to the rental unit, and business operations coverage. Find out whether any of these coverages cost extra, have specific limits or deductibles, or may not be available.

What Is Not Included in a Typical Ontario Tenant Insurance Policy?

An Ontario tenant insurance policy may cover many types of unexpected losses, but it also has certain limits, exclusions and conditions. The declarations should be examined together with the policy wording.

Criminal activities

If your policy covers theft or vandalism as a cause of loss, losses from vandalism and theft perpetrated by an unrelated third party may be covered. Most policies exclude losses caused by illegal or intentional actions of the insured.

Earthquakes

Earthquake coverage may be available as an option. If so, check whether it covers contents and additional living expenses, and whether a separate earthquake deductible might apply. Policies generally do not cover losses from earth movement.

Maintenance and gradual damage

Damage due to ageing, normal wear and tear, or gradual damage is usually not insured. Inform the landlord in writing of any leaks, mould, heating problems or other deficiencies. Follow the precautions in your insurance policy concerning low temperatures and longer absences.

Flood and sewer backup

Sewer backup, overland water and groundwater are not the same and could require different endorsements. Make sure you have the policy that corresponds to the exact unit and floor. Record the limit and deductible for each coverage selected.

Home business activities

If you’re conducting a business from home, call your insurer, disclose this fact and ask whether you need an endorsement on the policy or a business insurance policy. Business inventory, equipment and liability coverage could be limited or nonexistent under a tenant policy.

Pest damage

Check the wording of the policy, as damage caused by insects or rodents usually is not covered, and secondary or consequential losses may or may not be covered.

Mould

Also keep in mind that insurers commonly limit coverage for mould, contamination or rot. Such exclusions are common when mould and contamination arise from leaks, repeated water intrusion or a history of inadequate maintenance. Being insured for the original loss doesn’t necessarily mean you’ll be compensated for the cost of cleanup.

Unoccupied rental risks

Do not rely on your roommates’ rules of thumb about how long an apartment can be vacant during vacations, between semesters or on a permanent basis. Your insurer will tell you when you must notify them, allow an inspection, keep the heat at a certain level or turn off the water.

What Determines The Cost of Tenant Insurance in Ontario?

Tenant insurance rates are not all the same because insurers use a number of criteria to underwrite tenant insurance, including the address and type of building you’re renting, the coverage you’ve chosen and your insurance history.

Location and building characteristics

The price and availability of optional water coverage may vary by unit, building, construction type, fire protection and loss experience.

Contents and liability limits

Rather than choosing an arbitrary contents limit, create a realistic inventory. Generally, the higher the limit on contents, valuables or liability, the higher the sum that might be paid by your insurer.

Claims history

Claims can affect future rates and insurance eligibility. It may not always make sense to report small property losses. Consider how much you would receive, compare it with your policy’s deductible and think about the potential effect of the claim.

Deductible

Keep in mind that choosing a higher deductible may reduce your premium. However, it’s important to make sure you can afford the deductible should a loss occur.

Occupancy and use

Be sure to report the actual use and occupancy of the unit; don’t assume everything is covered. For example, risk varies depending on factors such as roommates, pets, smoking, home businesses and periods of absence.

Insurer and discounts

Items owned by the landlord are generally not covered by a tenant policy. Do not assume they are insured unless coverage is spelled out in the policy. Some insurance companies do not cover unrelated roommates, so confirm every roommate’s coverage in writing.

How Can You Find Cheaper Tenant Insurance in Ontario?

If you want to reduce the price without giving up coverage, compare Ontario quotes with the same contents and liability limits, deductibles and water endorsements. Make an honest inventory, ask about multi-policy discounts and select a deductible you could afford right away if you made a claim.

Compare quotes

Keep the contents limit, liability limit, deductible and water options the same when comparing insurance quotes. Otherwise, a low-priced policy could be deceptively inexpensive because it offers less coverage.

Choose a deductible you can afford

Ask what premiums are available with different deductibles, but don’t choose one you couldn’t pay in the event of a claim.

Bundle with auto insurance

Shop around. Some insurers may offer a discount on tenant insurance if you have auto insurance with the same insurer. Don’t just consider the discount; evaluate the extent of coverage and the combined price.

Ask about recognized safety features

Get your landlord’s approval before making changes to the rental. Some insurers offer discounts for approved smoke detectors, a monitored burglar alarm or other safety devices.

Review your contents inventory

Use an inventory to help determine a realistic contents limit. If your standard sublimits are not enough to adequately cover items such as jewellery, bicycles, collectibles or electronics, consider scheduling those items.

Review payment options

Determine what you’ll be paying for insurance overall each year. Some insurers charge a fee for installment payments. Choose a payment option that suits your household budget from the insurer’s available options.

Who Provides Tenant Insurance Quotes In Ontario

Ontario renters can get tenant insurance in a number of ways.

Insurance brokers

A licensed broker may obtain quotations from insurers they are licensed to represent and assist the buyer with understanding coverage options, including differences in policy limitations, exclusions and endorsements.

Direct writers

A direct insurer distributes its products through its own website, call centre or staff. It does not use independent brokers.

Insurance agents

Find out whether the agent represents one insurer or works through an agency arrangement. Then ask which companies they can provide a quote from.

Comparison platforms

Always double-check the policy wording and coverage before purchasing. Sites such as MyChoice allow you to enter your information once and see quotes from participating insurance providers.

FAQs About Tenant Insurance in Ontario

Is tenant insurance legally required in Ontario?

No. Although a landlord and tenant may include a provision in their standard lease requiring liability insurance, Ontario law does not require every tenant to have tenant insurance.

Can landlords require tenant insurance in Ontario?

Yes, as long as that requirement was part of the signed lease. If the requirement was added later or you are disputing it, review the lease that was signed. Ontario’s standard lease includes a section where the landlord and tenant can agree to require liability insurance.

How quickly can I get tenant insurance in Ontario?

Many simple policies can be quoted and issued very quickly after the insurer receives the necessary information and payment. Regardless of when you begin the application, coverage starts on the effective date shown on the policy or certificate.

What does tenant liability insurance cover?

Damages and defence costs may be paid under the policy when an insured is legally responsible for covered bodily injury or property damage. Not all injuries and damage are covered. Damages resulting from intentional acts and business-related liabilities are not typically covered.

What is the difference between home and tenant insurance?

The main difference between home insurance and tenant insurance is that home insurance covers the home, while tenant insurance does not because the building is the landlord’s responsibility. Both generally provide coverage for personal possessions, liability and additional living expenses.

Does one tenant policy cover every roommate?

Contact your insurer and let them know that you have a roommate. Coverage varies from policy to policy, and your roommate may need to be added to your policy or may need their own. Don’t assume your insurer will extend coverage just because you’re all at the same address.

Methodology

Profiles

Average rates were calculated using a standard profile and incident profiles. All personal details pertaining to the quotes and policies have been kept confidential.

Standard Profile

Quoted rates are based on either a 35-year-old male and/or female tenant with a clean claim history and good credit. They are also non-smokers and live in a home with monitored fire alarms and burglar alarms. The tenants also have a $1,000 deductible, a $1,000,000 liability, a $30,000 personal property limit and water damage included.

Incident Profiles

We examined how rates change by evaluating incident profiles. We looked at the most common tenant insurance claims in Canada: theft, fire-related, accidental injury, and water damage claims while comparing them to a clean record (standard).

Home Details

Quoted rates are based on either a duplex or triplex home constructed in the year 2010 or later.

Team

MyChoice data science, MyChoice research.

Sources

1. MyChoice.ca Internal Data, Tenant Insurance Key Premium Facts in Ontario, 2026

2. MyChoice.ca Internal Data, Tenant Insurance Rates by Postal Code in Ontario, 2026

3. MyChoice.ca Internal Data, Tenant Insurance Coverage Breakdown in Ontario, 2026

4. MyChoice.ca Internal Data, Tenant Insurance Rates by Unit Size in Ontario, 2026

5. MyChoice.ca Internal Data, Tenant Insurance Rates by Building Age in Ontario, 2026

6. MyChoice.ca Internal Data, Popular Tenant Insurance Coverages in Ontario, 2026

With over 7 years in the insurance industry, Matt focuses on home and life insurance, offering sharp analysis and insights on underwriting trends, coverage structures, and how market changes impact consumers.

Congratulations! You made it to the end!

Now, here is the easy part: complete your quote in under 2 minutes
Secure. No Spam. No Fees.

Discover More About

October 22, 2026
Which heating systems cost more to insure? See how oil, electric, propane, heat pumps and hot-water systems compared with gas in Ontario quotes.
October 7, 2026
Learn how jewellery limits work under home and tenant insurance, when to schedule engagement rings and watches, and what records to keep for a claim.
September 28, 2026
Learn how identity theft and personal cyber insurance protect homeowners, what each option covers, typical costs and what to do after online fraud.

Even More Ways To Save on Insurance