









A claim may be delayed while the insurer investigates coverage, collects documents, or decides on the scope of repairs. While a delay doesn’t necessarily indicate anything bad, you’re entitled to know what items may be holding it up and what you can do to speed it up.
Our editorial team reviewed the Financial Consumer Agency of Canada’s claim guide, FCAC’s insurance-complaint process, the General Insurance OmbudService process, and FSRA’s Ontario home-claims review to prepare this guide.
What Should You Do If A Home Insurance Claim Is Delayed?
- Get details from your adjuster in writing. Ask about the status of the claim, what information or decisions are outstanding, who is responsible for the next step and how long that step is expected to take.
- If things aren’t moving, ask to speak with your adjuster’s supervisor.
- If you’re not successful with the supervisor, ask for details on your insurer’s dispute and complaint process.
- Once you get the final position letter from your insurer, you can ask the General Insurance OmbudService to review the dispute.
| If the file is waiting for | Ask this | Send or preserve this |
|---|---|---|
| Coverage decision | Which policy clause and fact remain under review? | Policy, photos, chronology, reports and the insurer’s written requests |
| Proof of ownership or value | Which items lack acceptable support? | Receipts, statements, photos, manuals, serial numbers and replacement examples |
| Cause-of-loss report | Who retained the expert and when is the report due? | Send or keep available for inspection all damaged parts. Keep your own qualified report available if necessary. |
| Repair scope or price | Which line items or rates are disputed? | Itemized estimates, measurements, permits and material specifications |
| Third-party information | What was requested, from whom and on what date? | Consent forms and copies of records that you can get directly. |
How A Home Insurance Claim Moves Forward
Report the loss as soon as possible as required by your insurance policy. FCAC says claim-submission limits commonly range from 90 days to 12 months, not a universal 48 to 72 hours. Different time frames may apply to notice, proof of loss, cooperation with the insurance company and legal limitation periods.
The insurance company will need to verify the facts of the case, determine the cause of loss, apply the terms of the insurance policy and evaluate the amount of the damage. Often, the process includes help from several specialists, including an adjuster, restoration contractor, engineer, accountant, or another specialist.
Sometimes a claim moves forward with partial approvals for repairs that aren’t in question, emergency repairs, contents payments or additional living expenses while other issues are being determined.
When safe, take reasonable steps to avoid additional damage to your property. This doesn’t change because of a delay. Save receipts for any expense and keep damaged materials whenever possible. Take photos of conditions before disturbing them. It’s best to avoid making permanent repairs and disposing of damaged materials until you receive permission from your insurance company.
Read More: See How to Manage a Home Insurance Claim Adjuster
What Are Common Reasons For Claim Delays?
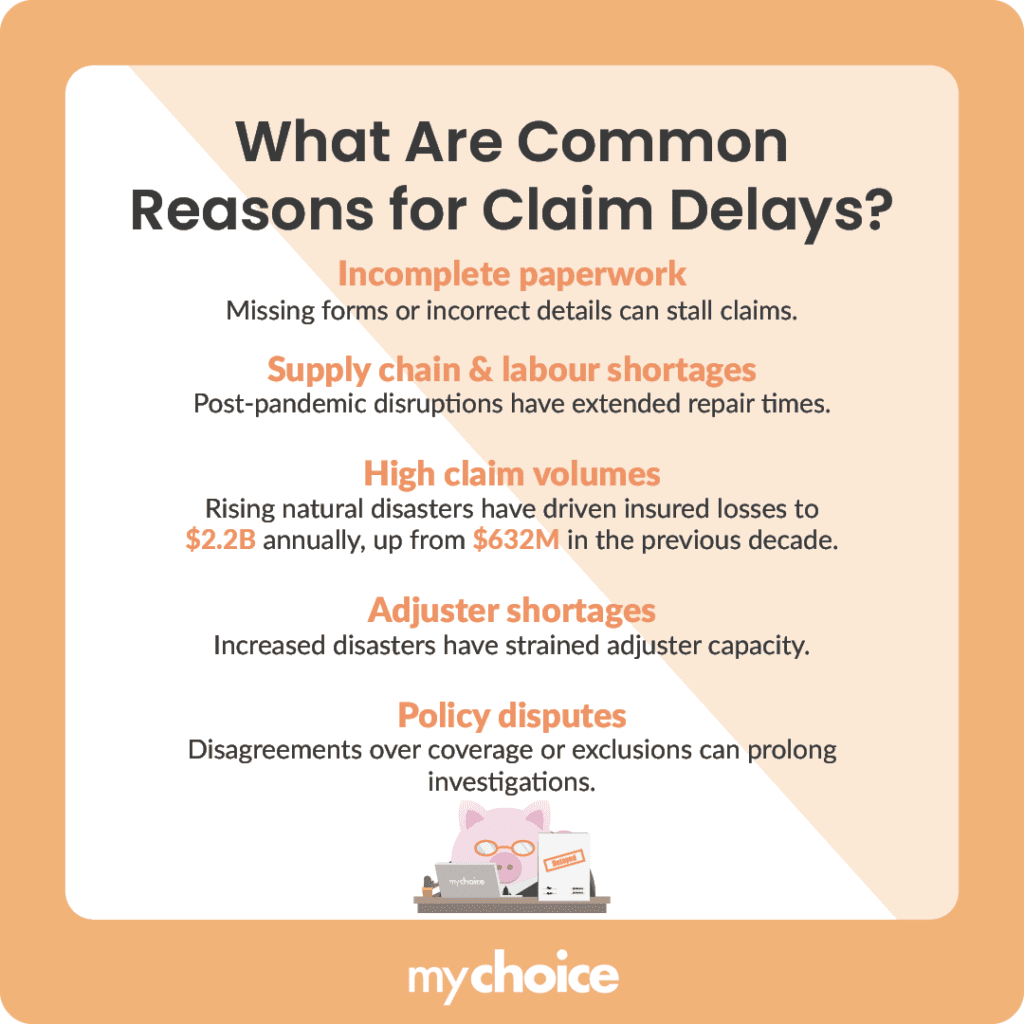
| Reason | Legitimate question to resolve | Warning sign |
|---|---|---|
| Incomplete documents | What specific form, estimate or proof is missing? | Repeated broad requests without identifying the gap |
| Coverage investigation | Which cause, exclusion or condition is being assessed? | No written explanation of the policy issue |
| Large or technical loss | Which expert report or repair decision is outstanding? | No target date or owner for the next action |
| Catastrophe volume | Can emergency or undisputed work proceed first? | Essential contact stops without an alternate representative |
| Scope or price dispute | Which repair items, quantities or rates differ? | A total is rejected without line-by-line reasons |
| Fraud review | What information can you provide and what remains unresolved? | Requests things unrelated to the stated concern. No update despite follow-up. |
There is no one-size-fits-all answer that applies fairly to all Canadians. Claim duration depends on the circumstances of the loss, the evidence, repair market conditions, the terms of the policy, and any disputes.
Read More: Review Common Home-Claim Settlement Valuation Methods
What Can You Do While The Claim Is Delayed?
- Keep a log of your claim. Record who you dealt with and what was requested, the promised action and due date, and the result.
- Send all documents to the adjuster as a package. Prepare an index and label it clearly. Ask the adjuster to confirm receipt of all documents.
- Divide your claim into agreed and disputed portions.
- Ask whether an advance or partial payment is available without signing a full release.
- If you can’t live in your home, track the limit and duration of your additional living expense benefits and how much remains. Track expenses above what you normally spend and keep the receipts.
- Ask the insurer before changing your contractor, expanding the scope of repairs, disposing of damaged items, or signing a direction-to-pay form.
- File a complaint, but keep track of contractual and legal deadlines. Complaints don’t stop these clocks. Get legal advice if a limitation period is about to run.
Provincial Differences To Keep In Mind
Insurance is regulated at the provincial/territorial level, so the available rules and legal remedies depend on your province/territory. It’s important to understand what powers insurance regulators have. For example, they can investigate whether insurers are following rules, but they may not determine the value of your loss or order an insurer to settle your claim. Each province/territory has a regulator and legal time limits, and FCAC explains the national complaint process. For example:
- Quebec residents can contact the Autorité des marchés financiers.
- In Ontario, FSRA’s 2024 review found inconsistent proof-of-loss tracking and gaps in customer communication among the insurers reviewed. This doesn’t prove your insurer mishandled your claim, but if yours is taking too long, it’s reasonable to ask for an update.
When To Escalate A Delayed Claim
- Ask the adjuster or claim supervisor to resolve the specific delay and respond in writing.
- Follow the complaint process used by the insurer. Ask for a final position letter, making it clear what result you want.
- If it’s a home-insurance matter and the insurer is a GIO subscriber, you can refer your complaint to GIO after you’ve received a final position letter from the insurer. GIO’s service is impartial and free. Its final recommendation is not binding.
- Contact your provincial or territorial regulator if you have concerns about the insurer’s conduct, or about whether it is meeting its regulatory requirements. The Office of the Superintendent of Financial Institutions (OSFI) is not the right avenue for help with decisions made about individual home claims.
- Talk to a lawyer before a legal limitation period expires. It’s a good idea to seek independent legal advice, if appropriate, for example, about releases you may be asked to sign, coverage disagreements, or disputed claim amounts.