









If a laptop, new gaming console, clothing or piece of furniture is damaged by fire or stolen, you might feel confident that the contents coverage in your home or tenant insurance policy will be there to provide protection.
But you may want to double-check before assuming the same coverage also extends to the full value of your luxury watch or expensive ring.
Claims involving jewellery and other high-value items are frequently subject to restrictions within a home insurance policy, but for those with items or collections that are worth far more than these limits, the good news is there are options available that can change both the amount and types of losses covered.
To help homeowners and tenants decide whether to consider purchasing additional coverage for luxury items like jewellery, we reviewed information from the Insurance Bureau of Canada, groups like the Canadian Jewellers Association and policy specifics. We also checked 2026 Ontario data from our MyChoice quote database to find out the amount of coverage and the types of policies homeowners and tenants commonly seek for jewellery.
How Much Jewellery Insurance Do You Actually Need?
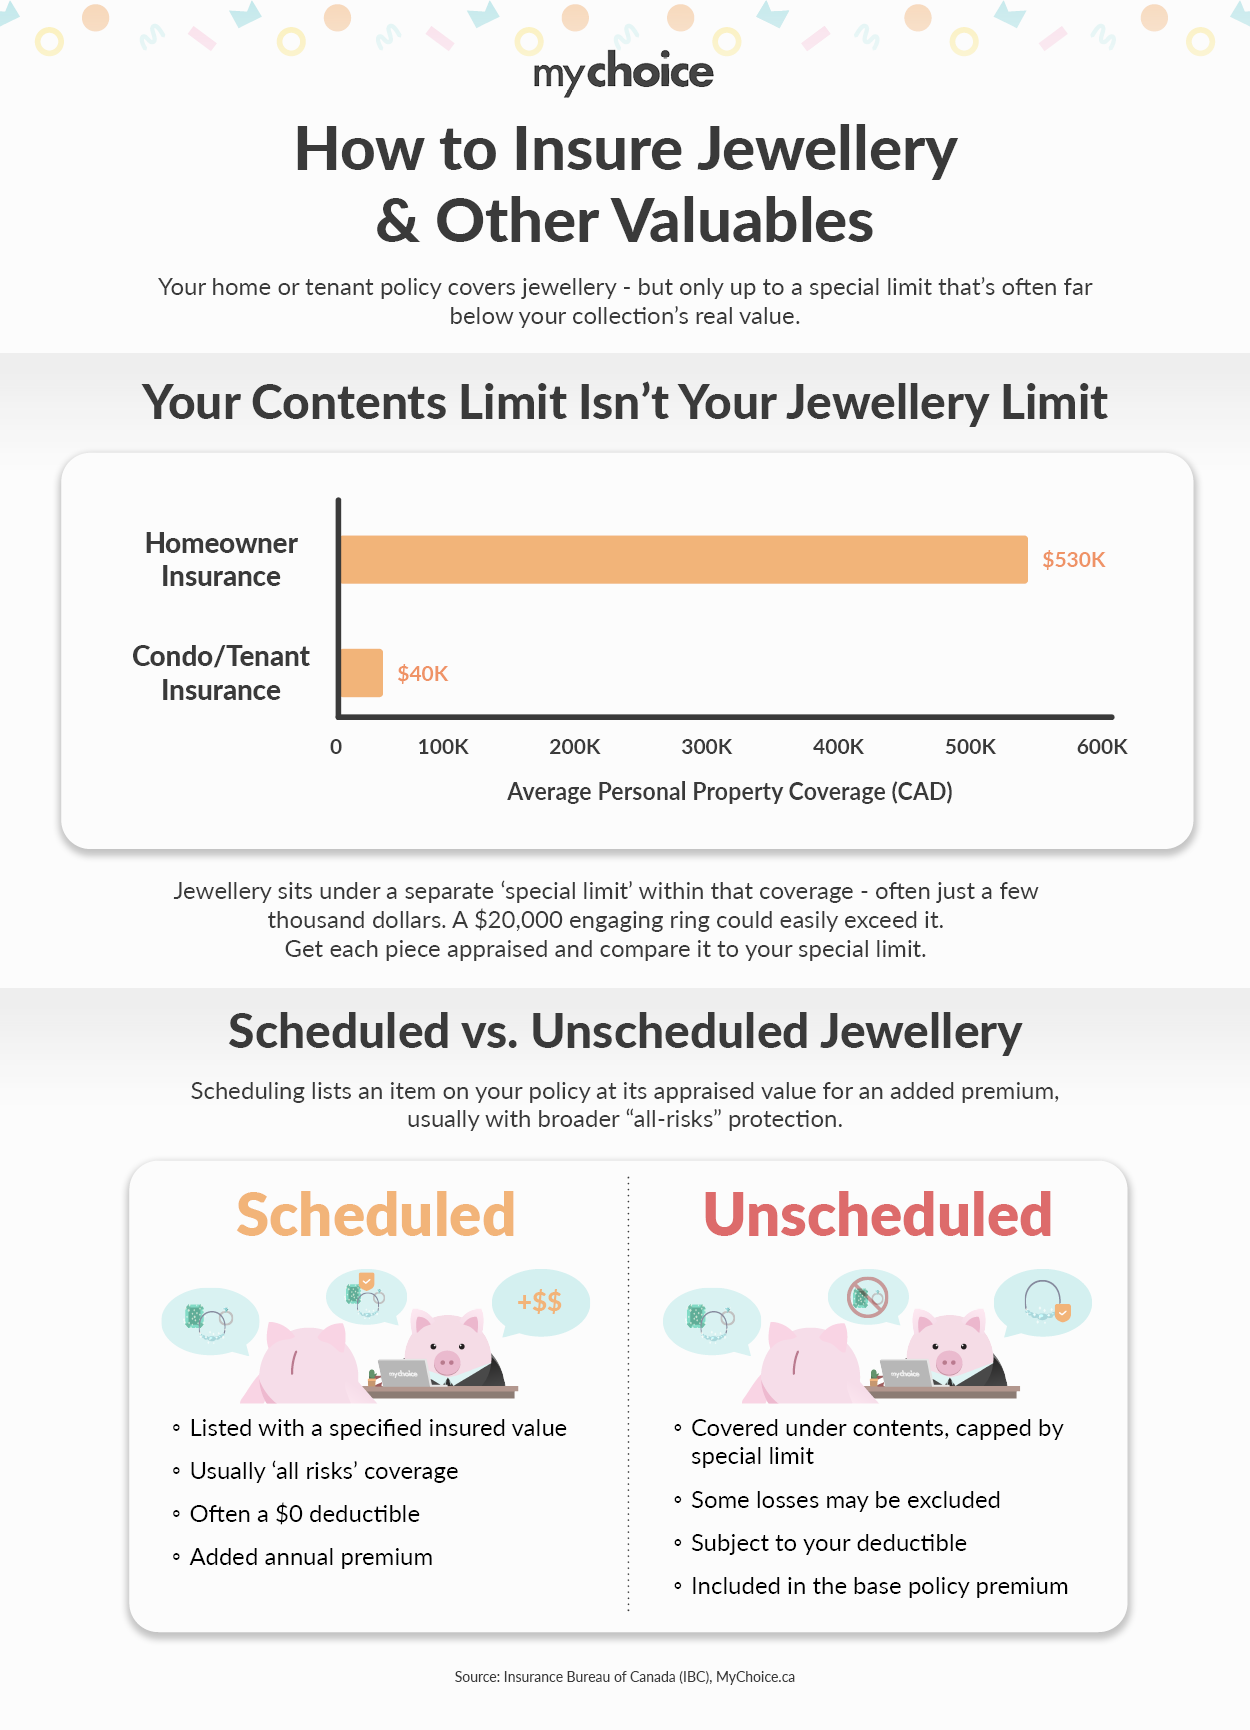
Your home, condo or tenant insurance policy generally offers some coverage for jewellery, but it has separate limits under your home contents, and claims are subject to a cap usually in the neighbourhood of a few thousand dollars or possibly even less for theft.
Depending on what you own, this may be enough. But if your collection includes pricier items like a $20,000 engagement ring, for example, there’s a chance your policy may not cover its full value in the event of loss.
To determine whether you need additional insurance for higher-value jewellery, it’s important to confirm the replacement value of each item, which may differ from the purchase price or the last time they were professionally appraised.
Do an inventory of jewellery items you consider to be high value. Then, have those items appraised by an accredited appraiser or certified gemmologist to find out their replacement value. Compare these amounts against your policy’s jewellery-specific special limits.
If your home insurance policy limit falls short of the value of your jewellery, you may want to consider purchasing additional coverage.
The Coverage Blind Spot
The personal property or contents portion of your home or tenant insurance policy typically covers damage or loss to the personal property you own, wear or use on the premises, for covered risks. It may also cover your contents while they are temporarily away from your home, anywhere in the world.
Many homeowner policies calculate contents coverage as a percentage of the total insured dwelling amount. According to MyChoice quote data, the average contents limit for Ontario homeowners is about $530,000.
This might seem like a lot of coverage, but your overall contents limit does not tell you how much actually applies to jewellery. Under most policies, high-value items, like jewellery, have a separate sub-category, with a “special limit” as to how much you’re able to claim.
Some policies may also exclude certain circumstances or perils for which they will cover jewellery. For example, “mysterious disappearance” or accidental losses may not be covered or, if they are, may be subject to limits.
A jewellery claim under your home contents will also be subject to a deductible and, depending on a policy’s settlement terms, your insurer may pay to replace an item based either on its actual cash value or replacement cost.
But as IBC explains, endorsements that offer higher limits for things like jewellery, watercraft, fine art or antiques can be added to your policy to provide protection over and above the special limit.
What Is Scheduling?
When you schedule a piece of jewellery or other valuable item, it will be mentioned specifically on your policy as an insured item, covered up to its specified insured value worldwide and subject to an additional premium. Some insurers will schedule a group of items for a blanket amount.
According to Ontario 2026 proprietary data from our MyChoice quote database, in quotes that included scheduled jewellery, the average value was $16,000, representing only 3.4% of total contents coverage.
This coverage also frequently has different claim terms than the contents covered under the broader policy. For example, 56% of scheduled jewellery quoted in the MyChoice data carried a nil deductible.
Some 97% of scheduled jewellery in Ontario was also quoted on an “all risks” basis, which may cover losses in scenarios like theft, accidental damage or loss and disappearance.
In some cases, this may provide broader protection than personal property coverage in a home insurance policy or contents insurance as a tenant, depending on the insurer and policy wording.
Scheduled vs. Unscheduled Jewellery
| Scheduled | Unscheduled |
|---|---|
| Separate item under policy, specified insured value | Included as subcategory under contents, losses capped by jewellery-specific limits |
| Often insured for “all risks” | Some losses may be excluded |
| Often $0 deductible | Subject to deductible |
| Additional annual premium | Included in policy premium |
When Should You Schedule a Ring or Valuable?
Deciding whether to schedule or purchase an endorsement for jewellery or another high-value item in your home insurance policy comes down to one simple calculation: are your policy’s limits sufficient to cover replacement of the item in case of loss or theft? If not, scheduling may be something to consider.
What Documentation Should You Keep?
In case of a claim, you’ll need detailed documentation proving value and ownership of your high-value items. Make sure you have photos, original purchase receipts, the insurance appraisal report, which sets out the top replacement value and a detailed description of the item, says the Canadian Jewellers Association, as well as any serial numbers or certificates. Some policies do not require an appraisal for jewellery valued under a certain amount.
What Happens When Values Change?
Scheduling jewellery on your home insurance policy isn’t a “set it and forget it” task since precious metals and gemstone values are constantly in flux and market conditions change, appraisals may become outdated. Check with your insurer as to their specific requirements but, generally, your insurer may suggest re-appraising your pieces every three to five years to ensure your replacement value is accurate. Also, make sure to keep your policy updated if you inherit valuable jewellery or purchase new items.
Other Valuables That May Need Scheduling
Jewellery is the most obvious item for purchasing additional coverage, but you can also schedule other high-value items you own, including art, wine, collectibles such as sports cards, stamps or coins, instruments, bicycles, handbags or silverware.