
Many Canadian homeowners assume their standard home insurance policy covers household appliances, such as furnaces, refrigerators, and air conditioning units. However, this isn’t always the case, and you might find yourself stuck with a hefty repair bill.
To keep this from happening, consider home equipment breakdown coverage as an endorsement to your policy. Discover how this endorsement can complement your standard home insurance and how it can save you money in the long run.
Our team looked through the Financial Consumer Agency of Canada’s guide to unexpected events, the Insurance Bureau of Canada’s explanation of extreme-cold damage, the Financial Consumer Agency of Canada’s home-insurance guide, and Quebec’s consumer-protection guidance on additional warranties.
What Does Home Equipment Breakdown Coverage Do?
Equipment-breakdown coverage is optional coverage in property policies. It covers eligible equipment that suffers from a qualifying breakdown. Depending on the insurer and policy, coverage varies by what is considered covered equipment, what causes of breakdown are covered, what limits and deductibles apply, and other settlement provisions.
According to IBC, equipment-breakdown coverage is not usually included in a home insurance policy. Confirm availability and request the endorsement wording from your insurer to see if you have this coverage.
Home Equipment Breakdown Coverage vs. Standard Home Insurance
The primary difference between home insurance breakdown coverage and standard home insurance is the risks they cover. Standard home insurance covers external events, also known as “perils,” such as fire, theft, vandalism, and natural disasters. It doesn’t cover:
- Wear and tear
- Age-related failure
- Internal malfunctions
Conversely, home insurance breakdown covers sudden and accidental mechanical failures of household systems like:
- Heating and cooling systems
- Kitchen and laundry appliances (i.e. dishwasher, laundry machine)
- Hot water heaters
- Electrical panels
- Home electronics
- Sump pumps
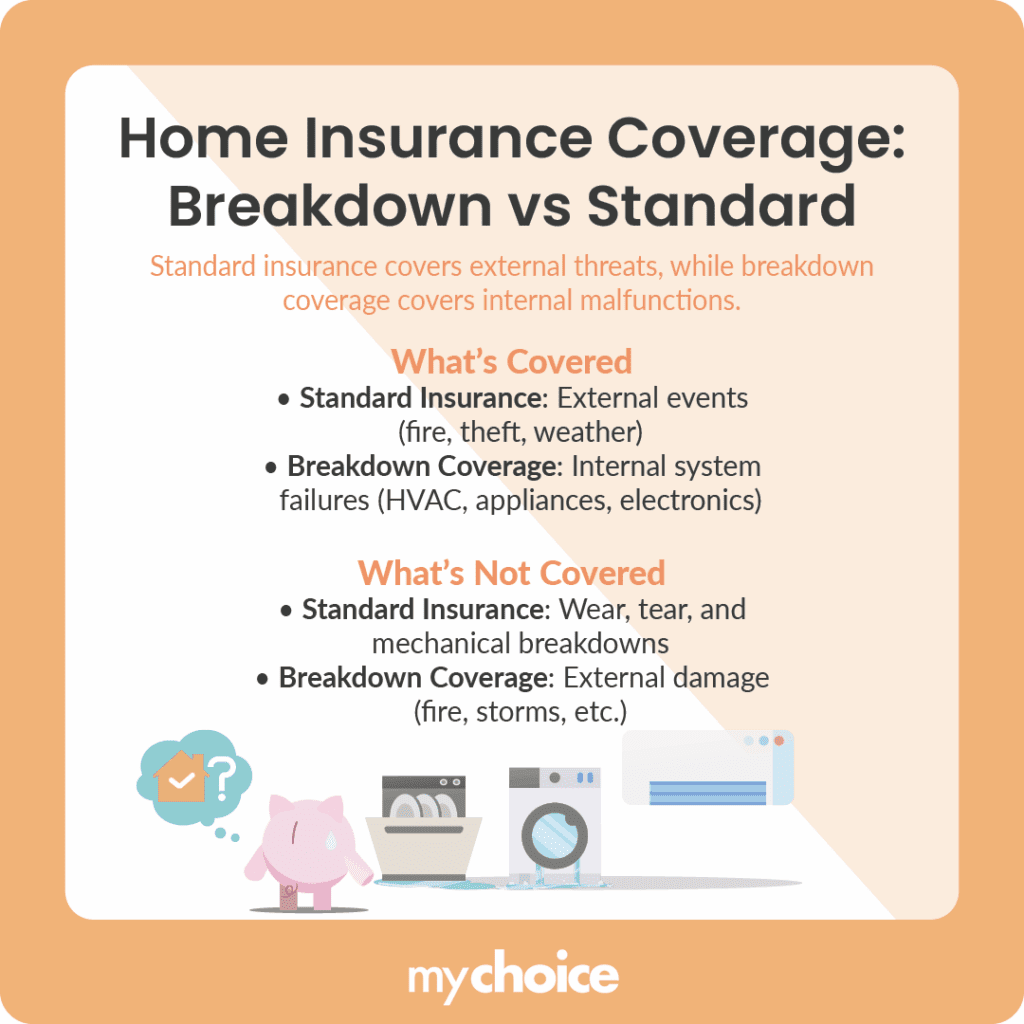
Equipment-breakdown endorsements usually cover specified mechanical, electrical or pressure-system breakdowns. Age, condition, wear, maintenance, depreciation and repair-versus-replacement terms will vary based on insurer and the type of endorsement you have.
Read More: Compare Broad and Comprehensive Home Insurance
How Do I Add Home Equipment Breakdown Coverage to My Policy?
Adding home insurance breakdown coverage to your policy is straightforward. Just follow these steps:
Contact Your Insurance Provider
First, reach out to your insurance provider and ask about adding equipment breakdown coverage. Depending on your insurer, they offer home systems protection or boiler and machinery coverage.
Collect Details and Get a Quote
Ask what this add-on entails, including what items are covered, what the cost limits are, and what your home insurance deductible is. Most insurers offer about $50,000 per occurrence, and you can add this coverage for as little as $29 per year. Depending on your region, costs can go up to $50 per year.
Add the Endorsement to Your Policy
Once you’ve set your terms, instruct your insurer to update the policy documents. This coverage doesn’t typically require an extensive process or a home inspection – it just plugs in.
Double-Check the Specifics
When you receive the renewed policy, review your coverage and deductible. Typically, the deductible is the same as your property insurance deductible, which is usually between $500 and $1,000. For example, if your furnace repair costs $4,000 in damages, you’ll pay the first $500, and insurance will cover the rest.
Coverage Features That Vary by Insurer
| Feature | Question to ask |
|---|---|
| Covered equipment | Are permanently installed systems, appliances, electronics, home batteries, solar equipment or EV chargers included? |
| Cause of breakdown | Does the definition include mechanical, electrical and pressure-system events, and what does it exclude? |
| Age and condition | Are there age limits, depreciation schedules, maintenance duties or pre-existing-damage exclusions? |
| Settlement | Is payment based on repair, replacement cost or depreciated value, and who chooses the repairer? |
| Extra costs | Are spoilage, temporary equipment, expediting expenses, code upgrades or additional living expenses included? |
| Claim process | Must the insurer approve diagnosis or repair, and must you keep the failed part? |
| Limit and deductible | Does one event share a limit across equipment, resulting damage and extra costs? |
Equipment Breakdown Coverage vs. Extended Warranties
An equipment-breakdown endorsement covers many items within a category of household systems in the event of a specified incident. An extended warranty pertains to an individual product.
Keep in mind that neither type of coverage will necessarily pay out in cases of poor maintenance, for all causes of breakdown or failure, or for all resulting costs.
In Quebec, for example, the Office de la protection du consommateur reminds consumers that household appliances come with a legal warranty. It’s a good idea to know what rights you already have before buying extended warranty plans, especially since warranty rules vary from one Canadian province to the next and you may be paying for coverage you already have from the manufacturer.
Read More: Read the Furnace Repair and Maintenance Guide
Is Equipment Breakdown Coverage Worth It?
Endorsements may be of limited value when the cost of equipment is low, the repair cost would be close to the deductible, existing warranties address the biggest concerns or the endorsement does not cover the specific breakdowns of greatest concern.
Compare the cost of the endorsement with the amount that would be received for a claim, taking wear exclusions, depreciation, sublimits and deductibles into account. Comparing that cost with the price of replacing everything is misleading.
Keeping appliances in good working order does not necessarily mean a claim will be covered.