









Unfortunately, renovation damage doesn’t fit into a single insurance category. Depending on what happened, the scale of work done, whether your home is unoccupied, your home insurance terms, who’s at fault, and other factors, your insurance may not cover a claim.
For this overview, we reviewed the Insurance Bureau of Canada’s 2026 renovation and builder’s-risk guide, IBC’s guide to how home rates are set, Health Canada’s asbestos guidance, and WSIB’s construction-clearance guidance.
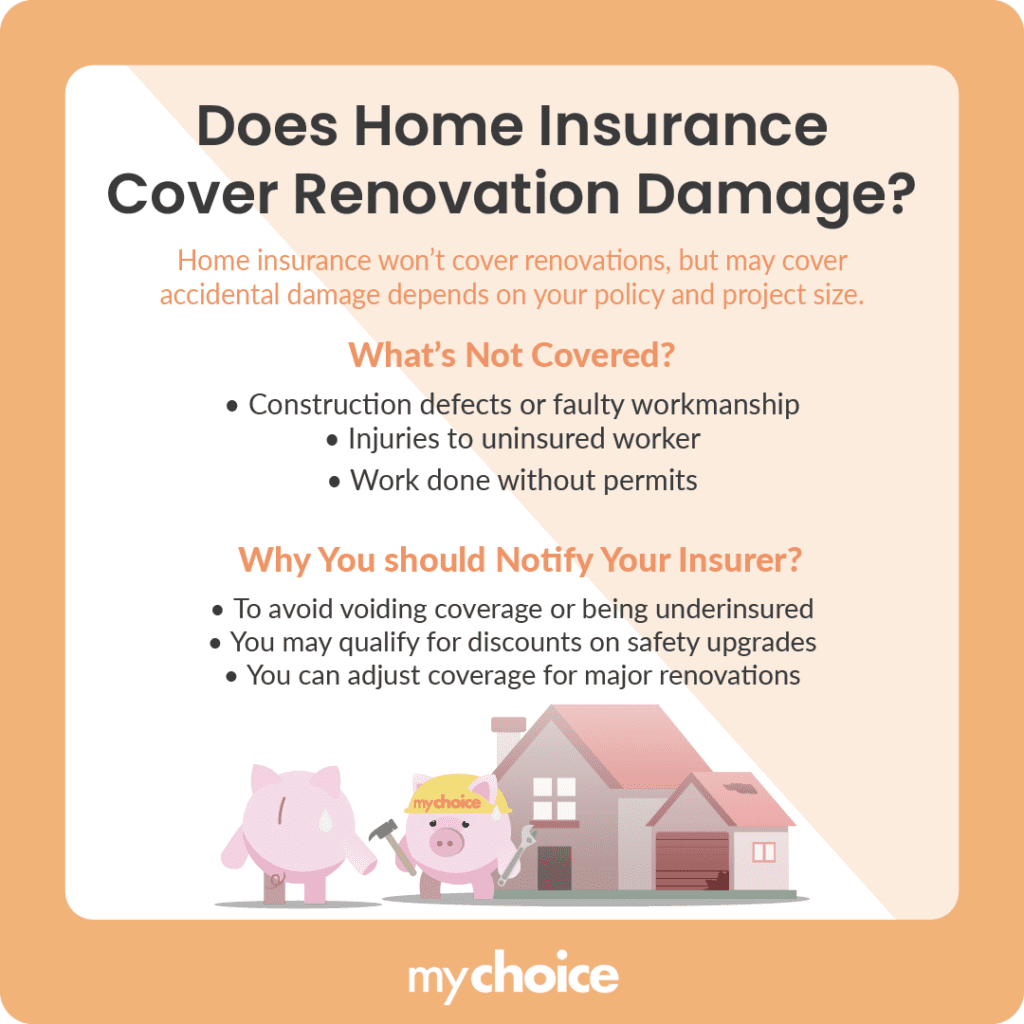
Does Home Insurance Cover Renovation Damage?
You might assume the contractor’s third-party liability insurance would cover losses occurring at your property. It may not cover losses to your home or materials.
Existing home insurance may cover damage to the existing structure from an insured peril, such as fire, during renovations. Typically, coverage does not apply to damage arising out of poor workmanship, although consequential damage may be treated differently, depending on the policy wording. Larger projects may need special coverage, such as course-of-construction or builder’s-risk insurance, for the project, the work itself and building materials. Notify your insurer of your plans.
Case-by-case Scenario Analysis
| Loss or issue | Policy that may respond | Question to resolve before work |
|---|---|---|
| Fire, wind or sudden water damage to the existing home | Subject to the conditions regarding renovations and causes, your current home policy | Has the insurer changed the conditions or deductibles, and has it accepted the project? |
| Theft or damage to building materials | Builder’s risk or course-of-construction coverage | Are materials covered when located on site, off-site in temporary storage or in transit? |
| Faulty workmanship or defective materials | Typically not covered: the defective work itself | Does the wording treat resulting damage separately? |
| A contractor injures someone or damages other property | Contractor’s commercial general liability policy may respond. | Are the operations, limit, policy dates and named business correct? |
| A friend or unpaid helper is injured | Liability depends on the facts and province; workplace rules can also vary. | Has the arrangement been confirmed by the insurer or provincial workplace authority? |
| The finished home costs more to rebuild | Revised home-policy coverage limit and insured-property description | Has the insurer documented the addition, finish level or new use of the property? |
Before Work Starts: A Renovation Insurance Checklist
- Notify the insurer or broker in writing of the planned project, its estimated cost and time frame, and whether you will be living in the home. Confirm whether the current policy will continue to apply, and ask in writing about any new conditions, exclusions, limits or deductibles.
- Notify the insurer or broker of the final project, any extra square footage, new systems, changes of use and updated rebuilding information when the renovation is complete.
- Determine who is responsible for builder’s risk. Make sure you know who is insured, the project value, whether the existing structure and new materials are covered, and when coverage ends.
- Ask the contractor for its legal name and commercial general liability coverage. Contact the insurer or broker listed on the contractor’s certificate to confirm the policy is in force.
- Check with your local building department about permits and inspections.
- Check your province’s workplace-insurance requirements. In Ontario, WSIB clearance is generally not required when a resident hires a contractor to renovate their own home. However, a contractor that hires a subcontractor generally must obtain a WSIB clearance.
- Ask about indemnity, insurance, waiver and damage-to-work clauses in the construction contract before signing.
Read More: Learn How Certificates of Insurance Work
DIY vs. Hired Help: Different Risks, Different Rules
If you’re going to do it yourself, be aware that you’re responsible for getting permits, complying with building codes and ensuring a safe jobsite. Personal liability insurance may not cover injuries to workers, friends or volunteers. Tell your insurer who is helping and what the compensation terms are.
If you hire a contractor, you reduce your risk only if the contractor is properly qualified, you have a good contract, and the contractor has the right insurance. A contractor’s commercial general liability policy covers its liability for certain kinds of bodily injury and property damage. It isn’t a substitute for project-specific property insurance for a renovation.
Read More: See What Ontario Requires From a General Contractor
Can I Get Renovation Insurance?
Builder’s risk, also called course-of-construction insurance, can help protect your home’s structure and building materials during a project. The homeowner, contractor or project owner may carry the policy. It depends on the insurer and what’s included in the contract.
Get a copy of the policy and find out who is a named insured, what’s covered, whether the existing structure is covered and when the policy expires.
Liability insurance is different. It covers responsibility for injuries or damage to other people’s property. It doesn’t cover correcting shoddy workmanship.
What Happens if I Move Out During Renovations?
Tell the insurer you’re leaving, when, why and when you’ll be returning. You should also have a plan for utilities, security, regular visits and whether contractors can enter the property.
When you move out, your insurer may treat the policy differently. Make sure you know the difference between vacancy and unoccupancy. Ask whether a vacancy permit or another endorsement is available, whether inspections are required, and whether you need to take specific precautions with water and heating.
Handling Unforeseen Hazards
Stop work if you think you have disturbed an asbestos-containing material. According to Health Canada, asbestos was widely used in buildings constructed before 1990. Have qualified professionals test materials that might contain asbestos before renovating, and have qualified professionals remove asbestos-containing materials.
Except where immediate action is necessary to protect life and property, document the condition with photographs before starting tear-out.
Read More: Read How Home Insurance Treats Mould
Renovations That May Reduce Risk, and May Not Reduce Premiums
Adding to your house, increasing rebuilding costs, increasing living area or increasing your liability could contribute to a higher premium.
Some upgrades can reduce losses and may reduce your premium, but a discount isn’t guaranteed. Ask what discount is available before upgrading solely to lower your insurance premium.
Upgrade Risk-Prone Systems
Upgrading an old or inadequate system such as the roof, electrical, plumbing or heating might improve eligibility or rating with some insurers. Keep documentation, including invoices, permits, inspections, product information and pictures showing completion.
Install Safety and Security Features
Some insurers offer discounts for monitored alarms, leak sensors, automatic water shutoff devices and sump-pump backups, but may have specific requirements for monitoring, installation and proof. Confirm what discounts are offered before investing in these items.
Read More: See How Home Security Systems May Affect Insurance
Protect Your Home From Natural Disasters
Match mitigation to the hazards. Backwater protection, grading, better roof attachments and fire-resistant building materials protect against different risks. Choose projects that address your specific hazards.