









Different types of water damage, such as a burst pipe, backup, flooding, or seeping into your home’s foundation, may be treated differently by insurers. Some may be included in your policy, others might not. Also, coverage may distinguish the item that failed, such as the pipe, from the resulting damage. Some events, such as certain kinds of floods, will require additional coverage that can be added on to your policy.
For this review, we consulted the Insurance Bureau of Canada’s flood-and-water guidance, Insurance Bureau of Canada’s home-coverage guide, the federal home-insurance guide, and General Insurance OmbudService’s claims guide.
Does Home Insurance Cover Water Leaks?
Water leak coverage can vary based on the source, cause, policy form and any available or purchased endorsements.
Home insurance often covers an accidental, sudden release of water from your home’s plumbing, air conditioning or heating system or an appliance. Often the cost to replace a burst pipe or broken appliance isn’t covered.
Seepage or repetitive leaks may not be covered or might require an additional coverage option (endorsement).
Groundwater, overland water and sewer backup might be excluded or available as an option; coastal flooding is typically excluded.
What Water Damage Does Home Insurance Cover?
| Water source | Typical starting point | Important distinction |
|---|---|---|
| Sudden indoor pipe or appliance escape | Home insurance commonly covers resulting water damage. | The failed item, such as a broken pipe, hose, seal, or appliance, may not be covered. |
| Toilet overflow | Whether or not home insurance will cover water damage depends on the source of the water and if there is a blockage involved. | An overflow from a fixture is not necessarily considered a sewer backup. |
| Sewer, drain or sump backup | Sewer backups might require optional sewer-backup coverage. | Policy wording indicates where the water comes from and how interaction with overland water will be treated. |
| River, heavy rain or surface water entering at ground level | Overland-water coverage may be available as an option. | Some types of water damage are covered by home insurance. Eligibility and coverage limitations vary by insurance policy. Some types of water damage, such as coastal/tidal water are excluded from coverage; exclusions vary by insurance policy. |
| Groundwater or water through a foundation | Coverage may be limited or not available. | Will my homeowner’s insurance cover water damage? It depends on whether it’s a sudden event or continuous seeping. |
| Rain through a damaged roof | Water damage to a home’s interior may be covered by home insurance if it’s the result of a sudden, covered event. | Repairs relating to maintenance and worn-out roofs may not be covered. It depends on the source and nature of the damage. |
| Frozen pipe | It may be covered by home insurance if the precautions laid out in your contract have been followed. | Different home insurance policies have different absence and heating requirements. Please check the terms of your own insurance policy. |
Water can come from a unit upstairs, a common pipe, your roof, or even from the ground and produce the same stained ceiling. Where the water originated, not where it landed, determines what property or liability insurance is implicated.
Five Separate Questions In A Water Claim
| Question | Example |
|---|---|
| Is the cause insured? | A sudden pipe rupture may be insured; repeated seepage is commonly excluded. |
| Is the failed item insured? | Example: Flooring damaged by water may be covered, but a worn-out dishwasher hose may not. |
| Is resulting damage insured? | Drywall, cabinets, electrical work and contents may all be involved in a water claim. |
| Are mould and cleanup insured? | Depends on cause, timing, mitigation and wording |
| Are living expenses insured? | Typically in order to be eligible for additional living expenses, an insured loss needs to exist. Coverage, if approved, would be subject to the terms and conditions of the applicable insurance policy(ies). |
How Water Protection Can Affect The Premium
Our analysis of thousands of home insurance quotes collected through the MyChoice platform since the beginning of 2026 found the share of yearly premiums attributable to enhanced water protection ranged from $83 out of a $2,779 annual premium, or 3.0%, in Calgary to $562 out of $2,990 (18.8%) in Sudbury. For example, in Toronto, enhanced water protection accounted for $409 out of the annual premium of $2,247, representing 18.2% of the premium.
Do not add those median amounts to a city premium, as insurers package coverage in different ways. Ask for pricing on water protection in your home insurance policy. For those that provide a breakdown on the price for specific add-ons, the median yearly price is $129 for sewer-backup protection, and $100 for overland-water protection. Check coverage limits and deductibles too.
Does Home Insurance Cover Plumbing Issues?
Ask the adjuster to break out the costs for opening the walls, fixing the problem, drying out the structure, testing, dealing with any mould, rebuilding, and replacing damaged contents.
Insurers may well pay the cost of dealing with resulting water damage and not pay for defective fixtures or plumbing maintenance. One line item being declined does not mean the whole claim is denied.
Read More: See How Sewer-Backup Coverage Differs From a Plumbing Leak
Does Home Insurance Cover Flood Damage?
Not all insurers define a flooded room in the same way. It’s important to know what’s covered and what’s not.
Check to see if water coming into your home through foundations, doorways, windows, drains, and sump systems is covered. Sewer backup and overland-water (freshwater) coverage may be available as an endorsement. Some insurers offer the two together, others will write them individually. Damage from coastal flooding, tidal water, and storm surge is commonly excluded.
Read More: See How Overland-Water and Flood Coverage Work
Does Home Insurance Cover Seepage Damage?
It’s important that you report any damage that you think is covered as soon as possible. Insurers will then be able to consider your claim in light of the wording of your policy and any other supporting evidence.
It’s not necessarily the case that damage or mould behind a wall is covered simply because it’s hidden. Many insurance policies exclude repeated or continuous leakage and seepage.
Does My Tenant Insurance Cover Water Damage?
In the case of water damage, notify your insurer as well as the property manager. Although coverage can vary by insurer, your tenant’s insurance may cover insured damage to your belongings, additional living expenses after an insured loss, and your liability for accidentally damaging the building or a neighbour’s unit.
Note that landlords or condo corporations insure different parts of the property. Don’t assume that one or the other’s insurance will cover everything.
Read More: Review Water-Damage Coverage for Tenants
How To Get Insurance To Pay For Water Damage
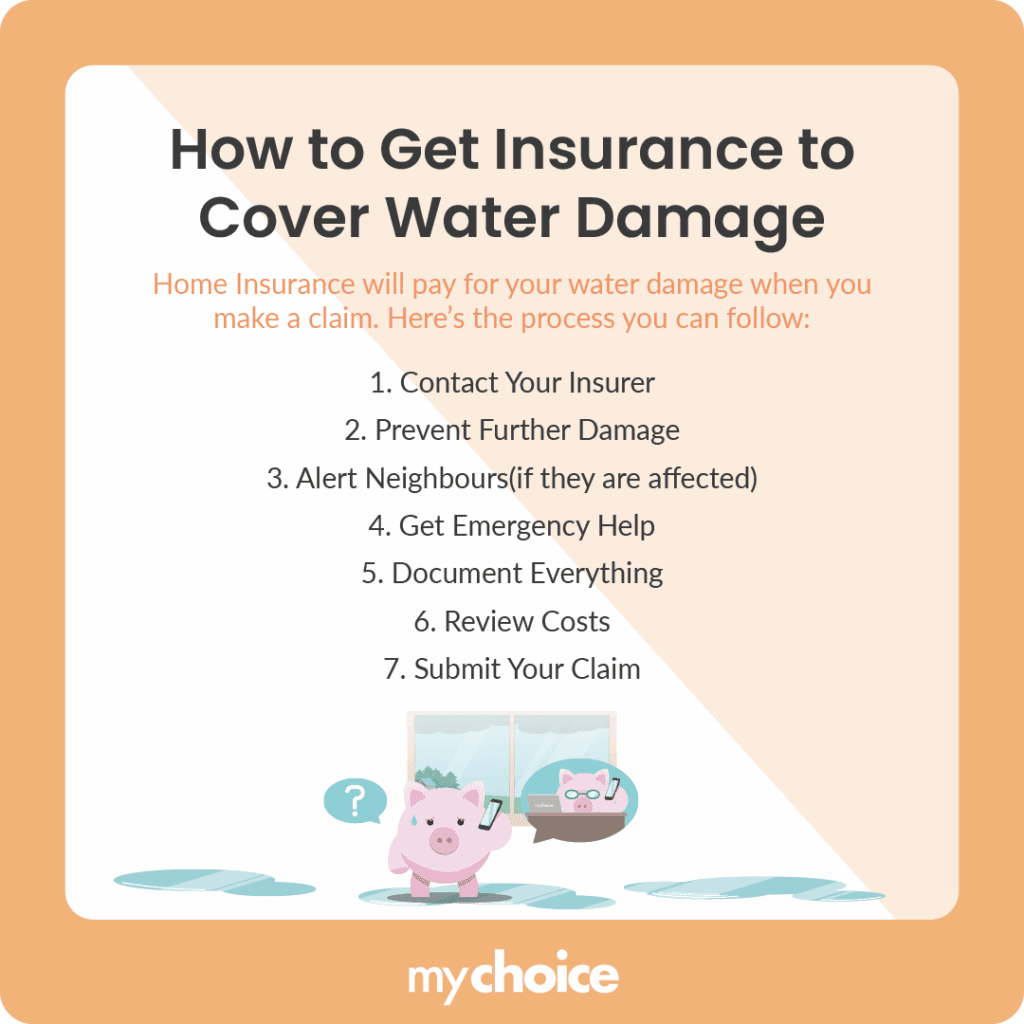
Here are some tips that can help you support an insurance claim for water damage.
- Stop the source of the water if it’s safe to do so, such as at the shut-off valve or main line.
- Shut off electricity to affected areas from a dry and safe location.
- Notify your insurer/broker as soon as possible, and ask about emergency drying, approved vendors, the deductible and any spending authorization.
- Take photos of water source, water’s travel route, affected rooms and possessions before moving or removing anything.
- Take reasonable steps to prevent further damage.
- Keep failed hoses/valves/equipment unless your insurer advises otherwise.
- Do not remove building materials on a large scale and do not carry out any permanent repairs before the insurer has had a chance to view the loss, except when necessary for safety reasons.
- Keep records of all telephone calls including name, date, time, and discussion, inventories by room, moisture content records, plumber’s report, drying-out/restoration reports, repair estimates, receipts.
If your insurance claim for water damage is refused either in part or in full, ask for written information on the reason for refusal, including the facts, calculations and policy clause.
If you’re not happy with the solution, complain through the insurer’s internal process then proceed to General Insurance OmbudService or seek professional advice.
Check These Policy Terms Before A Leak
| Term | What to confirm |
|---|---|
| Sewer backup | Definition, limit, deductible and interaction with overland water |
| Overland water | Eligibility, covered entry routes, exclusions, waiting period |
| Freezing and absence | What is required of you in relation to heating? Shutoff? Draining? How frequently should you arrange an inspection? Check your policy for an idea of what’s required. |
| Mould and repeated leakage | Policy terms contain exclusions, and may offer limited coverage for remediation. Check before you need it. |
| Additional living expenses | Find out when your policy is triggered, any time or dollar limitations, and whether the pre-approval process applies. |
| Condo or tenant responsibilities | Consider the property insurance (including deductibles) of the corporation, landlord, unit-owner and/or tenant. |
How To Reduce The Risk
Reduce the likelihood of water damage with good housekeeping
Replace worn-out hoses on appliances. Repair leaks and deficiencies with roofs, plumbing, grading, foundations, etc. Know where the main shutoff is on your water. Follow manufacturer and municipal instructions to maintain sump pumps, backwater valves, drains, alarms, etc. Store electrical equipment and valuables above known basement flood levels. Before leaving in winter, follow your policy’s exact requirements for maintaining heat, shutting off water and inspections.
Read More: See How Sump Pumps Can Reduce Basement-Water Risk