
The right property policy depends mainly on who occupies the home, how often it is rented and what income, contents and liability you need to protect. To prepare this guide, our editorial team reviewed the Financial Consumer Agency of Canada’s home-insurance guide, the Insurance Bureau of Canada’s room-rental guidance, IBC’s guide to home coverage, and the Canada Revenue Agency’s rental-expense guidance.
Keep reading to learn when owner-occupied home insurance, landlord coverage or a rental endorsement may fit, which limits and exclusions to compare, and how mixed, vacant and short-term use change the questions.
Do You Need Landlord Insurance or Home Insurance?
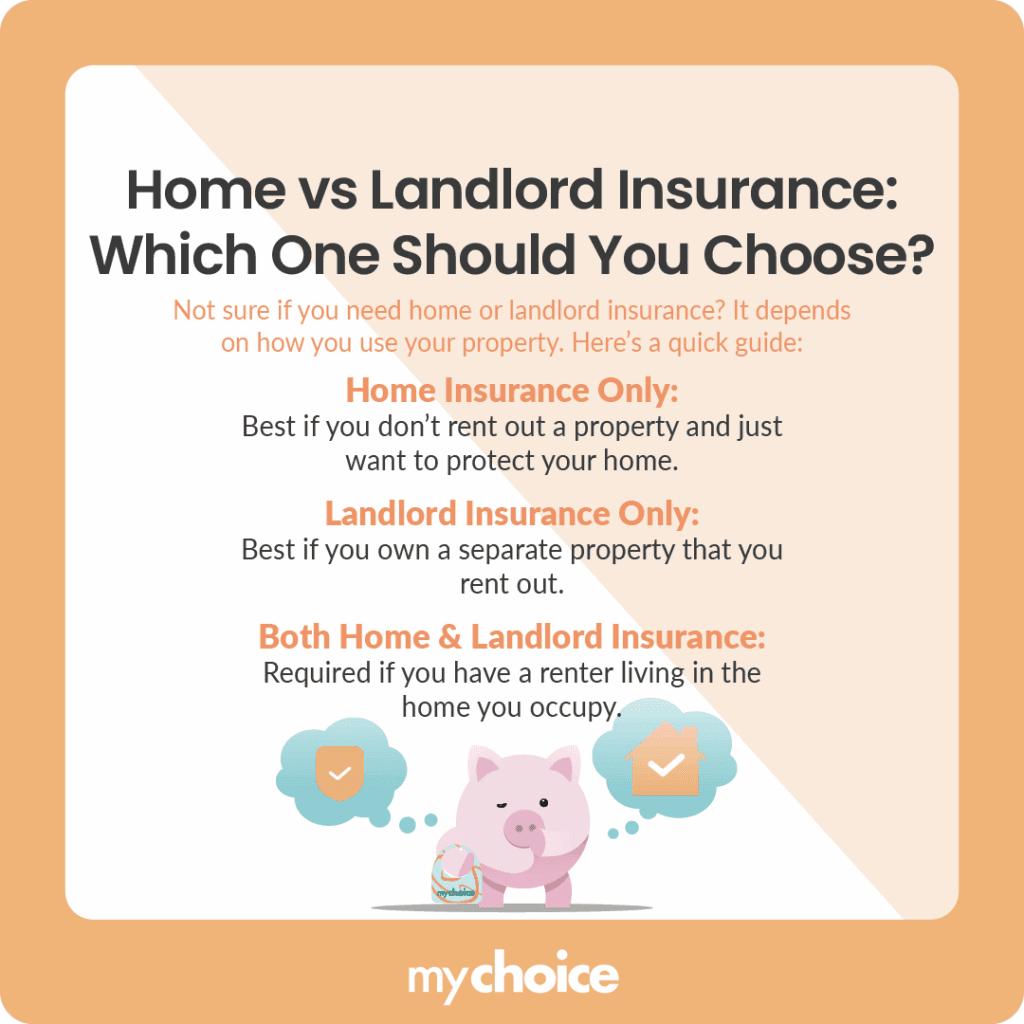
If tenants occupy the dwelling, you may need landlord/rented dwelling insurance. If you occupy the dwelling, you’ll want an owner-occupied home insurance policy, as long as the insurance provider will accept the dwelling as a primary or secondary residence.
If you own a home that is owner-occupied but you have a tenant staying with you, or if you rent out your house, a unit, or a room on occasion, you should alert your insurance company before the tenant(s) move in. You may not need two different policies. Some insurance companies will offer an endorsement or terms to cover this circumstance.
Have the insurance company put the accepted occupancy in writing, including the rental frequency and what portion of the dwelling is covered.
Landlord Insurance vs Home Insurance: Key Differences
| Owner-occupied home policy | Landlord or rented-dwelling policy | Tenant’s personal belongings | |
|---|---|---|---|
| Building | Protects a dwelling in which its owner lives | Covers the rental building | Does not insure the landlord’s building |
| Contents | Owner’s personal belongings, subject to limits | Only landlord-owned appliances, furnishings or equipment, if included | Tenant’s belongings |
| Liability | Owner’s personal liability under the policy | Premises or landlord liability under the policy | Tenant’s personal liability under the policy |
| Living or rental income | After a covered loss, additional living expenses coverage may apply | May include lost rental income after a covered loss, with limits and period | May include additional living expenses after a covered loss |
| Main disclosure | Any tenant, room rental, home sharing or change in occupancy | Tenant type, lease, units, vacancy, property management and rental pattern | Occupants, belongings, liability exposures and unit |
Coverage Checklist for a Rental Property
If you are renting out your property, you should review the items below and double-check your policy to ensure you are covered for them.
- Key terms: Replacement cost, actual cash value, limits, co-insurance, inflation and building-code increases in the cost to rebuild.
- Contents owned by the landlord: Furnished rental units, appliances, maintenance items, tools, other items used to manage and maintain the rental property, stored belongings and outdoor property.
- Loss of rental income: Insured loss, waiting period, total limit, length of benefit, variable rents and seasonal rents.
- Damage by tenants: Accidental or wilful damage, gradual deterioration or neglect, vandalism and theft. What constitutes sufficient proof of damage?
- Liability: Bodily injury to others on the premises, contractors or property managers working on the premises, legal expenses, swimming pools and pets.
- Catastrophe and water coverage options: Sewer backup, overland water, service lines and earthquakes. Check for separate deductibles and limits.
- Other risk factors: Types of tenants, lease terms, number of rental units, frequency of inspections, vacancy, remodelling and short-term rentals.
Read More: Read the Guide to Renting a Basement Apartment
Special Situations Canadians Often Overlook
No single endorsement covers all situations, such as short-term rental, room rental or home sharing. Ask about night limits, minimum lease duration, excluded rental platforms, whether the policyholder must be present during the rental period, whether a commercial endorsement is required and the liability deductible. Ask whether you can use the home when it’s not being rented.
With a multi-unit property, tell the insurer how many units you’re legally allowed to have, how many you actually have, whether they have separate entrances and cooking facilities, and how they are occupied. Getting coverage doesn’t mean you comply with zoning, fire or tenancy laws.
Tax and Mortgage Considerations
Landlord insurance may not be required by law, but your mortgage lender may require the property to be insured and may require you to disclose its rental status. Read the mortgage contract before renting out the property or cancelling insurance.
According to the CRA, insurance premiums paid in a taxation year are deductible against the rental income for the year. Any premiums paid in advance must be spread over the years they cover. Deductions differ if you use the property personally, make capital improvements, etc. Keep invoices and speak to your accountant.
Tenant Insurance: Filling the Gap
Depending on the rules in your province and your lease, you may be able to require your tenants to have tenant insurance. Any requirements should clearly define minimum liability amounts and ways to prove coverage. Be sure to apply these rules consistently. It’s a good idea to have a lawyer help you prepare any insurance-related clauses in your lease.
Tenant insurance won’t always cover all your losses.
A landlord policy doesn’t cover tenants’ belongings or liability. A tenant policy may cover tenants’ personal property, liability, and the cost of temporary living arrangements if they experience a covered loss.