









Whether you need life insurance doesn’t hinge on your marital status but instead on whether there would be a shortfall in finances if you died. For example, would your estate, business, or another person be better off with life insurance because their financial obligations would outweigh assets?
For this guide, our editorial team used the Financial Consumer Agency of Canada’s life-insurance guide, FSRA’s explanation of life-insurance policy types, Statistics Canada’s 2021 census analysis of people living alone, and the Government of Canada’s estate and wills guide.
Do Singles Need Life Insurance?
You may not need life insurance if your death would not create financial hardship for anyone. It doesn’t matter if you’re single, young, or have a mortgage. However, it’s a good idea to get life insurance if:
- Someone depends on your income or the care you provide for free.
- You help pay bills.
- There’s a co-signer or joint borrower on your debt.
- There is not enough cash in your estate to pay expected expenses.
- You want to leave a gift to charity or pass on a business when you die.
Use This Needs Test Before Buying
| Situation | Possible financial loss | What to check first |
|---|---|---|
| You support a parent, sibling or another person | Consider the money or uncompensated care that would be lost. | Amount, monthly need, support period and assets already available |
| You share or guarantee debt | Some purchases involve other people being liable for payment, such as a co-borrower, guarantor or estate. | Contract, ownership, balance and who remains legally responsible |
| You own a business | Debt, succession, buyout or key-person cost | Review shareholder, loan and buy-sell documents, and evaluate personal and business needs separately. |
| You want final-expense or estate liquidity | Before liquidating assets, the estate may require liquid funds. | Liquid estate assets, expected expenses and provincial estate process |
| You want to provide for a pet or charity | Legacy is a choice, not income replacement. | Confirm beneficiary, trustee or estate instructions, and obtain legal advice where needed. |
| Nobody relies on you and liquid assets are sufficient | No clear uninsured loss | Savings and an up-to-date will may resolve the need without a policy. |
Read More: Review Reasons Not to Buy Life Insurance
Why Should Singles Get Life Insurance?
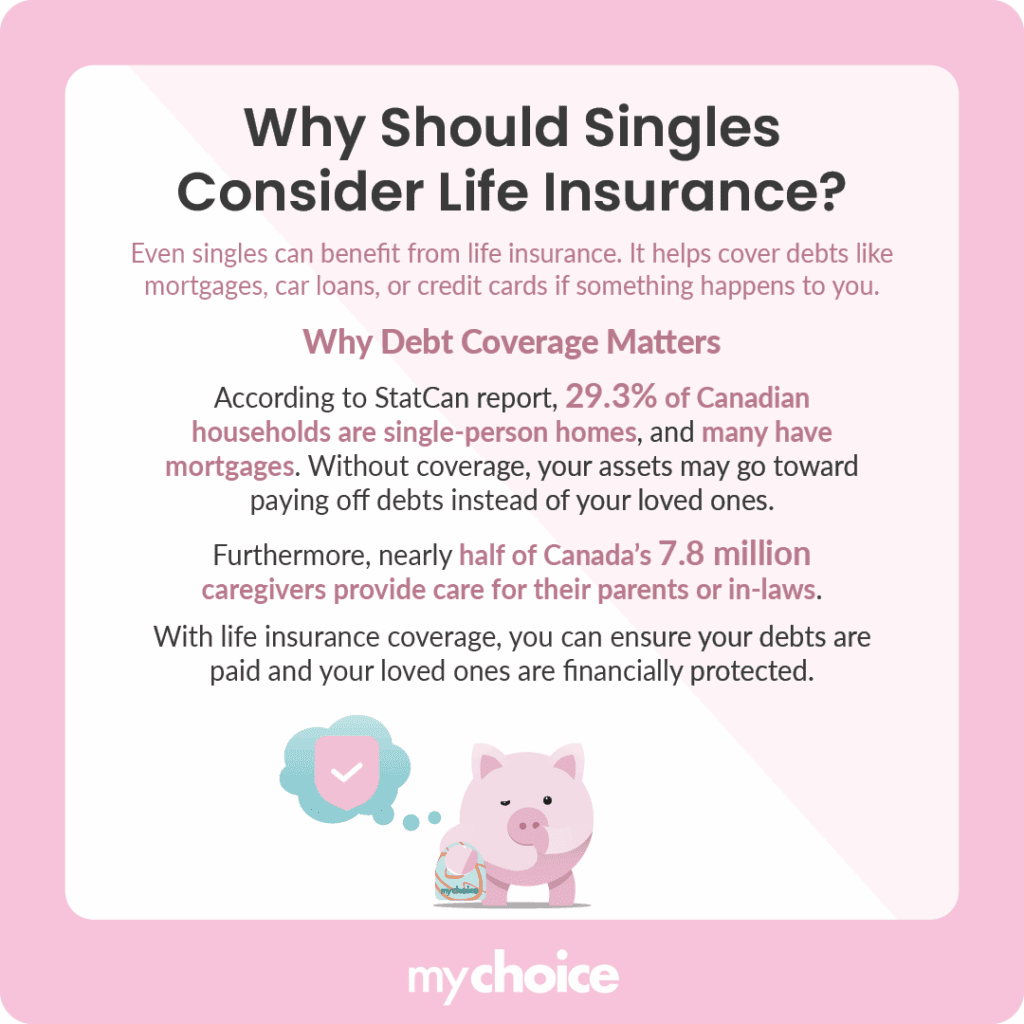
Contrary to what you may think, someone who lives alone may still have many responsibilities. According to Statistics Canada, 29.3% of Canadian households were one-person households in 2021. Chances are, many of these solo dwellers help financially support their aging parents or provide invaluable, though not financially compensated, family care.
Read More: Read Why Life Insurance Can Be Important
When Permanent Insurance May Have a Role
Term insurance makes sense when you have a temporary insurance need, such as paying off a mortgage, business financing or providing financial support for children. By definition, term insurance does not last a lifetime. Its initial cost is often lower.
Cash value should not automatically make permanent insurance a good investment. Factors to consider include:
- Guaranteed and current cash values.
- Costs and surrender charges.
- Interest charged on policy loans.
- How much of the death benefit will be available after policy adjustments and loans.
- Tax considerations.
Read More: Read Whether Whole Life Insurance Is a Good Investment
What Type of Policy Makes Sense If You’re Single?
As a single person, your insurance needs may differ from those of individuals with a spouse or children. The table below offers a comparison between the three most common types of life insurance and their unique values:
| Policy type | Strengths |
|---|---|
| Term life insurance | Affordable, adjustable coverage period |
| Whole life insurance | Cash value component, stable growth, lifelong coverage |
| Universal life insurance | Lifelong coverage, choice in investment methods, flexible premiums |
Read More: Compare Term and Whole Life Insurance