









During our editorial review, we researched the federal life insurance guide, FSRA’s life-insurance policy guide, the Autorité des marchés financiers’ term-insurance guide, and the IFRS Foundation’s description of IFRS 17.
Why is my life insurance premium going up? Your insurance may be going up for several reasons, which may or may not relate to higher insurance rates in Canada. More likely, a contract provision is behind it, such as a scheduled term renewal, a policy or rider change, group-plan repricing, or funding pressure in an interest-sensitive policy.
This article explains how to determine why your life insurance rates are going up, how to find out if increases are predetermined, how to compare new life insurance rates with your current policy, and what your options are if you want to replace or convert your policy or reduce your coverage.
Why Did My Life Insurance Premium Increase?
If the premium went up, check your policy type and effective date. A policy with a guaranteed level premium should remain as stated during the stated guaranteed period. A renewable term policy can increase when the term expires but often doesn’t require new medical evidence.
When you apply for new coverage, premiums are based on your current age, health, and the type of coverage you choose. Group policies and universal-life coverage work differently.
For example, the insurer can’t raise your individual premium based on a recent diagnosis or its own claims experience during the policy’s guaranteed period. Ask which rider, payment change or other provision, such as the renewal schedule or another policy transaction, increased your premium.
Which Premium Changed?
| Situation | Why the amount may change | First document to check |
|---|---|---|
| Level term, still inside the initial term | Changes to your policy, adding riders, payment options or even a billing error could be the cause of the change, not necessarily because you’re getting older. | Policy schedule and latest notice |
| Term reaching renewal | The amount may change at renewal because the contract’s guaranteed renewal schedule reflects an older attained age and renewal without new evidence. | Renewal-rate table and conversion deadline |
| New or replacement application | Age, smoking status and health; Occupation; Personal activities; Amount of cover; Term of policy and Underwriting class can affect the amount. | Issued illustration and rating decision |
| Whole life or other level permanent policy | Even when premiums are guaranteed, dividends, optional deposits, riders, or changes in the length of the payment period may cause changes in cash flows. | Guaranteed values, dividend option and rider pages |
| Universal or interest-sensitive policy | Even with the guaranteed contractual charge, changes in investment results or cost-of-insurance charges could result in the planned deposit being insufficient. | Annual statement and low-return in-force illustration |
| Employer or association group plan | The amount may change due to a change in the master contract, experience of the Group, benefit design, or employer subsidy. | Employee certificate and renewal notice |
Read More: Compare Renewable and Convertible Term Life Insurance
Scheduled Term Renewal
Term life insurance can be issued for specific term lengths such as 10, 20 or 30 years, and premiums are usually level during the original term. For policies that can be renewed, the original contract often lists renewal premiums. Renewal premiums are higher because coverage continues at an older age without a new health assessment.
AMF says it may be less costly to purchase a new contract than to pay higher renewal premiums on a term policy. However, you may not qualify for a new contract if your health has changed. If you can buy a new policy, its terms may differ from your current contract. For example, the contract period may restart. Until you are certain you have a comparable replacement policy that has been issued, accepted, and fully compared, continue with your existing contract.
Read More: See What to Do When Term Life Insurance Is Expiring
Major Contributors To Premium Increases
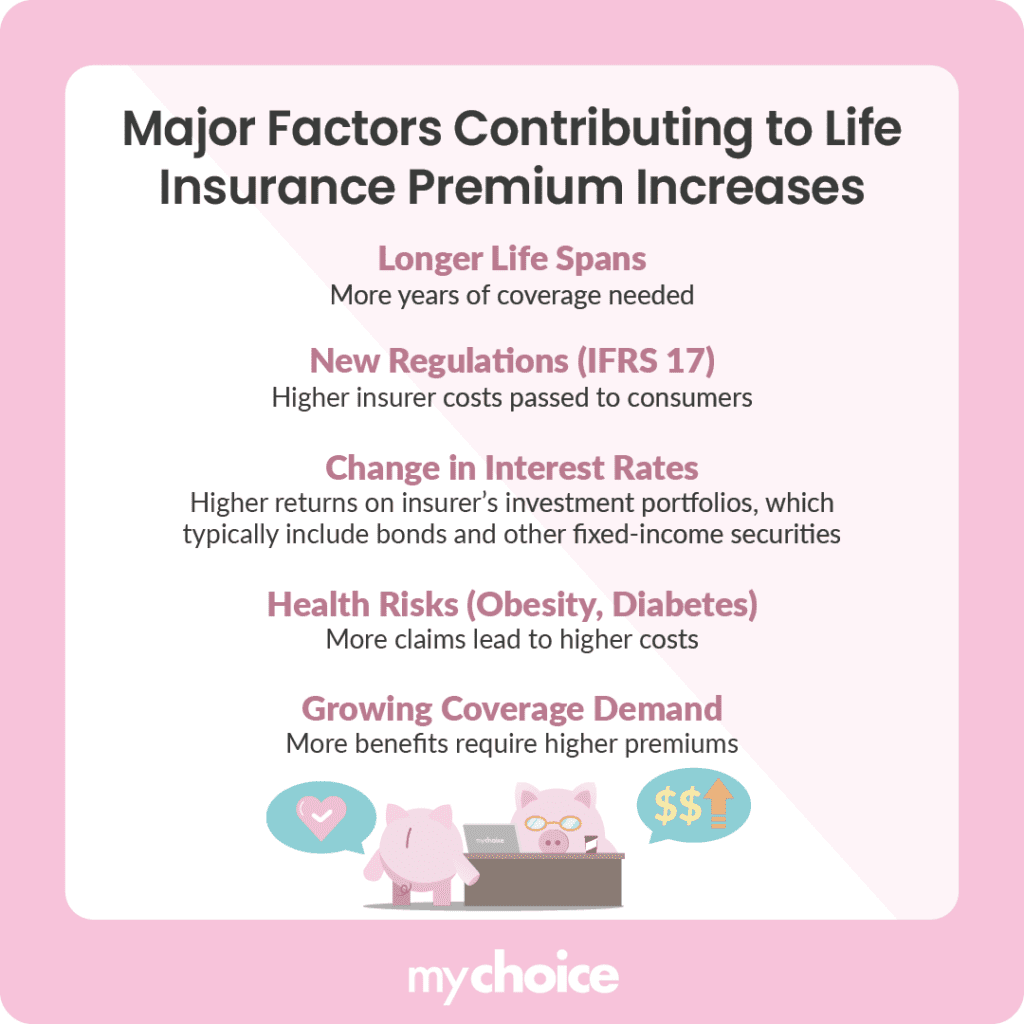
These factors apply to new applications, product pricing, interest-sensitive policies or group plans; they do not all change a guaranteed in-force premium.
- Older attained age at application or renewal, as payment schedules for terms increase with attained age.
- More expensive coverage, such as a bigger death benefit, longer initial term, permanent guarantee, or additional riders.
- Limited-pay products have a different payment schedule from products that require premiums for a lifetime. Payment frequency: monthly payment amounts will not equal annual premium costs.
- For group insurance, increases are less likely to be a result of individual health concerns and more likely the result of an increase in group rates, plan changes, or a decrease in employer subsidy.
How Interest Rates Impact Insurance Coverage Costs
Universal life policies separate the cost-of-insurance charge from the amount you choose or need to deposit. So, a planned deposit is not necessarily a guaranteed premium.
Ask for an in-force illustration of your policy. Analyze the illustration under the guaranteed assumptions and under at least one set of low-return assumptions.
Insurers invest your premiums to support their long-term obligations. Lower expected returns can make new long-term guarantees more expensive.
What To Do Before Accepting The Increase
- Ask for a written explanation of the increase. It should include the former and new premiums; the effective date; the contract clause; and the full future premium schedule. Distinguish guaranteed parts of your policy from any optional deposits. Be aware of costs of riders (additional coverages). Understand that any illustrations of dividends and/or future cash values are not guarantees.
- Decide how much coverage you really need. Review your debts; income-replacement needs; support for any dependants; children’s education costs; final expenses; and business-related needs. Consider any existing assets. Make sure you have the right amount of coverage.
Read More: See When to Review Your Life Insurance Coverage
Questions To Ask The Insurer Or Agent
- Is my policy being adjusted/renewed (contractually speaking), quoted as a new policy (new business), being adjusted via a rider, repriced as part of a group, or am I receiving an optional funding recommendation?
- Are any of the premium amounts guaranteed? Which ones? For every future year shown in the contract?
- Can my policy be converted? Can I convert without new medical evidence? What is the exact deadline? What types of policies can it be converted into?