









Term does not necessarily mean that the policy terminates on expiry. Depending on the contract terms, it may renew at a predetermined rate, require a decision on whether to continue it, or expire permanently. Conversion rights may end before the policy expires.
To prepare this guide, our editorial team reviewed the federal life insurance guide, the federal guide to getting insurance, the Autorité des marchés financiers’ term insurance guide, and the Canadian Council of Insurance Regulators’ replacement declaration.
What Should You Do When Term Life Insurance Is Expiring?
Verify that you understand your contract. Locate the following items: the term end date; renewal provision, which should include a premium schedule; conversion deadline, if applicable; and the expiry age.
Reconsider how much coverage is needed and for how much longer. Review the premiums for the guaranteed renewal, as they’re likely in the same schedule or determined by a formula already in your contract, but keep in mind you may have other options.
Compare the guaranteed renewal to your right to convert and other options based on an underwritten application before deciding to cancel your term life insurance. If your right to convert ends before the general term end date, this should be done before that earlier date.
What Happens When Your Term Life Insurance Expires?
| Date or event | What it controls | Action |
|---|---|---|
| Conversion deadline | The last date to request an eligible permanent policy without new health evidence | Ask to see the current menu of products, rules for choosing the amount of insurance and illustrations before the deadline. |
| Current term end | The end of the current level-premium period | Check whether the policy expires, automatically renews or requires advance notice. |
| Renewal payment | Your next payment will be at the renewal rate | Check the amount and cancellation instructions before the payment date. |
| Final expiry or maximum renewal age | The date after which contractual renewal is no longer available | If you anticipate having an ongoing insurance need, plan before this date. |
| New policy effective date | When replacement coverage actually begins under its conditions | Keep the existing policy until the new contract is in force and accepted. |
Main Options You Have When Your Term Life Insurance Expires
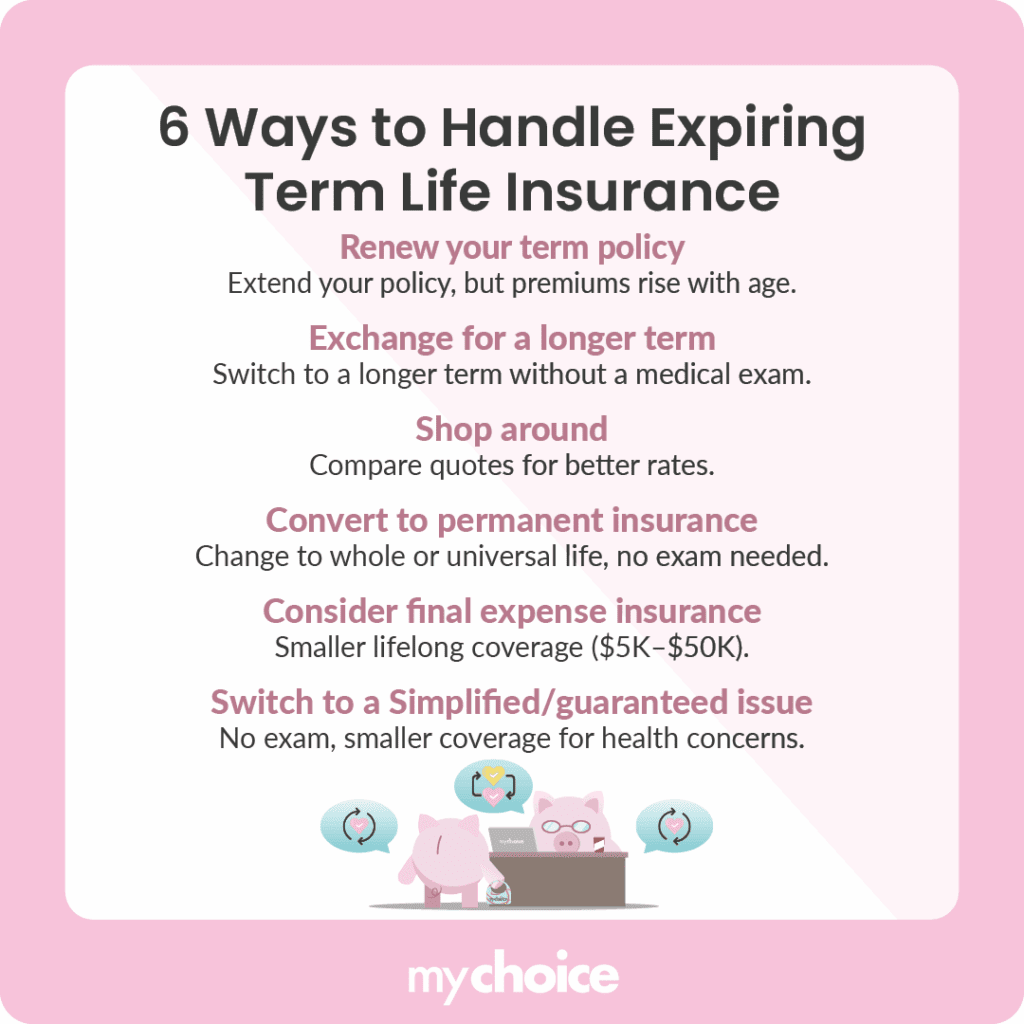
| Option | What it does | Key limit or safeguard |
|---|---|---|
| Use contractual renewal | Continues term coverage for the period stated in the policy without new health evidence | Read every scheduled renewal premium, the final expiry and any change in amount or riders. |
| Apply for a new term policy | Starts a new policy with a new term that’s subject to current underwriting | Receiving a quote is not the same as being approved. Your offer may differ in price, coverage amount or approval. |
| Convert to permanent insurance | If eligible, you may be able to convert your term policy to a permitted type of permanent insurance without submitting new evidence of insurability | Check the conversion deadline, eligible products and amount. |
| Make a partial conversion | You may be allowed to convert a portion of the insurance amount, depending on your insurer’s rules and contract | Check the minimum amount and what happens to the remaining term coverage. |
| Use an exchange or term-to-term option | Some insurers let you change your current policy for a longer term without a medical exam | This is not universal. Check age, duration, timing, amount and underwriting rules. |
| Reduce or let coverage end | Matches a smaller or finished insurance need | Confirm cancellation or non-renewal instructions so an automatic premium is not taken. |
Read More: Compare Renewable and Convertible Term Life Insurance
Partial Conversions
Suppose that part of your needs is permanent and the remainder expires at the end of the term. For example, suppose that you have $500,000 of expiring term coverage but only a $150,000 estate need that’s permanent. You could use the balance of the death benefit for mortgage needs that expire in a few years.
Ask: Can I convert only a portion of the total death benefit? What happens to the remaining death benefit? Will it expire, renew or remain convertible?
A partial conversion may be available if the policy and insurer’s rules allow it.
Read More: See How Term Life Differs From Whole Life
What Happens If You Do Nothing?
Inaction could result in termination or automatic renewal for one year or another period. Some policies require an affirmative election to renew. With automatic renewal, the insurer may collect the scheduled premium even if the consumer intends to cancel. If the policy expires, the beneficiary won’t receive a death benefit for a death after expiration.
Compare the Options on One Page
| Input | Renew existing | Convert | New application |
|---|---|---|---|
| Coverage amount | Amount after renewal | Amount eligible for conversion | Amount approved after underwriting |
| Duration | Renewal period and final expiry | Permanent while contract requirements are met | Chosen term or permanent form if approved |
| Premium | Full guaranteed renewal schedule | Current illustration and guarantees | Issued premium and guarantees |
| Health evidence | Normally none for the contract right | Normally none for the contract right | Current underwriting applies |
| Riders and exclusions | What continues or ends | What carries over or changes | New contract terms and periods |
| Deadline | Notice and payment date | Conversion deadline | Application, approval and effective date |
Read More: Explore Term Life Insurance Options
Replacement Safeguards
- Keep paying the existing premium while the insurer reviews the new application, unless it confirms another arrangement in writing.
- Do not cancel the existing policy until the new policy is issued, in force and accepted.
- Compare benefits under the old and the new policies, including death benefit, premium guarantees, riders, exclusions, contestability clauses, suicide clauses, policy ownership and beneficiary designation. Look over your new policy carefully during its review period.
Read More: Use the Life Insurance Coverage Review Guide