









Some term policies are renewable or convertible; some are both. To learn about these important policy privileges, our editorial team looked to the federal life insurance guide, the federal guide to getting insurance, the Autorité des marchés financiers’ term insurance guide, and FSRA’s policy-reading checklist.
Renewal extends term coverage under the contract’s renewal schedule. Conversion lets you exchange eligible term insurance for certain permitted permanent insurance offered by your insurance company. Renewal and conversion privileges on an existing term insurance policy are different from a new insurance policy issued after new underwriting. Check your policy to learn more about renewal and conversion privileges.
Renewable and Convertible Life Insurance: What Makes Them Different?
| Feature | Renewal | Conversion |
|---|---|---|
| Result | The policy continues for another renewal period, as outlined in the contract. | Convertible life insurance allows qualifying term life insurance to be converted into an eligible permanent life insurance policy. |
| New health evidence | New health evidence is usually not required when the contractual renewal right is used. | Usually, new health evidence is not required if the contractual right to convert the policy is exercised. |
| Premium basis | The guaranteed renewal rate or schedule appears in the contract, commonly increasing at attained ages. | The permanent product, converted amount, age and conversion terms that apply. |
| Coverage length | Coverage continues for an additional term or renews annually, up to a specified age or policy expiry. | Provided all mandatory premium payments and policy conditions are met, permanent coverage stays in effect. |
| Product choice | The policy controls the renewal period and amount; you may not be able to choose a new term. | Product choice will vary based on the conversion menu provided by your insurer. |
Pros and Cons of Renewable Life Insurance
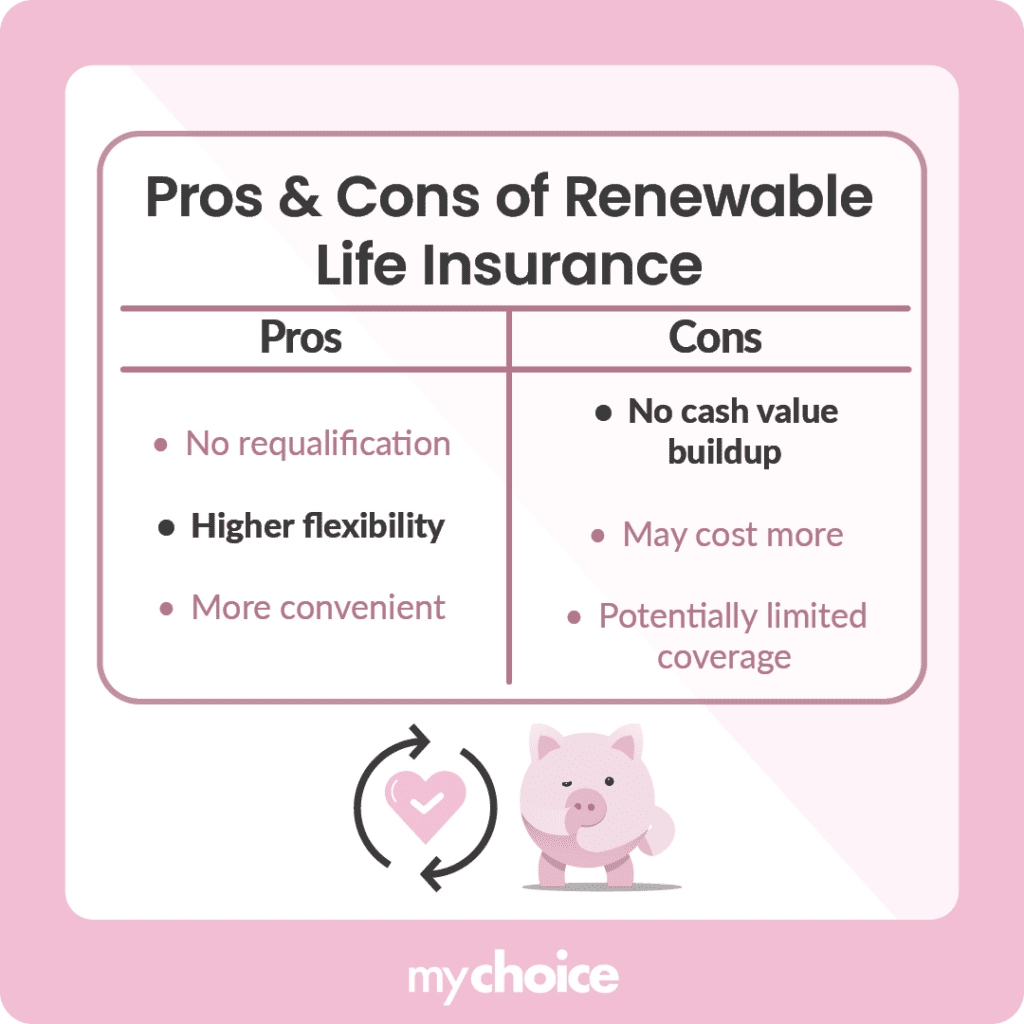
Renewable life insurance allows the policyholder the option to renew the policy at the end of the level-premium term. This may be desirable if the insured’s health has deteriorated or if they simply need coverage for the time being.
The biggest drawback of renewable life insurance is that renewal rates are often much higher than the original premium. Be sure to check your policy’s entire rate schedule before agreeing to coverage. Also, read the contract carefully to find out:
- Whether your policy renews every year or for some other time frame
- When your policy will expire, or the maximum renewal age
- Whether the death benefit changes with increasing ages
- Whether riders are renewed, and whether their terms change
In general, a renewable policy can be valuable for people who are unsure of their future insurability. Renewals may occur automatically or after notice from the policyholder.
If you are satisfied with your policy’s terms and your health is good, you might save money by shopping around and applying for a new term policy. Keep in mind that applying for a new policy isn’t the same as “requalifying” for your current policy. Your rate may not match your initial quotes, and your policy is considered a completely new contract.
Pros and Cons of Convertible Life Insurance
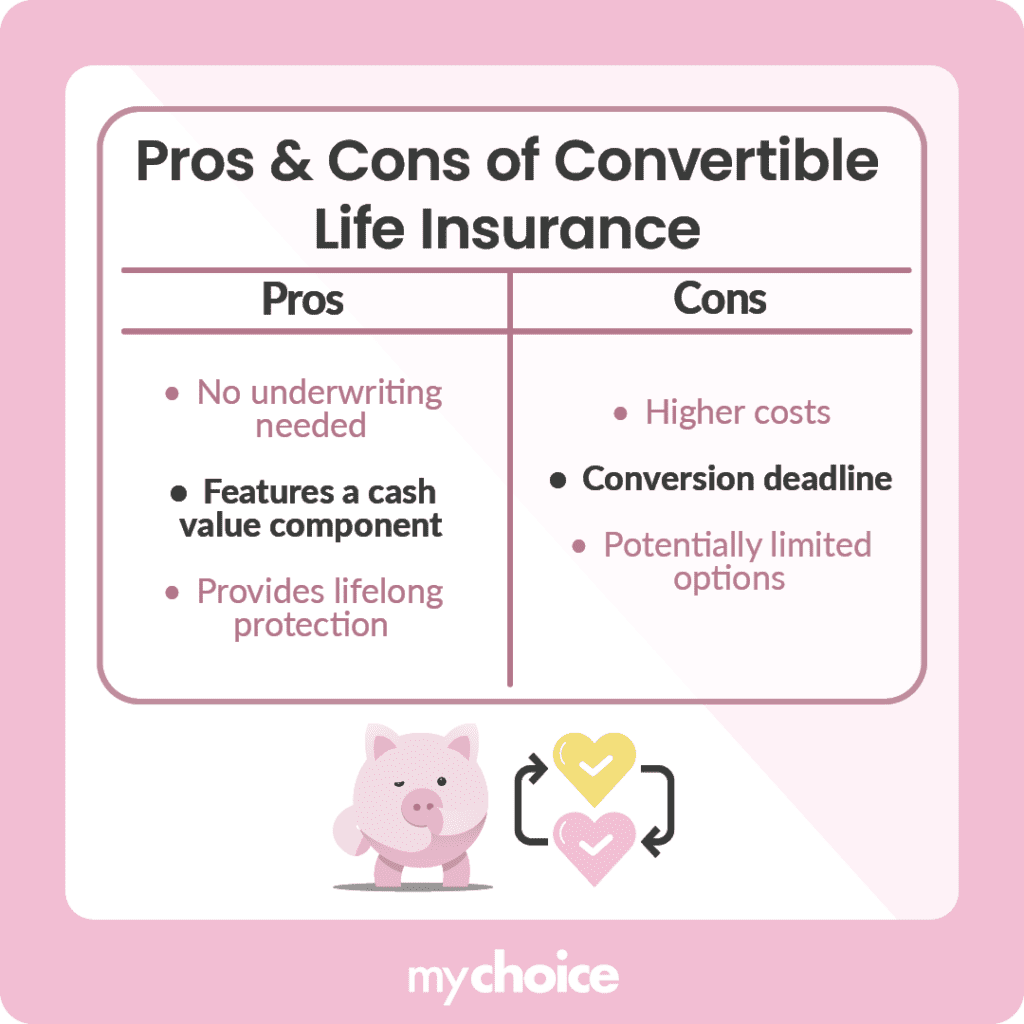
Conversion lets you keep coverage when passing a new evaluation may be difficult. However, conversion does not mean that:
- You can convert to all types of insurance.
- The converted coverage will have the same riders as the term insurance.
- The converted coverage will be the best rate.
- It is advantageous to convert.
When considering conversion, keep in mind:
- The type or types of coverage that may be obtained by conversion.
- Whether there is a time limit for conversion; it may be tied to a certain age, policy anniversary, or other stated date before the term expires.
- The amount of coverage that can be converted and whether partial conversion is allowed.
- Whether your rating class and smoker/non-smoker classification will remain the same. Some companies offer conversion credits. Don’t assume you will keep the same rate or receive a conversion credit. Check with the insurance company.
- Whether riders, ownership and beneficiary designation carry over or new forms are needed.
- How much the premiums will be and performance details, such as cash values and death benefits, about the new coverage. Review a policy illustration. Be sure to look at guaranteed as well as non-guaranteed values.
Applying for a Newly Underwritten Policy
Another option is to apply for a new term or permanent life insurance policy through your current insurer or a new one. Applying for a new life insurance policy can be useful if you’re looking for a policy that lasts longer or shorter, has a larger or smaller benefit, or simply costs more or less. Keep in mind, though, that you’ll need to qualify for coverage under current underwriting guidelines.
Before cancelling your existing policy, compare effective dates, guaranteed rates, death benefits, riders, exclusions, contestability, suicide clauses, etc. Do not cancel your policy until you’re issued your new policy—receiving a quote is not the same as being issued one.
Read More: Read What to Do When Term Life Insurance Expires
Read These Fields in Your Policy
| Field | What to record |
|---|---|
| Initial term end | The last day of the current level-premium period |
| Renewal schedule | Each renewal premium, renewal period, maximum age and any benefit reduction |
| Conversion deadline | The date or policy age when your right to convert without new evidence ends |
| Eligible amount | Find out if all of the death benefit can be converted or just some. Is there a minimum amount? |
| Conversion products | Which permanent products are offered |
| Riders | Whether optional benefits will continue terminate or require individual approval |
| Notice and forms | Check the policy to see who should receive the instructions, what signatures are required and the effective date and time of your request. |
Read More: Compare Term and Whole Life Insurance
Converting vs Renewing My Life Insurance: Which Should I Do?
| Situation | Option to investigate first | Reason |
|---|---|---|
| Short remaining need and health has worsened | Renewal | It can bridge the need without new health evidence, if the scheduled cost is affordable. |
| Lifelong estate, tax or dependant need | Conversion | Conversion is useful for obtaining permanent life insurance without submitting evidence of insurability. |
| Good health and a long temporary need | Newly underwritten term | A new policy may have a more appealing level-premium period, but there’s no guarantee you’d be approved for a new policy. |
| Temporary and permanent needs overlap | Partial conversion plus term, if permitted | It can separate the lifelong amount from coverage that has a known end date. |
| No continuing financial need | Reduce or end coverage | Paying more to preserve an unneeded benefit may not solve a current problem. |
Read More: Use the Life Insurance Coverage Review Guide
Read More: Explore Term Life Insurance Options