









Separation or divorce may change why you need life insurance. Still, it doesn’t necessarily answer questions about who owns which policies, who pays the premiums, or who can claim on them. Find out how beneficiary designations, policy information, provincial laws, court orders and separation agreements affect your rights and responsibilities.
MyChoice reviewed the Financial Consumer Agency of Canada’s life insurance guide, the Government of Quebec’s life insurance and succession guidance and the Canadian Bar Association’s discussion of life insurance and child-support obligations.
What Happens to My Life Insurance Policy During a Divorce in Canada?
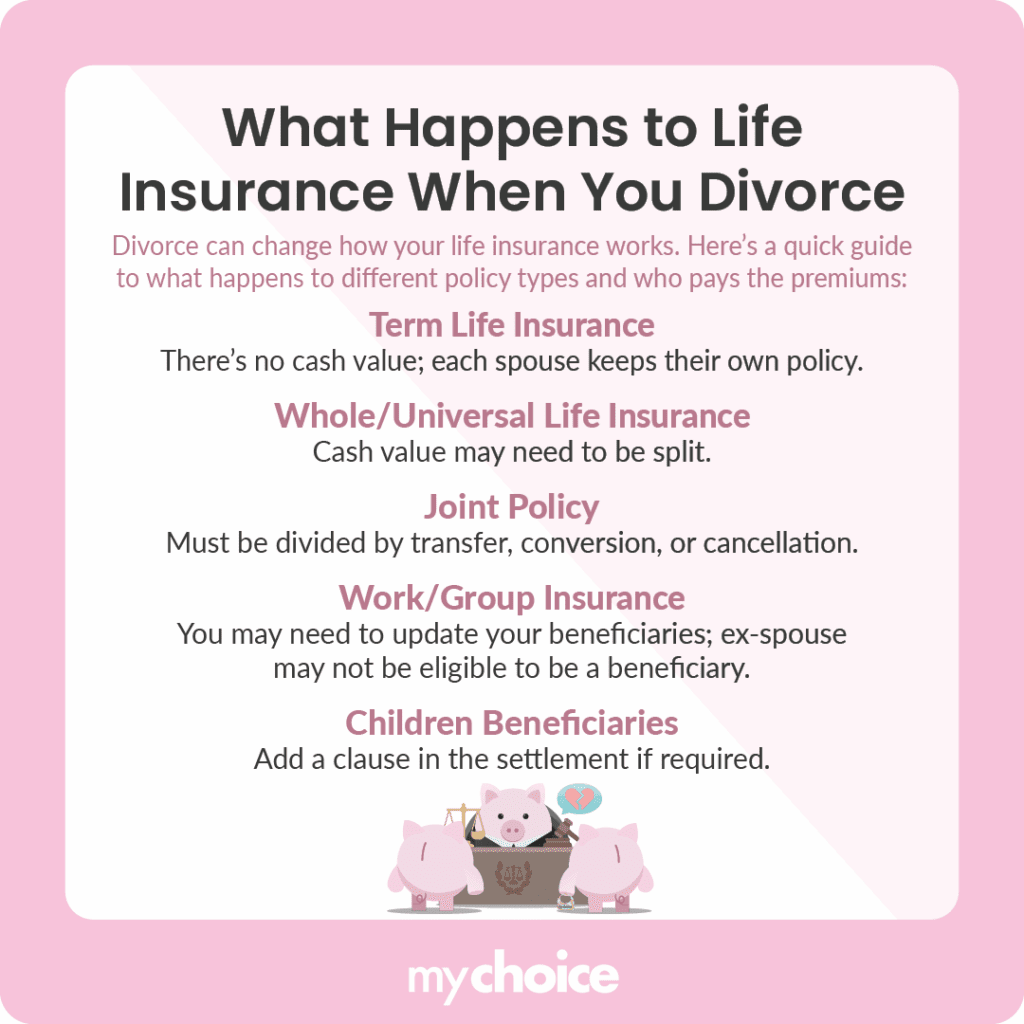
If required premiums are paid, the policy normally remains in force. Don’t assume your ex-spouse is no longer on your policy. You also cannot assume you can change an irrevocable beneficiary or divide a joint life insurance policy.
Determine who owns the policy, who is insured, who the beneficiaries are, how premiums are paid, its cash value, and any legal requirements stated in your separation agreement, divorce agreement or court order.
Be aware of your province’s laws. Quebec is an exception when it comes to making generalizations about life insurance. According to the Quebec government, an ex-spouse is no longer a beneficiary when the marriage or civil union has been dissolved or annulled. It does not state that separation alone dissolves beneficiary status. If there’s no other beneficiary, the insurance money may become part of the succession. Seek legal advice applicable to your situation before making changes.
The Four Life Insurance Roles to Check During a Divorce
| Role | What the role means | Question to answer during divorce |
|---|---|---|
| Insured person | The person whose death triggers the benefit | Does the policy insure one former spouse or both? |
| Policy owner | The person or entity that has certain rights under the contract, subject to beneficiary rules and legal limitations | Who can request changes, assignment, surrender or policy information? |
| Beneficiary | The person, estate, trust or organization named to receive the benefit | Is the designation revocable, irrevocable, required by an agreement, or required by a court order? |
| Premium payer | The person or account providing the money | Who is committed to making payments, how will payments be verified and what happens in case of default? |
Another person can pay a premium without becoming the policy’s owner or beneficiary. Accordingly, if insurance is being used to secure support, the agreement should specify the duty to pay premiums, when they’re due, what constitutes adequate proof of payment and the remedies for default.
Read More: Compare Revocable and Irrevocable Insurance Beneficiaries
How Each Policy Type May Be Affected
What happens to your life insurance policy during a divorce in Canada ultimately depends on your policy type. Some policy types undergo minimal changes, while others may need to be equalized or even ended altogether. Check the table below to learn about what happens to different life insurance types during divorce:
| Policy type | How it may be affected | What you must verify |
|---|---|---|
| Individual term life | Although the policy has no cash value, it may be useful for protecting children, support obligations and debt. | Policy owner, beneficiary, remaining policy term, conversion rights, and provisions of any settlement agreement or court order. |
| Whole or universal life | The policy may have cash surrender value. | Current statement, guaranteed and non-guaranteed values, loans, tax effects and family-property treatment. |
| Joint life | A single policy insures both former spouses. | Whether it is first-to-die or last-to-die, who owns it, what options are available to the survivor and whether the insurer permits the coverage to be changed or split after separation. |
| Workplace group life | It is separate from personal coverage. | Beneficiary form, coverage amount, deadline for converting or porting, and what happens when leaving a job. |
| Creditor or mortgage life | The benefit usually pays the lender or reduces the associated debt. | The insured party, any decreasing insured balance, the lender as payee, and the cancellation or replacement provisions. |
Who Pays the Premiums After Divorce?
There is no blanket rule in Canada about who should pay for a life insurance policy. It will depend on the terms of the contract, including who owns the policy and who is insured. A court order or agreement could also require one party to maintain life insurance.
For example, the support payor could agree to pay the premiums even if they aren’t the policyholder.
You could be ordered or agree to pay for your former spouse’s life insurance, so make sure you discuss whether that would constitute support, a family expense, a reimbursement, or consideration for another obligation. Get it in writing.
Review these issues with your family lawyer and tax professional, as each situation is different.
Should You Get New Life Insurance After a Divorce?
You don’t necessarily need the same amount of insurance as before. Consider support needs, the cost of raising children, housing, liabilities, education, final expenses, existing portable insurance and assets. Keep the information updated.
Divorce is not considered a health issue. However, replacement coverage can cost more because of age, health, occupation and other underwriting factors, or it may be refused.
Do not cancel the old insurance until the new insurance has been applied for, delivered, reviewed and is in force.
Read More: Compare Life Insurance Options for Couples
Common Life Insurance Mistakes to Avoid During a Divorce
Forgetting to Change the Insurance Beneficiary
FCAC says that if the beneficiary is irrevocable, the policyholder needs the beneficiary’s written permission before making changes. If the policyholder can change the beneficiary but an agreement or court order names a beneficiary, making changes could result in legal consequences.
Check each insurance policy, whether personal, employer-provided, association or creditor coverage.
Read More: See How Contingent Life Insurance Beneficiaries Work
Cancelling a Joint Policy Without a Replacement
If you plan to replace your policy, it will need to be underwritten. Unless your lawyer advises otherwise, don’t cancel your existing policy until you have the new one confirmed in writing.
Check with the insurer and your lawyer to determine whether one policyholder or co-owner can cancel, transfer or amend a joint policy. The contract will determine what can be changed.
Read More: Read the Life Insurance Policy Cancellation Guide
Not Updating Workplace Insurance Separately
Changes made to your personal policies likely will not be made to your employer-provided policies.
Ask your employer’s human resources department or the plan administrator:
- Who is my current beneficiary?
- What are my conversion or portability rights?
- Are there deadlines if I lose eligibility for benefits or leave my job?
Naming Minor Children as Beneficiaries Without a Trustee
The person who cares for your child doesn’t necessarily have the legal right to manage money belonging to your child. FCAC suggests creating a trust and naming a trustee or administrator if your beneficiary is under the age of majority.
Get estate-planning advice on trusts or wills applicable in the child’s province, and make sure the insurance policy and trust or will match.
Assuming Divorce Automatically Changes Life Insurance Status
Don’t assume a divorce order automatically updates an insurer’s files. Some jurisdictions have specific rules, and Quebec has a former-spouse rule. Rules and policies vary in other provinces.
When the insurer accepts a change, ask for written confirmation. Keep it with your agreement, court order and annual in-force documents.