









Getting married is a significant milestone that often comes with a host of new responsibilities, including financial planning and securing your family’s future. Life insurance is a vital aspect of this necessary planning. Understanding your life insurance options can provide peace of mind, ensuring that your loved ones are protected financially in the event of an unexpected loss.
What’s the best life insurance plan for a married couple? Does having children affect your life insurance needs? Read on to learn more about life insurance options for married couples.
To prepare this guide, our editorial team reviewed the Financial Consumer Agency of Canada’s life-insurance guide, FSRA’s explanation of life-insurance policy types, and FSRA’s policy-reading guide.
Which Life Insurance Structure May Fit a Couple?
There is not necessarily a couple’s discount. Separate policies provide the most control. Joint coverage may make sense if the amount of coverage is intended to meet one shared obligation triggered by the first death.
Understand the differences between joint and survivorship coverage, which only pays after both pass away. Joint last-to-die coverage is often appropriate for inheritance or estate planning needs, but it won’t meet most other coverage needs because it wouldn’t pay at the first death.
There is no one-size-fits-all answer, so get quotes and compare illustrations to see whether there is a discount or surcharge for a particular set of applicants, product, amount of coverage, insurance company and policy structure.
Read More: Review Life Insurance Plan Options for Families
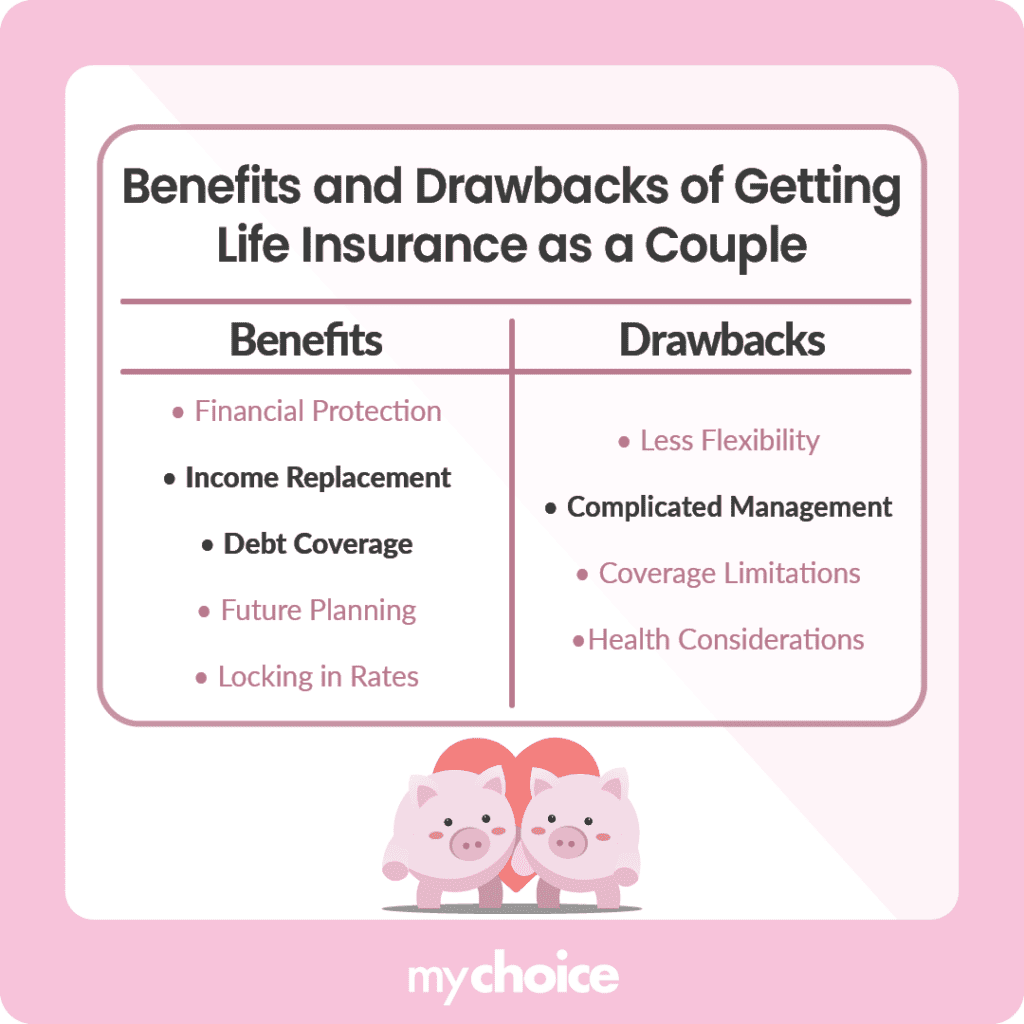
Joint Life Insurance Policies for Couples
| Feature | Separate policies | Joint first-to-die | Joint last-to-die |
|---|---|---|---|
| Payment trigger | Each policy pays on its insured person’s death | Pays after the first insured person dies | Pays after the second insured person dies |
| After first death | Survivor keeps their own policy if it remains in force | Policy usually ends after its one payment; survivor option may vary | No death benefit is paid yet; policy continues under its terms |
| Coverage amounts | Can differ by person and term | Usually one shared amount | One amount for the eventual beneficiary |
| Common use | Different income, care, debt or dependent needs | Shared mortgage or temporary first-death need | Estate expenses, legacy, trust or permanent second-death need |
| Separation | Ownership and beneficiaries can be handled policy by policy | Joint ownership and continuation can be difficult | Long-term ownership, premium and beneficiary plan must be resolved |
| Price comparison | Get two matched individual quotes | May cost less than two identical individual policies | Compare as a permanent estate product, not with first-death income coverage |
Separate Life Insurance Policies
Separate policies are a little bit more flexible and can be helpful if your circumstances are different. Perhaps one of you earns considerably more than the other, does most of the unpaid care, has business debts or would want a shorter or longer term. Also, with separate policies, both partners can specify who owns the policy and who the beneficiaries are.
However, you’ll be taking out two contracts, which may be more complicated.
If both partners died during the term, both policies would pay out.
How to Choose Between Joint and Separate Coverage
Calculate the loss from Partner A’s death separately from Partner B’s death. Determine how much money you would need after the first death, after the second or after both.
Find out who will own the policy, pay premiums and control the benefit. Find out what happens to the policy if you separate. Get the survivor and conversion rights in writing.
Don’t assume you’ll get a discount if you buy coverage together. Get a quote for both of you together and a quote for the same amount of coverage, on the same guarantee and health class, separately.
Read More: Read How Divorce Can Affect Life Insurance
How Children Change the Coverage Need
Adding a child can increase the amount of income replacement and care replacement needed, as well as the time it would be required.
Factor in education goals, childcare expenses and any household work the surviving parent would need help completing.
Last-to-die insurance is not an appropriate solution for income or care replacement when the first parent dies. It will not help to offset these expenses.
Read More: Read the Life Insurance Guide for New and Expecting Parents
How Much Life Insurance Coverage Does a Couple Need?
Keep in mind that although a calculator is a helpful tool, it won’t choose the number of years to replace income for, growth rate or the liquid assets reserved for other purposes. These assumptions need to be documented.
Estimate coverage for each partner:
Final expenses and joint liabilities + income and unpaid care replacement after tax for several years + needs of dependants or a business − existing coverage − liquid assets reserved for these needs = approximate protection needed
Read More: Estimate Your Couple’s Life Insurance Needs
Plan for Separation and Survivor Insurability
- Confirm whether the insurance is transferable. Who has the right to cancel, assign, borrow against or change the beneficiary?
- Determine whether the contract permits the coverage to be divided between the individuals. If so, what deadlines, amount of insurance, type of insurance and proof are needed? Do not cancel the original insurance until the replacement is issued and accepted.
- After separation, review beneficiary designations. Changes may be restricted by an agreement or court order, or the beneficiary may be irrevocable.
Read More: Compare Revocable and Irrevocable Insurance Beneficiaries