









Wondering about contingent beneficiaries on a life insurance policy? We reviewed the Financial Consumer Agency of Canada’s life insurance guide, Ontario’s Insurance Act, CPA British Columbia’s beneficiary-designation discussion and the Journal of Insurance Regulation’s study of per-capita and per-stirpes wording to bring you this article on contingent beneficiaries.
What Is a Contingent Beneficiary in Life Insurance?
A contingent beneficiary, or alternate beneficiary, is the person or organization that will receive the benefits of your insurance policy if your primary beneficiary is not able to receive them as stated in the insurance policy.
The Financial Consumer Agency of Canada describes alternate or contingent beneficiaries as an individual, trust, estate or organization that is eligible to receive proceeds from a beneficiary designation if a primary beneficiary dies before or at the same time as the insured.
A contingent beneficiary does not mean there will be an additional or separate benefit. In general, unless stated on the beneficiary designation, a contingent beneficiary does not share the proceeds if the primary beneficiary is eligible and alive.
What’s the Role of a Contingent Beneficiary in Life Insurance?
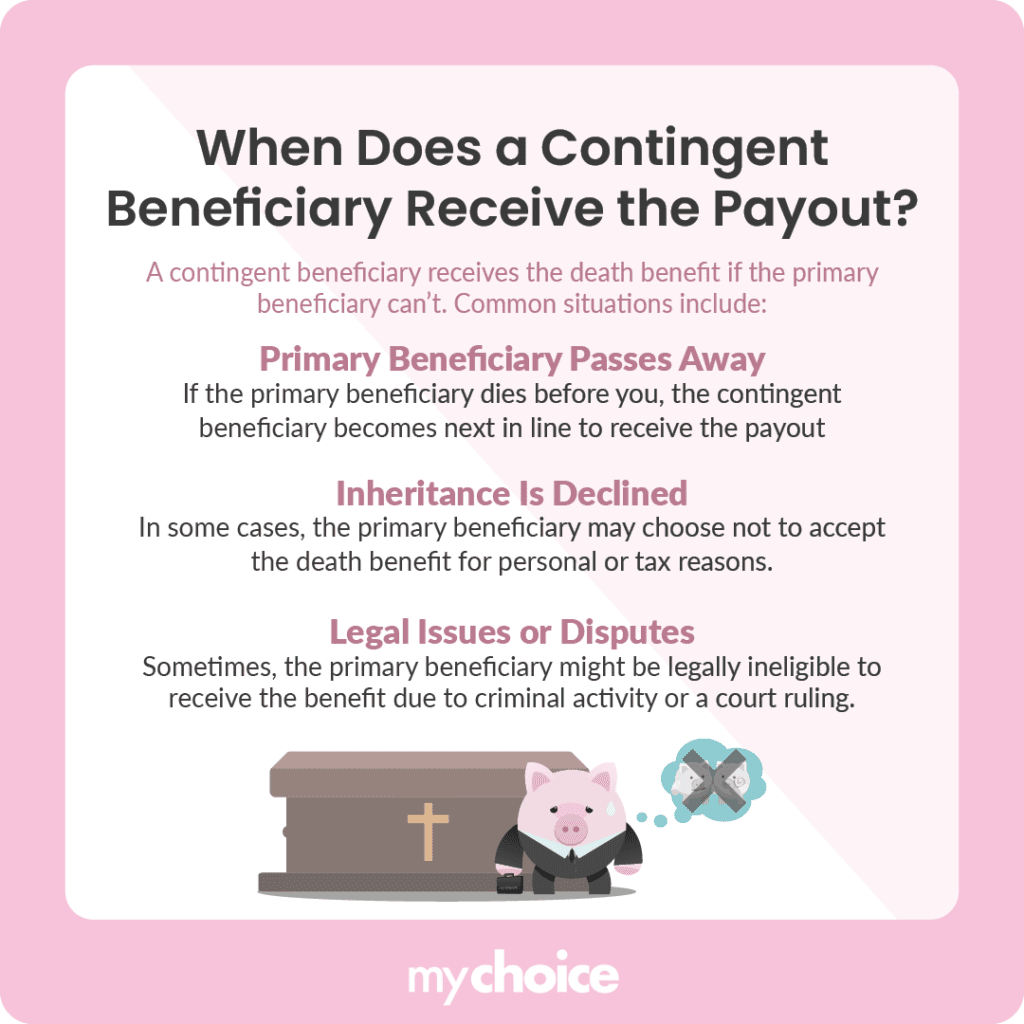
If the person you’ve named as beneficiary dies before you do and there are no further instructions on the beneficiary-designation form, the proceeds may go to a person or place determined by the insurance policy or provincial law.
A contingent designation avoids this result by directing proceeds elsewhere if the sole beneficiary dies before you.
However, specifying a contingent beneficiary doesn’t necessarily mean the proceeds will be received promptly. Insurance companies may request documentation, such as a claim form, death certificates, identification, proof of the order of death or proof of legal entitlement, before releasing the proceeds. Some claims may also be disputed.
Primary vs. Contingent Beneficiary
| Question | Primary beneficiary | Contingent beneficiary |
|---|---|---|
| When is this tier considered? | The primary tier is considered first, subject to the policy and designation. | It is considered only if the contingent designation’s triggering condition is met. |
| Can there be more than one? | Yes. State the percentage or share for each. | Yes. State the percentage or share for each. |
| Can you change it? | Usually, if revocable. Written consent is generally needed if irrevocable. | Rules can be the same for revocable and irrevocable situations. |
| What if the recipient is a minor? | A trust, trustee or administrator may be needed. | Minor-beneficiary issues still apply when this tier takes effect. |
| Does the will control? | A policy designation may operate apart from a will. | Do not assume that a later will alters the policy form. |
Read More: Compare Revocable and Irrevocable Insurance Beneficiaries
How to Name a Contingent Beneficiary
| Form item | What to enter or confirm | Why it matters |
|---|---|---|
| Recipient identity | Recipient’s full name and any other identification indicated by the insurer | After some life changes, it’s not clear who “my spouse” refers to. |
| Primary allocation | Percentages or shares should add up to the total required by the form. | When a primary beneficiary is deceased, their share may not pass where the policyholder expects. |
| Contingent allocation | Totals are summed according to the instructions. The backup tier should be complete. | A contingent person may back up multiple primary beneficiaries. |
| Revocability | Choose revocable or irrevocable as required by the form. | Once a designation has been made irrevocable, written consent is generally required to change it. |
| Minor recipient | Ask about a trustee, administrator or formal trust. | These impacts can last until the age of majority. |
| Estate or trust | Use the exact legal name and obtain legal advice. | A trust must be validly identified to be recognized or enforced. Estate proceeds are subject to claims by the estate’s creditors. |
| Acceptance | Get written confirmation once you’ve submitted the signed document. | A draft beneficiary designation kept at home is not equivalent to a beneficiary designation sent to the insurer. |
FCAC says that in Quebec, there is a special rule for a spouse named as beneficiary. A beneficiary who is a spouse is considered irrevocable unless stated to be revocable.
Outside Quebec, beneficiary rules vary by province and policy.
Situations Where a Contingent Beneficiary Might Step In
Ontario, for example, provides rules for what happens when a beneficiary dies before the insured if the contract or declaration does not say who receives the deceased beneficiary’s share.
Section 194 of the Insurance Act provides that the deceased beneficiary’s share goes to the surviving beneficiary or beneficiaries, equally if there is more than one. If there are no surviving beneficiaries, the share goes to the insured or their personal representative.
Different provisions apply in other provinces.
“Per Stirpes” vs. “Per Capita” Designations
Before using terms such as “per stirpes” or “per capita,” which refer to what happens if a beneficiary dies before you, check with the insurance company to confirm how it uses them.
Backup plans get more complex when you have more than one child or other beneficiary.
| Desired result | Illustration | Safer next step |
|---|---|---|
| A deceased child’s share passes to that child’s descendants | If a child were to die before the insured, the deceased child’s branch is supposed to inherit that child’s 50% share. Otherwise, each child receives a 50% share. | Ask whether the form allows for per-stirpes distribution. Any unusual language should be sent for review. |
| Only listed living recipients share the amount | Any surviving listed children share the payable balance as stated on the form. | Check the insurer’s definition of per capita and its default rule. |
Read More: Read the Ontario Guide to Will Beneficiaries
Revisiting and Updating Your Beneficiaries
Request confirmation after changing beneficiary designations and keep it with your insurance papers.
Review beneficiary designations:
- After important changes in personal relationships, such as marriage, separation, divorce, the birth or adoption of a child, or the death of a beneficiary
- After changes in your financial situation or support requirements
- If you move to another province, change jobs, replace an existing insurance policy, establish a trust or make changes to your will
If the policy has an irrevocable beneficiary, get advice before changing ownership of the policy, borrowing against the policy or changing beneficiary designations.
Read More: Use the Life Insurance Coverage Review Guide