









Life insurance is available to freelancers, but figuring out how much coverage you need can be more complicated because freelancers typically have unique business obligations and income levels. For this reason, this guide splits its coverage-amount discussion into two parts: one for your personal or household needs and one for your business needs.
During our research, we referred to the Financial Consumer Agency of Canada’s life-insurance guide, FCAC’s disability-insurance guide, the Canada Revenue Agency’s T2125 information, and the Insurance Bureau of Canada’s business-coverage guide.
How Do Freelancers Get Life Insurance?
You can apply for an individual life insurance policy through a licensed agent or broker or directly through the insurer.
If you’re a freelancer, the application and underwriting process is pretty much the same. Freelancing shouldn’t necessarily result in higher premiums or a declined application. Insurers will consider whether the amount of coverage is justified in light of your income, outstanding debts, number of dependants and any commercial purpose. Different insurers have different evidentiary requirements.
Start by calculating the financial loss that will result from your death. This will determine the amount and length of coverage you’ll need.
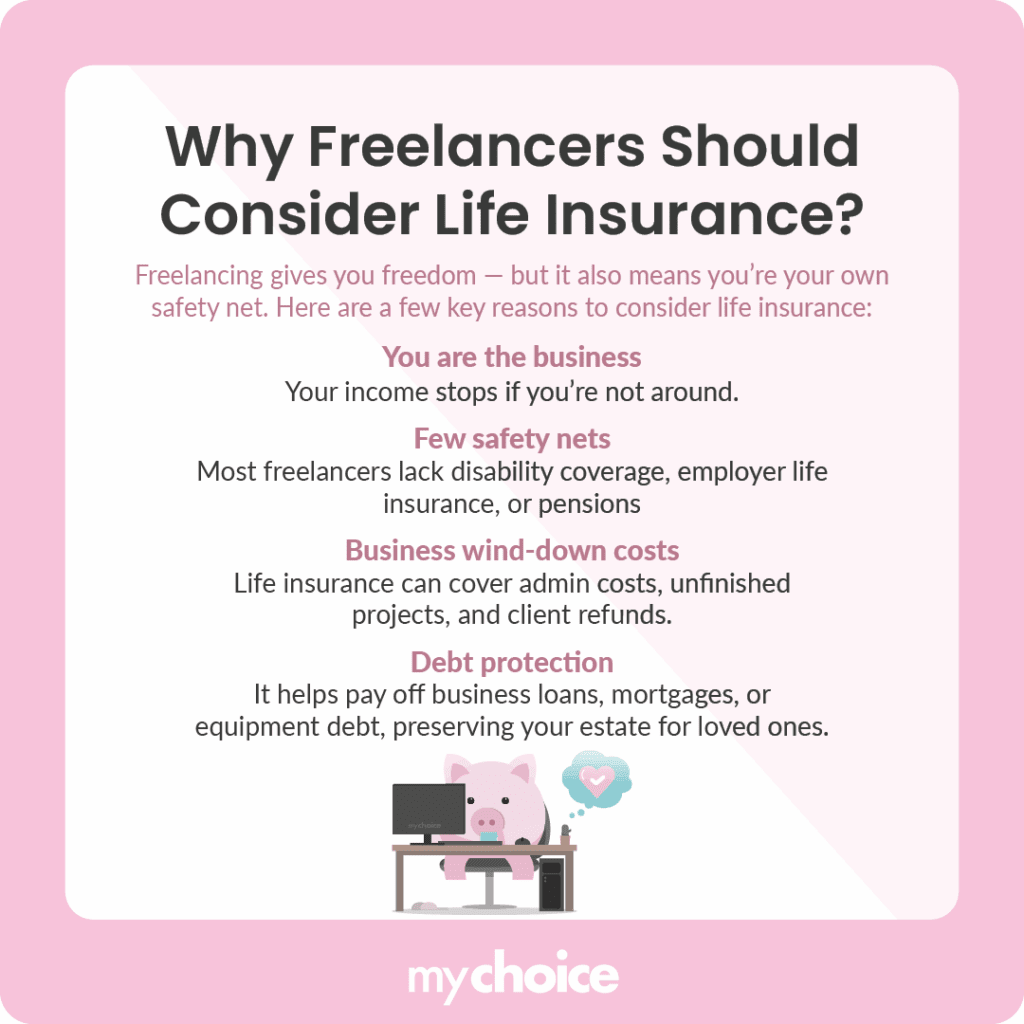
When Freelancers May Need Life Insurance
Before you make a decision on whether you need life insurance as a freelancer or not, you should take into consideration the following:
- Estimate your after-tax household contribution, including any housework or care responsibilities.
- Also consider any debts or guarantees that would face your estate, other borrowers or your business, as well as funeral expenses and any transition assistance required by your dependants.
- Consider the costs of closing down or transferring your business, including legal and accounting fees, repaying deposits to clients and completing or handing off work.
- Talk to your accountant or lawyer if you have an incorporated business to consider the tax, asset and probate implications of owning life insurance at the personal or corporate level. Sole proprietors’ needs differ from those of incorporated business owners.
How Much Coverage Should You Get?
| Need | What to include | What to subtract |
|---|---|---|
| Household support | After-tax household contribution and unpaid care for a chosen number of years | Survivor income available for this need and dedicated liquid assets |
| Personal obligations | Final expenses, joint debt and education or dependant goals | Existing individual or group life coverage |
| Business wind-down | Refundable deposits, contracted transition work, professional fees and closure costs | Liquid business assets and amounts recoverable under contracts |
| Business debt | Debt or leases the estate, corporation or guarantor remains responsible for | Creditor or business-owned coverage assigned to the obligation |
Review your coverage:
- When there is a significant client concentration;
- When you incorporate;
- When you get a loan or add a dependant; and
- After a sustained income change.
Coverage should address long-term financial responsibilities and shouldn’t change based on monthly invoices.
Which Policy Type May Fit a Freelancer?
Permanent insurance makes sense if you have a permanent insurance need, such as estate and tax planning, business succession or lifetime dependant-care planning. Be aware, though, that permanent insurance is expensive. You shouldn’t buy permanent insurance just because you’re a freelancer.
Term insurance makes sense if you have a need that expires, such as a mortgage, a certain number of dependant-care years or even a career. Make sure you choose the right term; a 10-, 20- or 30-year term isn’t automatically right for every freelancer. Watch for conversion and renewal provisions.
Read More: Compare Term and Whole Life Insurance
What Makes Getting Life Insurance Tricky for Freelancers?
- Problems explaining income or a business purpose, such as starting a business, having a big expense year or moving from employment;
- CRA reporting, which could include a T2125 for business or professional income and expenses if you’re a sole proprietor, or financial statements if incorporated;
- Personal and business tax returns, notices of assessment, contracts, invoices, business banking records and evidence of repeat business;
- Business-related documentation, such as loan or lease agreements, personal guarantees and shareholder agreements;
- Averaging periods or alternate documentation, since not all insurers request two years of records or follow the same approach; and
- A new business, seasonal income, retained corporate income or a business that has changed significantly during the past year.
Ask what documentation the insurer requires before submitting an application.
Life Insurance Does Not Cover Every Freelancer Risk
| Risk | Coverage to investigate | Key question |
|---|---|---|
| Death | Personal or business-owned life insurance | Who suffers the loss, owns the policy and receives the benefit? |
| You cannot work because of illness or injury | Individual disability income insurance | How does the policy define disability, income and partial work? |
| The business has fixed costs while you are disabled | Business overhead expense coverage | Which expenses, waiting period and benefit period are included? |
| A client makes an error | Professional liability or errors-and-omissions coverage | Does the policy cover your exact services, territory and prior work? |
| Equipment, data or a client incident causes a loss | Commercial property, cyber or general liability coverage | Which assets, data, locations and activities are included? |
According to FCAC, some self-employed people may want disability insurance. Overhead expense insurance, which covers certain business costs if you’re disabled, differs from disability insurance that replaces lost income.
Read More: Compare Consultant Insurance Options as a Freelancer
How to Prepare and Compare Policies
- Complete a household and business needs calculation before requesting quotes.
- Ask each insurer what financial evidence it needs for the requested amount and ownership structure.
- Compare the same amount, term, health class, riders, guarantees and renewal or conversion schedule.
- Disclose work duties, travel, activities, health and finances accurately. Correct errors in writing.
- When the policy arrives, verify the owner, insured person, beneficiary, premium, benefit and cancellation period. The review period varies by contract and province; do not assume a Canada-wide 10-day rule.
Read More: Compare Life Insurance Options
Sole Proprietor vs Incorporated Freelancer
A sole proprietorship is not distinct from its owner, while a corporation is a legal person separate from its owners. The distinction matters because it affects debt responsibility, benefits and other needs. It can also determine who should own a life insurance policy.
Owning a life insurance policy in the company’s name generally doesn’t make the premiums tax-deductible. Before purchasing life insurance through the corporation, have an accountant advise you on the tax treatment. Have a lawyer advise you on issues involving shareholders, buy-sell agreements, estate matters and creditors.
Read More: Read the Home-Based Business Insurance Guide