









Inflation can erode the purchasing power of a fixed death benefit. But using a one-size-fits-all inflation factor to adjust your coverage needs could lead you to overestimate how much coverage you need.
Our content team researched Statistics Canada’s 2025 CPI review and Statistics Canada’s CPI portal, the federal life-insurance guide, and the Canadian Bar Insurance Association’s needs calculator.
You can adjust your life insurance amount by recalculating your needs for each financial goal and exploring the impact of a range of inflation rates.
Keep in mind that your assets and debts can change over time, and whether you can increase your coverage depends on your policy’s terms.
Do You Have Enough Life Insurance After Inflation?
As prices go up, the purchasing power of the death benefit decreases. It’s enough if the death benefit plus other resources fills your survivors’ gap. Over time, however, their gap changes. The mortgage may be paid down a bit each month, children may become independent, your savings may increase. Recalculate the gap; don’t just increase your insurance.
Start With A Goal-By-Goal Needs Inventory
| Need or resource | When needed | How it may change |
|---|---|---|
| Final and immediate expenses | At death | Update local estimates. |
| Mortgage and other debts | At death or over payoff period | Usually declines with payments. |
| Income or caregiving replacement | For ___ years | Consider household expenses, inflation, taxes, and survivor income. |
| Childcare and education | Specific years | Assign separate timelines and savings. |
| Permanent support or legacy | Long term | May involve legal structures, trusts, and tax issues. |
| Existing individual and group insurance | While coverage remains active | Employment changes can affect group coverage. |
| Savings and other survivor resources | At death and later | Consider liquidity, taxes, and investment risk. |
Coverage gap = lump-sum needs + the amount required to fund recurring needs − reliable resources available to survivors.
When determining the present value of ongoing income needs, consider inflation and expected investment returns after deducting investment-related fees.
Read More: Review Canada’s Life Insurance Coverage Gap
How Inflation Affects Life Insurance
According to Statistics Canada, the annual-average Consumer Price Index increased by 2.1% in 2025. The Consumer Price Index is up by 19.9% compared with five years earlier.
Inflation has occurred over the past few years, but that doesn’t necessarily indicate what may happen 20 years down the line. Increases can vary by category, so using an all-items inflation rate from Statistics Canada may not apply to everyone’s inflation-related goals for education, home prices, long-term care, etc.
Inflation impacts the purchasing power of money, but does not necessarily affect the nominal cash value or death benefit in your life insurance policy. It’s important to know the difference between the non-guaranteed illustrated values, the guaranteed cash value, and the guaranteed death benefit on a life insurance policy.
How To Calculate An Inflation-Adjusted Future Cost
Future cost = current cost × (1 + annual inflation assumption) raised to the number of years
Note that this is a sensitivity analysis of a single future expense, not a comprehensive analysis of life-insurance needs.
| Starting future expense | Years | 2% assumption | 3% assumption | 4% assumption |
|---|---|---|---|---|
| $500,000 | 20 | $742,974 | $903,056 | $1,095,562 |
For simplicity, we used a 3% inflation rate and treated the full $500,000 as an expense in year 20. A mortgage is an amount due now; annual household expenditure and education costs would be incurred in different years. Create separate line items for each expense, and run the same calculations at 2%, 3%, and 4% inflation rates. Compare the difference in the gap and the premiums.
Do Insurance Companies Adjust Life Insurance Policies For Inflation?
Some insurance contracts include a guaranteed-insurability option, cost-of-living option or additional-purchase option. Check the policy for these provisions, the dates, and the maximum increases allowed. Additional premiums may apply.
Without an option, increasing death benefits may require a new application and possible medical/financial underwriting. In general, most level policies do not raise death benefits to match CPI.
Which Types Of Policies Does Inflation Affect The Most?
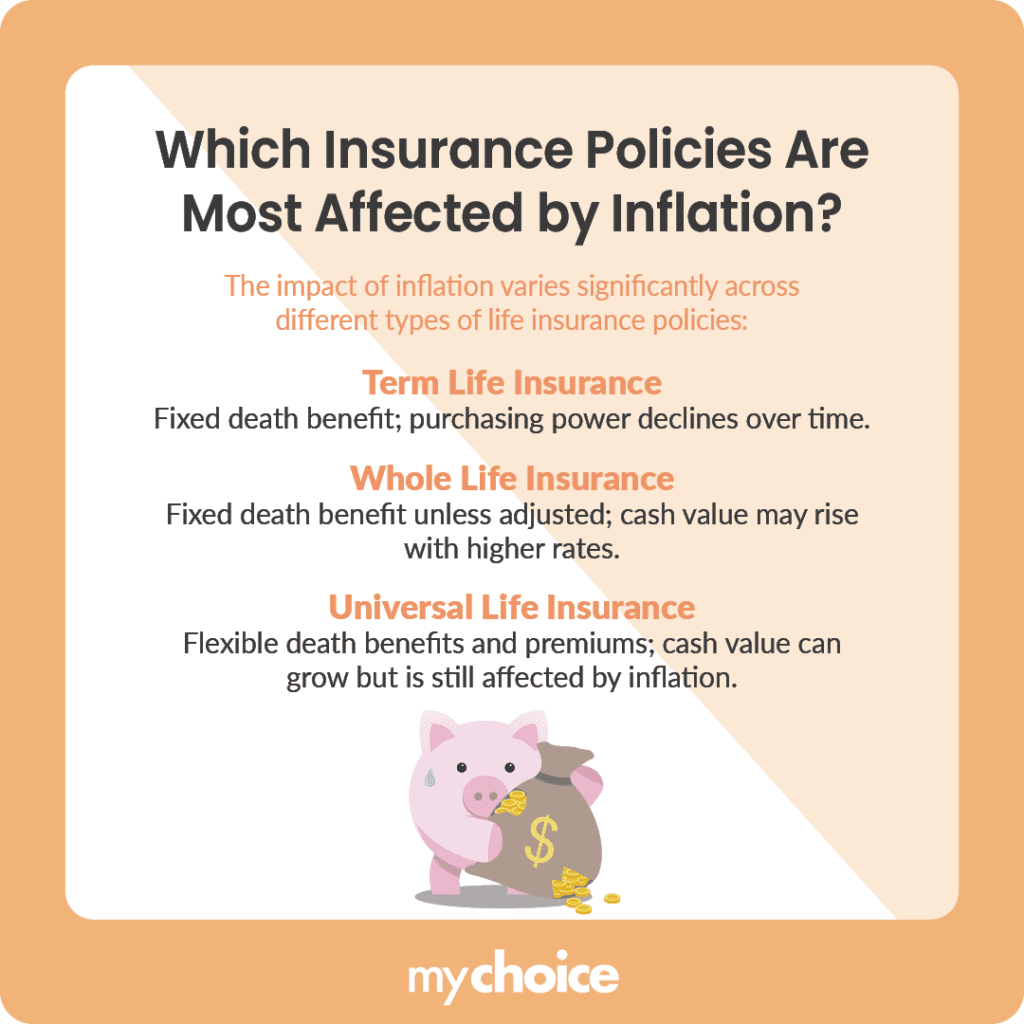
| Policy feature | Inflation question |
|---|---|
| Level term death benefit | Does the amount the policy pays out cover the shortfall during the duration of the term? |
| Renewable term | Should you pay the higher renewal premium on your policy or should you apply for new coverage? |
| Convertible term | What conversion options and deadlines apply? |
| Whole life | Which death benefit and cash values are guaranteed, and which depend on dividends? |
| Universal life | How do charges, returns, premiums and death-benefit options react under lower-return illustrations? |
| Increase option or rider | How much can be added, when, and at what price? |
Permanent insurance doesn’t necessarily protect you from inflation; just because your cash value increases doesn’t necessarily mean the death benefit grows to meet your household’s needs.
How To Select A Policy That Accounts For Inflation
How big is the gap between what you have and what you need? Calculate it before choosing a policy type.
Different needs have different time frames; for example, temporary income replacement, the mortgage, education. Base the policy term on the time frames of those needs.
For permanent insurance, illustrations should clearly indicate guaranteed and non-guaranteed amounts, including a lower-return illustration.
Read More: Compare Term and Whole Life Insurance
Get quotes for the same total coverage as one level term policy as well as a ladder of smaller, shorter-term policies. You can’t know which is less expensive without quotes.
Ask how future coverage increases work and whether they require a new medical or financial application.
Read More: Recalculate How Much Life Insurance You Need
When To Review Coverage
| Trigger | Recalculate |
|---|---|
| New child or dependant | Caregiving, income replacement, education funding, and beneficiaries. |
| Home purchase or refinance | Debt, assets, survivor housing plan, and term length. |
| Job or benefits change | Group coverage, income, pension changes, and conversion deadlines. |
| Divorce, marriage or new partner | Beneficiaries, financial obligations, agreements, and property ownership. |
| Large savings or debt reduction | Resources available and remaining shortfall. |
| Policy renewal or conversion deadline | New quotes, health changes, affordability, and expected coverage duration. |