









In recent years, mental health has become one of the most talked-about issues for Canadians. Throughout the country, people are more willing to discuss anxiety, depression, and stress than ever before.
In this guide, our content team has looked into the federal insurance-application guide and the federal life-insurance guide, the Canadian Life and Health Insurance Association’s consumer guide, and the Office of the Privacy Commissioner’s access guide. You will learn about questions insurers may ask, consent, medical records, and the differences between fully underwritten, simplified, and guaranteed issue life insurance.
Can I Get Life Insurance If I Have A Mental Health Diagnosis?
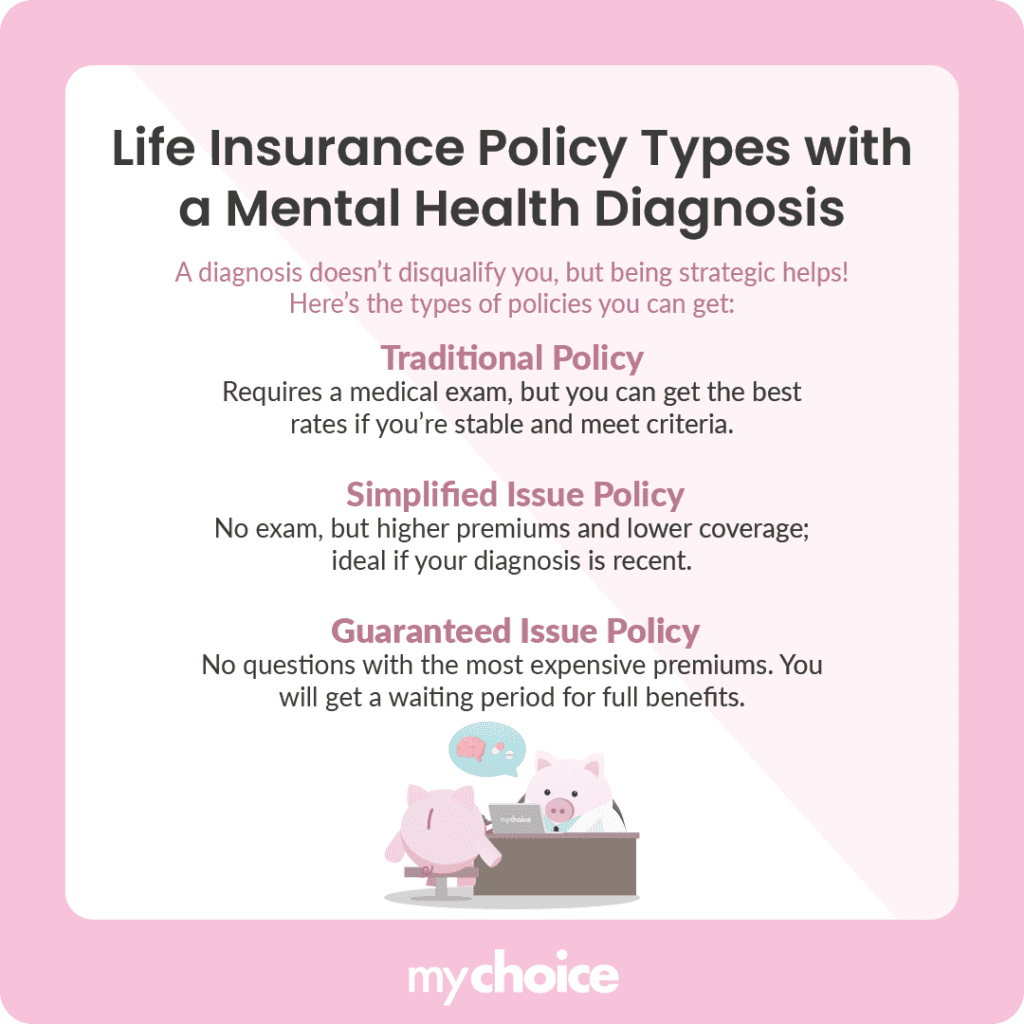
You may be eligible for life insurance. Never delay, change, or stop treatment because you’re applying for life insurance.
Each application is reviewed according to an insurance company’s current guidelines. Providers consider the amount of coverage, your age, mental health diagnosis and symptoms, ability to function, treatments, when your condition has changed, other health conditions, substance use, and any hospitalizations or emergency room visits.
Outcomes vary by insurance company and insurance product.
Choose The Application Route
| Route | What it may require | Tradeoff to check |
|---|---|---|
| Fully underwritten | Detailed application which may require answers to health-related questions and verification from a physician or paramedical examiner. | It may offer broader coverage amounts or lower rates, but the outcome is specific to each case. |
| Simplified issue | This route has a shorter medical questions section and usually requires no paramedical exam. | Different routes can mean different underwriting questions, limits, premiums, and eligibility. Opting for a simplified application does not mean there’s no requirement to disclose. |
| Guaranteed issue | This route asks few or no health questions. | This route typically provides smaller benefits, can be more expensive and benefits are limited or graded in the early years. |
| Group coverage | You qualify through your work or association. | Amount, termination, conversion and portability rules apply. |
| Tentative or informal inquiry | With your consent, an adviser may ask insurers how they may assess your situation before you apply. | This route is not offered by every insurer and is not a binding quote. |
Read More: Explore No-Medical Life Insurance Options
What Mental Health Information May Matter?
| Area | Examples of information an insurer may request |
|---|---|
| Condition and timeline | Specific diagnosis and its onset; number of episodes and their duration; current symptoms; most recent change in condition |
| Treatment | Medications, counselling and specialist care; response to treatment; side effects; follow-up |
| Function | Time away from school or work; everyday activities and current functional limitations |
| Urgent care | Hospitalizations; ER visits; if asked, suicidal ideation or attempts |
| Other factors | Tobacco smoking, alcohol, or drug use; physical health issues and other medications |
| Coverage request | Purpose; amount; income; assets; occupation; other insurance in force or applied for |
Apply Without Compromising Your Care
Consider how much coverage you need and for how long.
Check any coverage you have through your workplace or other associations.
When you’re assessing coverage options, look at the health questionnaire, benefit limitations, monthly cost, graded or waiting periods, and conversion rights.
Treatment decisions should be made between you and your clinician. Never put treatment on hold, stop a medication, or avoid necessary medical care because of insurance-related issues.
Before completing multiple full applications, consider hiring a licensed agent or broker to make a tentative inquiry. When doing so, make sure you’re comfortable with what information will be shared and with whom.
Answer all questions completely and accurately. If you’re unsure of dates or other information, ask how to amend your application.
Insurers will specify any supporting documentation or medical records they need. Unless required, don’t automatically provide an entire therapy file. Review consent and ask how records can be shared securely.
Consent, Records And Privacy
You may be asked for written authorization before an insurer obtains information from a physician or another source. Read it carefully. Check its purpose, organizations, information types, period and expiry, plus how information will be stored, used and corrected.
Canadian businesses are subject to one of several pieces of privacy legislation. PIPEDA applies to private-sector businesses in provinces without substantially similar privacy laws. Applicable law may let you access business-held personal information, correct errors, or record an unresolved concern.
If you have a concern, start with the insurer’s privacy officer. If you’re not satisfied with the officer’s response, you can contact the federal or provincial privacy authority.
Read More: See How Health Records Affect a Life Insurance Application
What Underwriters Look For In Your Application
Read More: Review the Canadian Life Insurance Underwriting Process
Medical Records Review:
After receiving authorization, the insurer may request an attending physician’s statement or other relevant records.
If a record contains an error or out-of-date information, correct it through the insurer’s established process. Do not ask the clinician to write for a predetermined insurance outcome.
Paramedical Exam And Information Services:
Your application and consent should explain any insurance information service used.
A paramedical exam may include measurements, sample collection and/or written and/or oral questioning.
Financial Underwriting:
Separate from a medical underwriting decision, the insurer may want to perform a financial underwriting.
Questions may include why you need the requested coverage amount. They may consider your income, occupation, assets, and existing/pending insurance.
Possible Decisions And Your Next Step
| Decision | What it means | Next step |
|---|---|---|
| Standard offer | The product was approved and your insurer is offering its standard class for it. | Double-check that the premium and policy details are accurate. |
| Rated offer | Coverage is offered at an increased premium or in a different class. | Compare the alternatives. Ask whether a review option is available. |
| Modified offer | Limits on the amount, term, rider, or benefit. | Look over the exact contract, not just the premiums. |
| Postponed | The insurer is not making a decision on your application at this time. | Ask why and when it may reconsider your application. |
| Declined | The insurer will not offer the product in question based on the application that was submitted. | If you don’t understand the decision, consider requesting the reason and details of the records process. Depending on the decision, your options may include making a request for correction, choosing another route, or making a complaint if appropriate. |
If You Disagree With The Decision
Get the decision, why you received it, and your options for having it reviewed again in writing.
Check your records, correct any incorrect information following your insurer’s privacy process, and make sure you’ve sent all relevant information to your insurer.
Follow your insurer’s dispute process. After its final response, you may be able to refer the matter to the Ombudsman Service for Life and Health Insurance. You may be able to complain to the appropriate regulator or privacy authority.
Read More: See Your Next Steps After a Life Insurance Denial