









Should you get life insurance? That’s a tricky question to answer because no single answer applies to everyone. As a rule of thumb, getting life insurance is worth it if someone’s death would create a financial deficit that a household, estate or business cannot absorb.
Our editorial team reviewed the Financial Consumer Agency of Canada’s life-insurance guide, the Financial Services Regulatory Authority of Ontario’s policy-type guide, FSRA’s questions to consider before buying life insurance, and FCAC’s current insurance-purchase guidance.
Is Getting Life Insurance Worth It in Canada?
Life insurance makes sense if people rely on your income or unpaid work. It can also make sense if the death of a key individual would create financial uncertainty for your business. Life insurance probably doesn’t make sense if your estate has enough liquid assets to cover your liabilities.
When considering any life insurance policy, cost matters, along with the policy’s terms. Before shopping around, first figure out whether you need life insurance, then how much you’ll need. After that, compare policies and make a purchase.
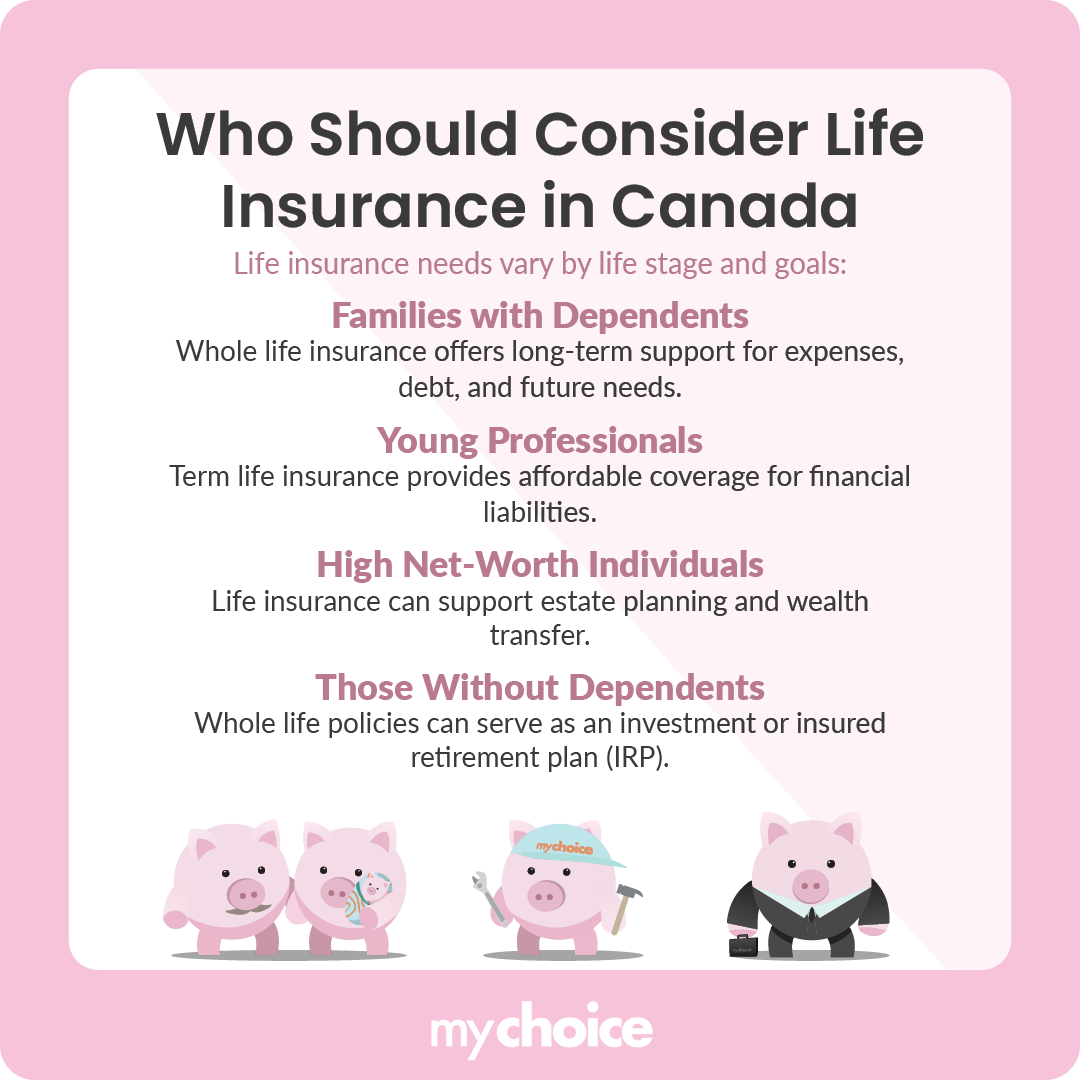
Who Needs Life Insurance in Canada?
| Situation | Possible financial gap | Question to answer |
|---|---|---|
| Family depends on your income | Housing, food, childcare, education and time to adjust | How much annual support is needed, and for how many years? |
| You provide unpaid care | Replacement childcare, elder care, transportation or household work | What would it cost to replace that work locally? |
| You have joint or estate obligations | Debts, taxes or final expenses that available assets cannot cover | Which obligations survive, and who would have to pay them? |
| Your business depends on you | Revenue interruption, successor costs or a buyout obligation | Is the need personal, business-owned or governed by an agreement? |
| No dependant and enough liquid assets | Possibly little or no protection gap | Is there a defined lifelong or estate goal that insurance solves better? |
Read More: Review Reasons Not to Buy Life Insurance
When Age and Health Make Timing Relevant
Age in itself is not enough to determine when to get insurance. On the other hand, getting insured before your health changes could improve your chances of qualifying for coverage. Buying insurance when you don’t yet need it may mean paying unnecessary premiums for several years.
When You Want to Provide for Your Loved Ones
This number will vary based on many factors. Determine what expenses will continue, what will change, what income they’ll receive, and how long you need to provide. Do not simply replace gross salary for a defined period. Taxes will have an effect, as will decreased expenses. Survivor income, government benefits and assets will all reduce the amount you need.
When You Want to Provide for Your Children
Try to work out how much you’ll pay for childcare or equivalent care. You can use local rates as a guide, but these rates and subsidy levels vary widely by location and personal circumstances. Consider a few scenarios and include schooling and education costs.
When You Own a Business
Key-person insurance can help a business manage the financial impact of losing an important owner or employee. You may also need liquidity to cover business debt and succession-related costs.
It’s important to separate these needs from your obligation to insure your family’s financial security. Consult professionals about insurance needs, entity ownership, beneficiary designations and tax treatment based on your business’s legal structure and any existing agreements.
Read More: See How Key Person Insurance Works for a Business
When You Want to Cover a Mortgage
When shopping for mortgage life insurance, remember that survivors may want to pay off the home, continue making payments or sell the home and move. The amount of life insurance should reflect these options, not default to the mortgage balance.
Compare individual and creditor policies before buying. Differences include who owns the policy, who gets the proceeds, whether the death benefit decreases over time and whether you can take the policy with you if you sell the house or refinance with another creditor.
Read More: Compare Mortgage Insurance and Life Insurance
How Much Coverage Should I Get and for How Long?
Do not rely only on rules of thumb such as 10 to 12 times your income. Use a needs-based calculation to determine how much coverage you need.
Choose a term that matches the need you want to cover. You might buy one long-term policy or consider staged or staggered policies.
Read all of the policy provisions, including conversion options and renewal rates.
| Add | Subtract | Stress-test |
|---|---|---|
| Income or caregiving replacement for a chosen period | Savings and investments available to survivors | Inflation and a lower investment return |
| Mortgage or other debts you want cleared | Existing individual and workplace life insurance | A shorter or longer support period |
| Final, legal and estate costs | Survivor income and benefits you are confident will continue | The loss of a second income or caregiver |
| Education, business or legacy goals | Assets already dedicated to those goals | Premium affordability if income falls |
Read More: Estimate How Much Life Insurance You Need
Compare Insurance and Investing as Separate Decisions
A permanent life insurance policy may not be appropriate if the purchaser cannot comfortably make insurance premium payments for a long period. It may be more financially beneficial to pay off high-interest debt rather than invest money through life insurance.
Each form of investment, such as GICs, ETFs, mutual funds or real estate, serves a different purpose, has different tax implications and carries a different level of liquidity and risk. Make insurance and investing decisions separately. Speak with qualified financial, legal and tax advisers if you have complex estate or tax-planning needs.
| Decision | Evidence to request |
|---|---|
| How much coverage is needed? | Compare term quotes for the same insured person, amount and duration |
| What is guaranteed? | Guaranteed cash values, death benefits, premiums and surrender terms |
| What depends on assumptions? | Consider lower and current illustrated returns, dividends, charges and lapse risk |
| Can you keep funding it? | Compare the premium schedule, flexibility, loan effects and outcome if payments stop |
| What is the alternative? | Compare saving or investing after paying for the same protection |
Read More: Compare Buying Life Insurance and Investing