
A standard Canadian home policy commonly excludes direct earthquake damage. Some policies offer an earthquake coverage endorsement.
Be aware that many earthquake insurance policies come with hefty deductibles in the range of tens of thousands of dollars, often calculated as a percentage. Also, review your home or condominium policy before purchasing earthquake coverage.
Our content team reviewed Natural Resources Canada’s earthquake FAQ, its record of the 1949 magnitude 8.1 Haida Gwaii earthquake, the federal disaster-insurance guide, and Insurance Bureau of Canada’s home-coverage guide to write this guide.
Is Earthquake Damage Included In Canadian Home Insurance?
Most home insurance in Canada doesn’t cover earthquake damage. Some insurers offer earthquake insurance as an endorsement that, depending on the policy, covers damage to your home and possessions, plus additional living expense coverage.
According to the Insurance Bureau of Canada, ensuing losses like fire or explosion caused by earth movement are generally covered by a base home insurance policy even when direct earth movement is excluded. Always check your policy to determine what is included.
How Does Earthquake Insurance Work In Canada?
| Issue | What may happen | What to ask |
|---|---|---|
| Direct shaking | Usually excluded under the base policy, but may be added by endorsement. | Which building, contents and detached-structure limits apply? |
| Fire or explosion following earth movement | IBC says resulting fire or explosion is generally covered. | Which deductible applies and where is the ensuing-loss clause? |
| Water, tsunami or tidal wave | May have separate exclusions or limits. | Does any water endorsement apply to this source? |
| Additional living expense | When your home becomes unliveable due to insured earthquake damage, you may be covered. | What trigger, limit, time period and deductible apply? |
| Land, foundation and masonry | There may be other limitations to coverage. Land value is not insured. | Are foundations, masonry, stabilization, pools or landscaping limited or excluded? |
| Aftershocks | The contract may group shocks within an occurrence period. | How long is the occurrence window and how many deductibles can apply? |
Which Parts Of Canada Face The Highest Earthquake Risk?
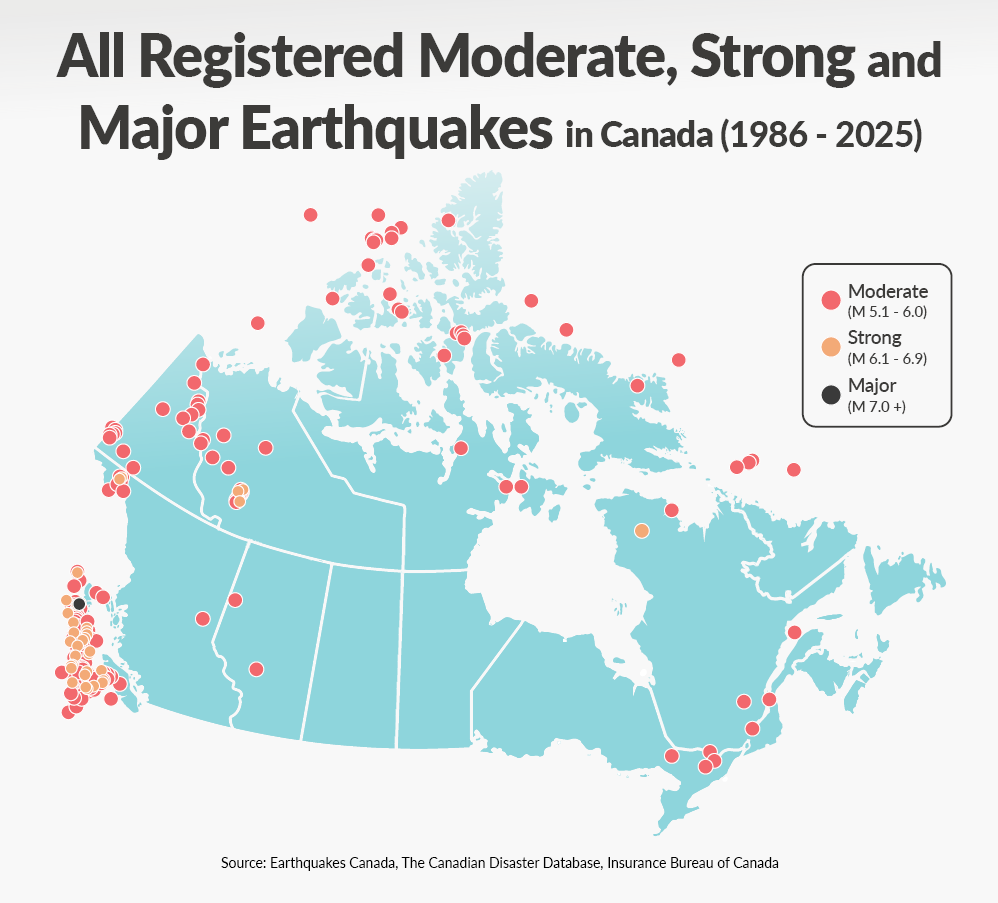
Natural Resources Canada records about 4,000 earthquakes in or near Canada each year. Canadians generally feel about 50.
The number of earthquakes does not indicate the likelihood of dangerous shaking in a given place. Assessing that possibility requires an understanding of seismic hazard, shaking, soil behaviour, vulnerability, exposure, and terminology.
New Brunswick is a known active seismic area recognized by Natural Resources Canada, but recent earthquakes in the region do not mean Atlantic Canada is becoming more vulnerable to earthquakes. NRCan also acknowledges an active seismic area in southern Newfoundland.
Earthquake hazard is greatest in British Columbia, including the coast and offshore areas. Other active areas include parts of the Yukon and the Mackenzie Valley, the Ottawa Valley, the St. Lawrence Valley (including areas near Montreal and Quebec City), and New Brunswick.
A magnitude-9 earthquake struck in 1700, but the largest earthquake recorded in Canada during historic times was the magnitude-8.1 earthquake that struck offshore Haida Gwaii in 1949. The magnitude-7.7 Haida Gwaii earthquake in 2012 was not the strongest modern-day quake in Canada.
Read More: See Which Canadian Communities Face Higher Earthquake Risk
What Impacts Your Earthquake Insurance Cost?
Your Location And Local Seismic Risk:
Seismic risk is based on many inputs. Use NRCan’s hazard information for context only. Ask your insurer how they arrived at a rating for your location, since proximity to previous recorded seismic activity is just one input.
The Age, Size, And Structure Of Your Home:
Do not promise a retrofit discount. Check with each insurer about which documents they accept and how they affect the quote.
Construction type, foundation, masonry, age, evidence of retrofitting, size, replacement cost and many other characteristics may impact pricing or damage potential.
Your Insurer’s Pricing Model:
Different insurers use different approaches to rate the same address. Get written quotes using the same coverage limits, deductibles and other inputs.
In addition to price, compare coverage details or wording. Sometimes one insurer won’t provide some types of coverage. Find out what they won’t cover.
Your Deductible Choice:
Compare the additional annual premium cost with the amount of loss you retain.
Selecting a lower percentage may not always be an option. Deductible options can affect premium cost.
Optional Coverage Included:
Check each of the following separately: building, contents, detached structures, additional living expense, condominium loss assessment, deductible assessment.
Do not assume land stabilization or other extras are covered unless they are specifically named in the endorsement.
Who Should Seriously Consider It?
- Any homeowner who could not afford a major structural loss above the calculated deductible
- Homeowners in higher-hazard areas where being able to rebuild is critical to household and mortgage stability
- Any condo/strata owner who would not be able to afford a corporation earthquake deductible or assessment not fully matched by their unit policy
- Any tenant that would not be able to afford to replace their belongings and pay associated living costs in the event an earthquake damaged their rental
- Anyone comparing disaster assistance with insurance, because assistance may not cover insurable losses.
Condo Owners
Ask the corporation for its certificate and earthquake deductible. Look at the declaration/bylaws or strata rules to determine how deductibles are assessed.
Say the condo has a $5 million earthquake deductible and 100 units – it’s not necessarily going to be assessed equally ($50,000). This will depend on unit entitlement, causation, the bylaws, provincial law, etc. Determine the highest possible assessment charge.
Do your earthquake loss-assessment and deductible-assessment sublimits cover the amount? Also, does your unit policy cover the corporation’s cause of loss?
Read More: Understand Condo Loss-Assessment Coverage
Tenants
Since tenants don’t insure the building, ask about earthquake insurance that covers damage to your possessions and additional living expenses. What are the limits and deductibles?
Ask if coverage would apply if the quake caused a blackout in your neighbourhood or rendered your street impassable. Coverage may not kick in unless there is insured physical damage to your apartment or its contents.
Why Having Earthquake Coverage Is Important
Provincial and territorial disaster financial assistance programs have limits, exclusions and eligibility requirements that vary by jurisdiction.
The FCAC also warns that government assistance may not be offered if earthquake insurance was available but not bought. Don’t count on government assistance instead of insurance.